Name and identifying number
The name and number from your tax return, the name and number of the entity that originally reported the contribution if different, and a box for a family pass-through entity.
8283
Noncash Charitable Contributions
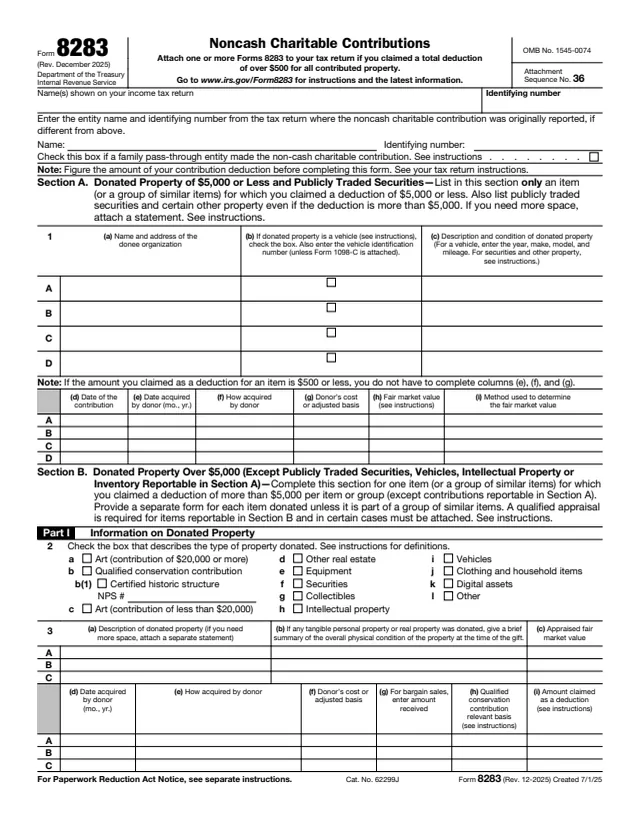
Form 8283, Noncash Charitable Contributions, reports information about property given to charity, such as clothing, household items, vehicles, securities, art, real estate or a conservation easement. The IRS About page says individuals, partnerships and corporations file it when the amount of their deduction for all noncash gifts is more than $500. The form says to attach one or more Forms 8283 to your tax return if you claimed a total deduction of over $500 for all contributed property.
The form has two sections. Section A covers items (or groups of similar items) with a deduction of $5,000 or less, plus publicly traded securities and certain other property. Section B covers property over $5,000 and has room for a qualified appraiser's declaration and the donee organization's acknowledgment.
The instructions say Form 8283 is not used to figure the deduction, and that out-of-pocket volunteer expenses and gifts by check or credit card are treated as cash contributions instead. You can fill out Form 8283 free in your browser on this page and download the result without an account.
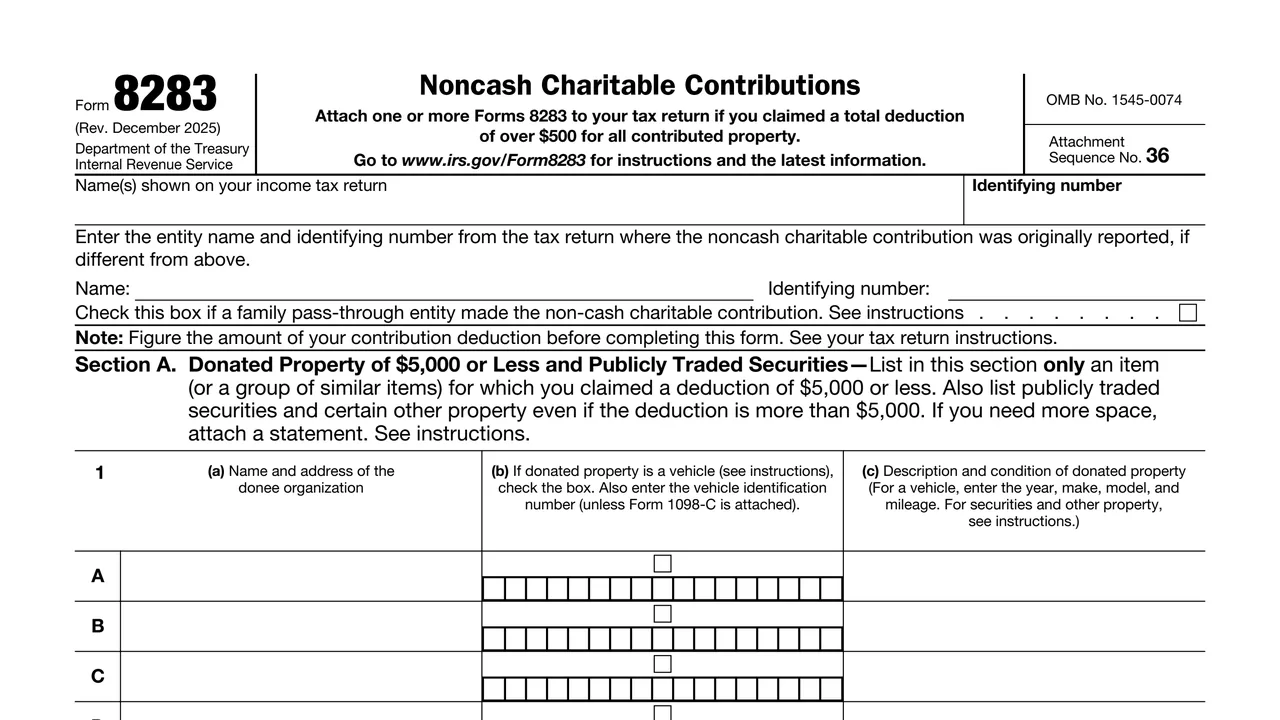
The name and number from your tax return, the name and number of the entity that originally reported the contribution if different, and a box for a family pass-through entity.
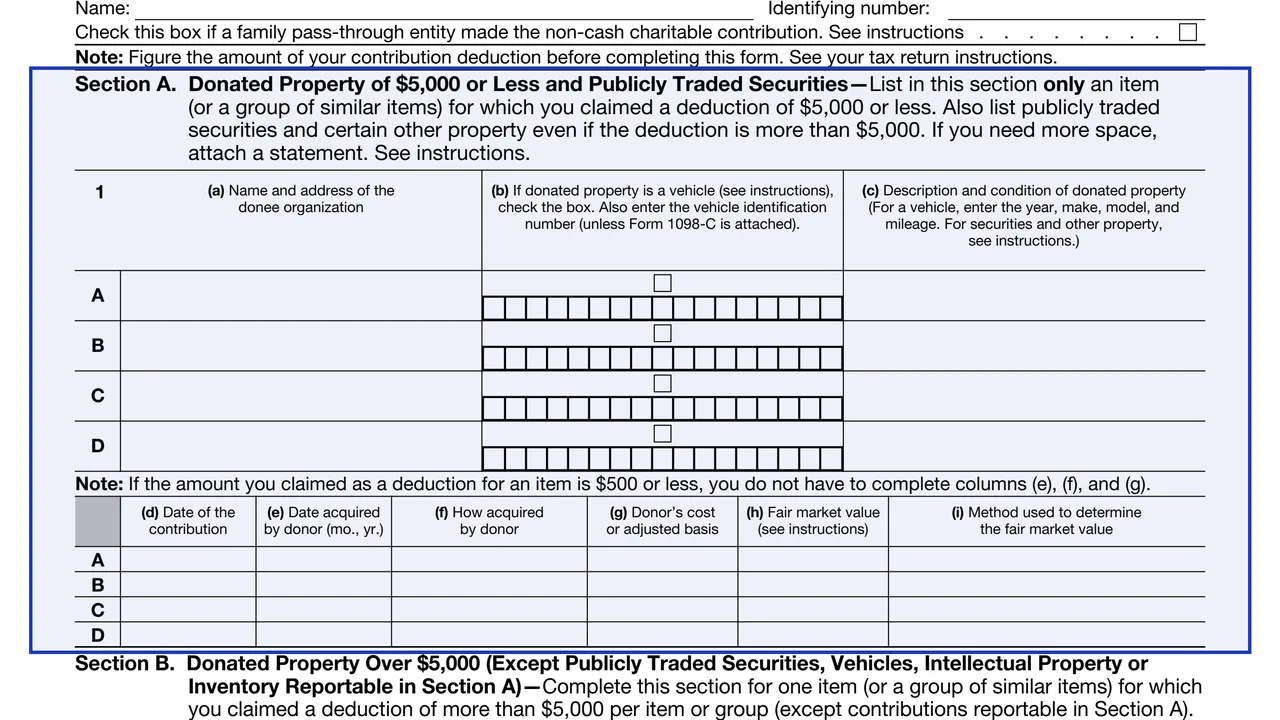
Up to four rows, A to D, for donated property of $5,000 or less and publicly traded securities: donee, vehicle box and VIN, description, dates, how acquired, cost, fair market value and the valuation method.
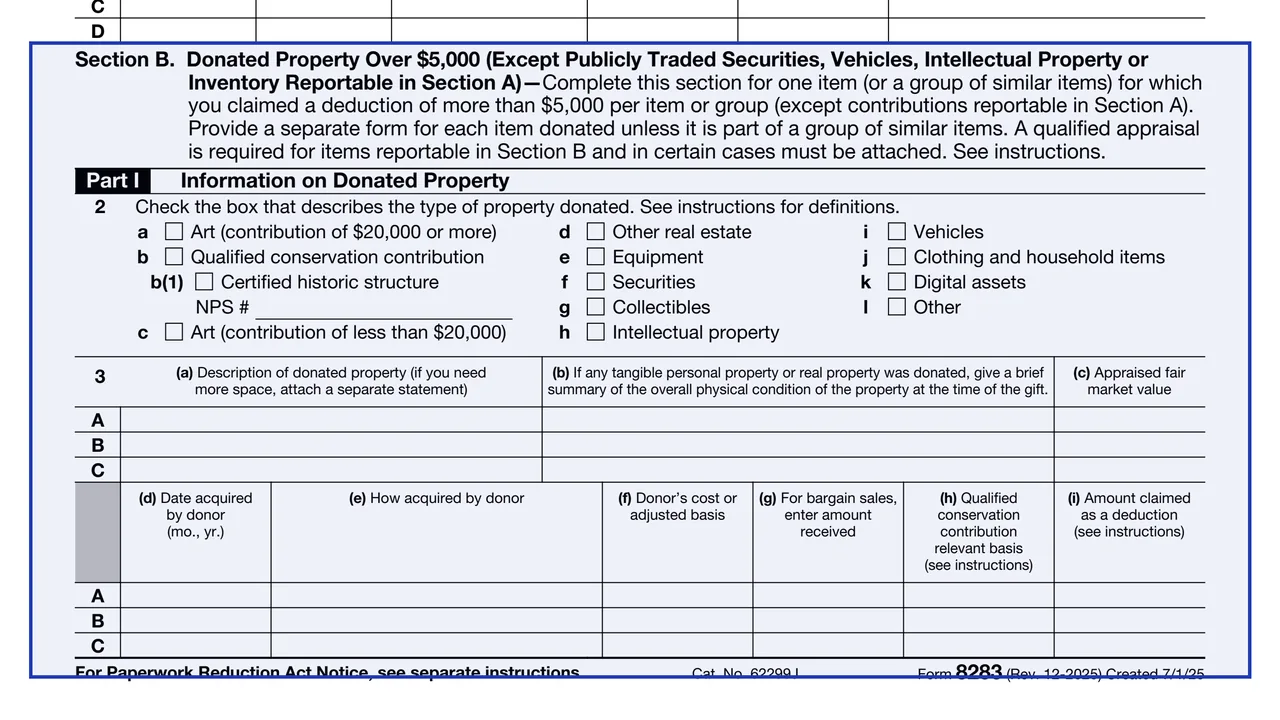
Line 2 checks the type of property, from art to digital assets. Line 3 describes each item, its condition, appraised fair market value, cost, bargain sale amount, relevant basis and amount claimed.
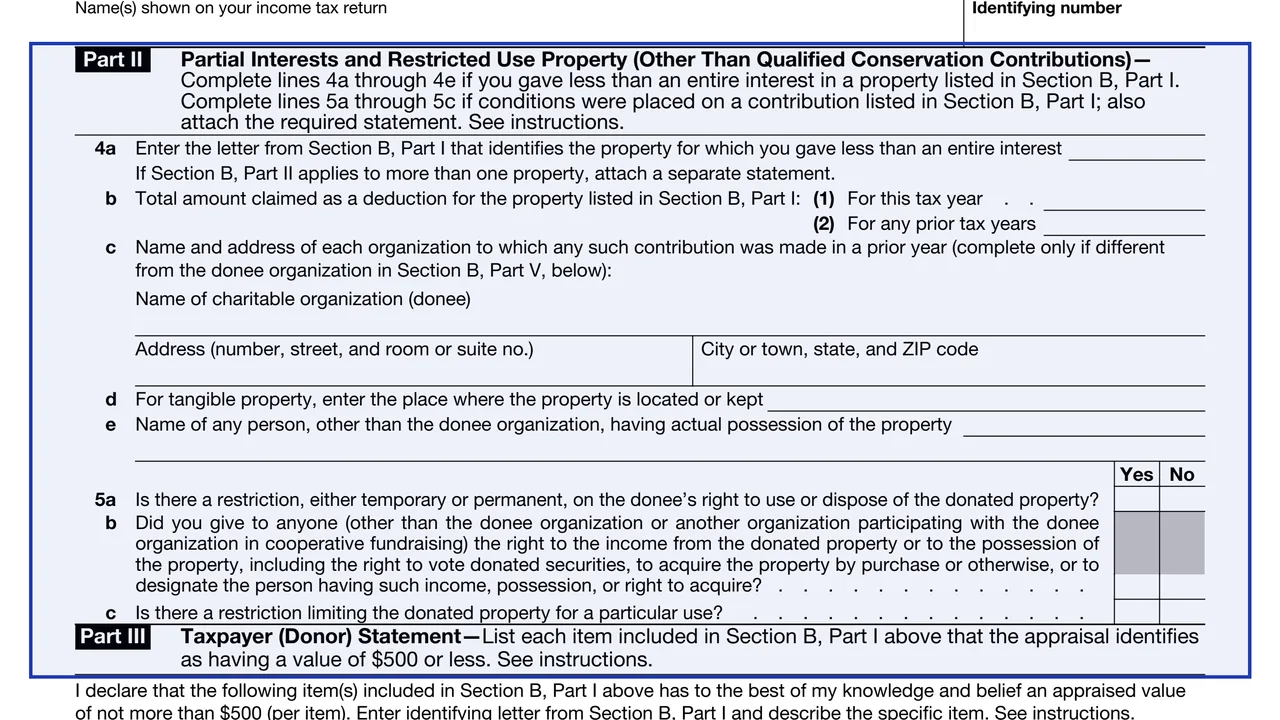
Lines 4a to 4e for giving less than an entire interest in a property, and lines 5a to 5c with Yes or No questions about restrictions on the donated property.
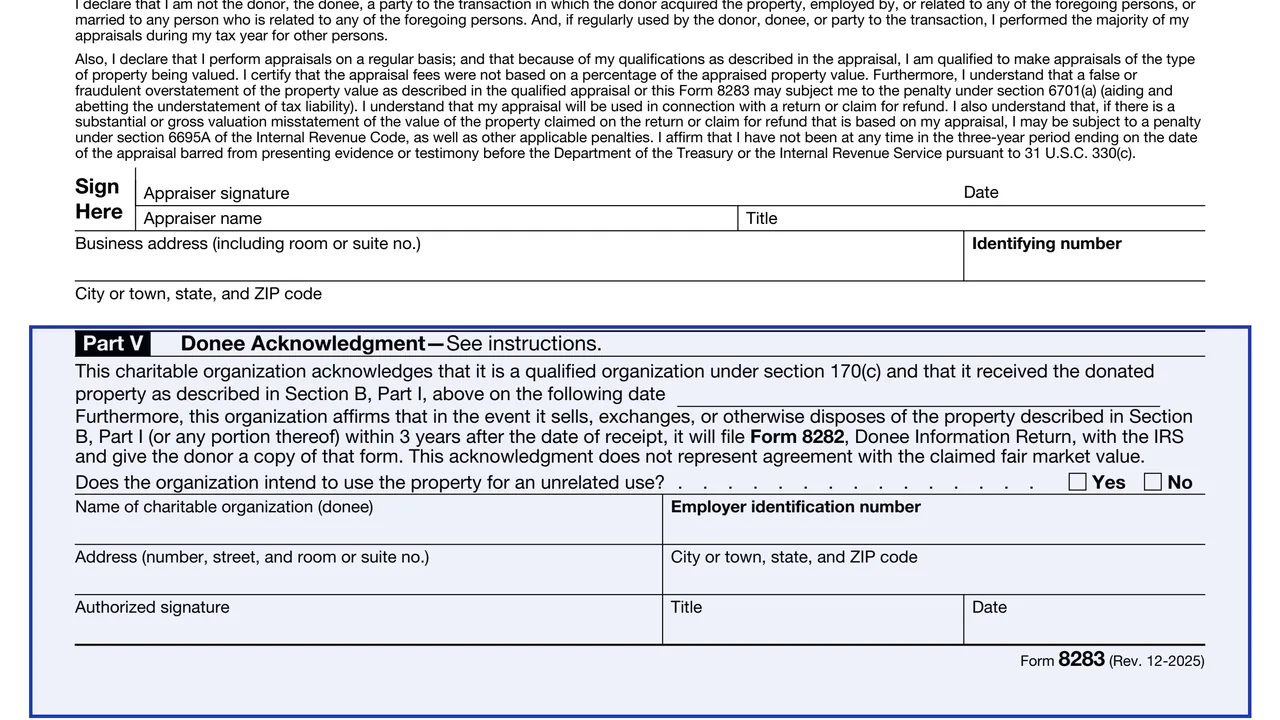
Part III is the donor's statement listing items the appraisal values at $500 or less. Part IV is the appraiser's declaration and signature.
The charity confirms it is a qualified organization under section 170(c), gives the date it received the property, says whether it intends an unrelated use, and signs.
The form says to figure the contribution deduction before completing it. Use Section A for items of $5,000 or less and publicly traded securities, and Section B for items or groups over $5,000.
The instructions say individuals enter an SSN or ITIN and other filers an EIN. A member of a pass-through entity also enters the name and EIN of the entity that originally reported the contribution.
Enter the donee and a description. For a vehicle, check the box and enter the VIN unless Form 1098-C is attached. Columns (e) to (g) can be skipped for items of $500 or less. Column (i) names the method, such as "Thrift shop value" or "Appraisal".
The instructions say a written qualified appraisal from a qualified appraiser comes before Part I. Check the property type on line 2 and complete line 3. A separate Section B is filed for each donee and each item or group of similar items.
Complete lines 4a to 4e for a partial interest and lines 5a to 5c if conditions were placed on the gift, with the required statement. In Part III, list any Section B item appraised at $500 or less and sign.
Before giving Section B to the donee, enter at least your name, identifying number and the property description. The donee signs Part V and returns the form, and the appraiser signs Part IV.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say Form 8283 is filed with the tax return for the year the property is contributed and the deduction is first claimed, and also for any carryover year described in section 170(d).
The instructions say the Form 8283 data goes in the electronic submission, and the completed form with the required signatures is attached as a PDF or mailed to the IRS with Form 8453.
The instructions list art with a deduction of $20,000 or more, a deduction of more than $500,000, clothing or household items not in good used condition claimed at more than $500, and certain easements on historic structures.
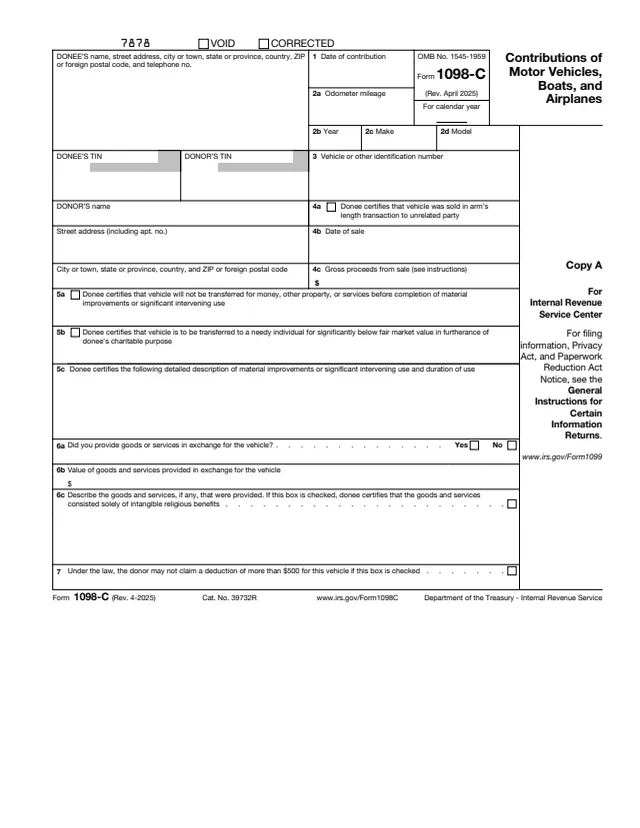
For a qualified vehicle claimed at more than $500, the instructions say to attach the donee's contemporaneous written acknowledgment, which can be Copy B of Form 1098-C.
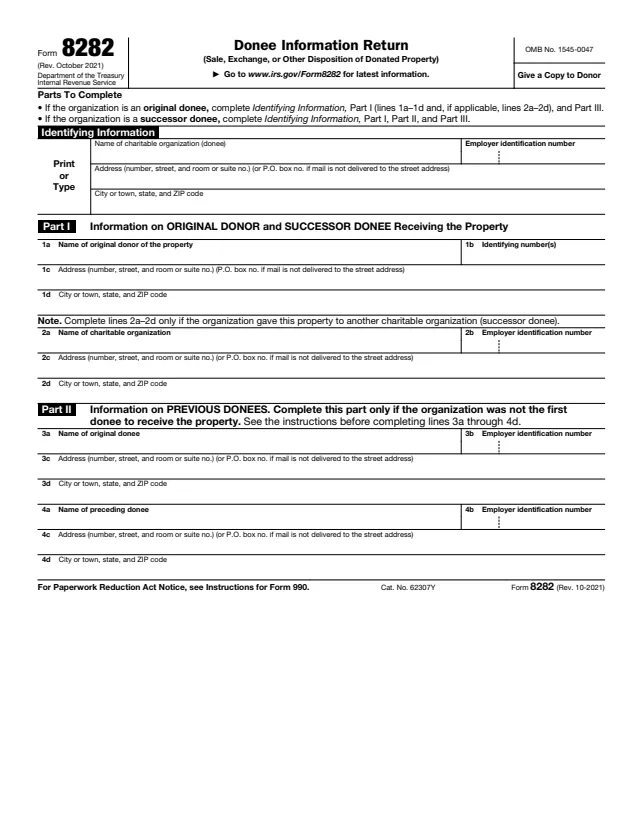
Part V says that if the donee disposes of Section B property within 3 years after receipt, it files Form 8282, Donee Information Return, with the IRS and gives the donor a copy.
The instructions say the deduction generally will be disallowed if a required Form 8283 is not attached or not fully completed, and that a blank entry or "available upon request" is nonresponsive.
8282
107 fields, 4 pages
1098-C
79 fields, 4 pages

1040
199 fields, 2 pages
1065
440 fields, 6 pages
1120-S
390 fields, 5 pages
8453
23 fields, 2 pages
The instructions say Form 8283 is filed by individuals, partnerships and corporations. In Section B, a qualified appraiser and the donee organization also complete and sign their own parts.
No tool matches that search.
The IRS About page says when the deduction for all noncash gifts is more than $500. The instructions add that a group of similar items with a total deduction over $500 also counts.
Section A is for items or groups of $5,000 or less, plus publicly traded securities, certain vehicles, intellectual property and inventory. Section B is for items or groups over $5,000.
No. The instructions say Form 8283 is an appraisal summary, not an appraisal, and a separate qualified appraisal is required for property reported in Section B.
No. The instructions say not to use it to figure the charitable contribution deduction, and point to the tax return instructions and Pub. 526.
The instructions say an official authorized to sign the organization's tax returns, or a person specifically designated to sign Form 8283.
The instructions say a completed copy of the prior year's Form 8283 is attached to the current return, plus a copy of any appraisal that had to be attached before.