Header
The decedent's name as it appears on Form 706 and the decedent's Social Security number.
706 Sch. U
Qualified Conservation Easement Exclusion
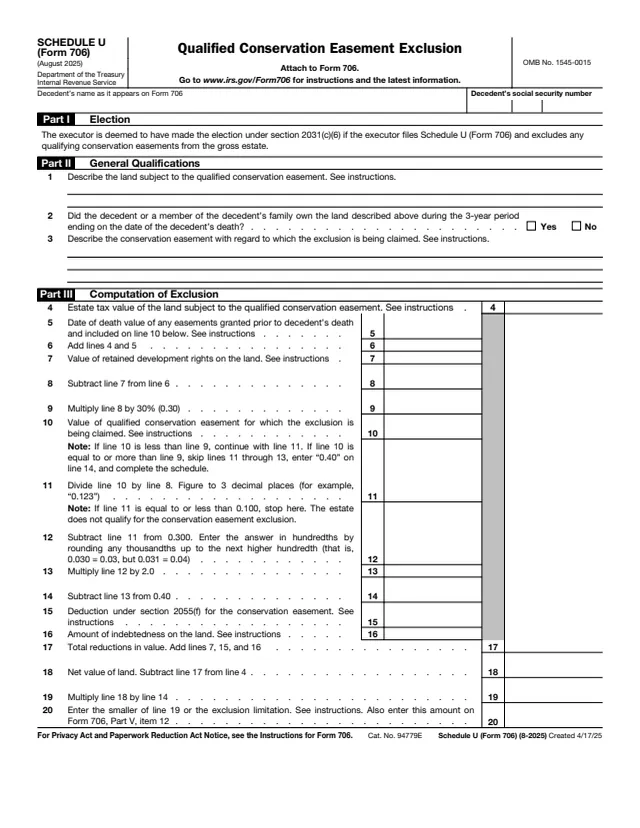
Schedule U (Form 706) is attached to Form 706, United States Estate (and Generation-Skipping Transfer) Tax Return. The IRS About page says it is used to make an election to exclude a portion of the value of land that is subject to a qualified conservation easement under section 2031(c). The executor of the estate completes it.
The form says the executor is deemed to have made the election under section 2031(c)(6) by filing Schedule U and excluding qualifying conservation easements from the gross estate. The instructions say the exclusion is the lesser of the applicable percentage of the value of the land (after certain reductions) or $500,000, that the election is made on a timely filed Form 706, including extensions, and that once made it is irrevocable.
The amount on line 20 is also entered on Form 706, Part V, item 12. You can fill out Schedule U free in your browser on this page and download the result without an account.
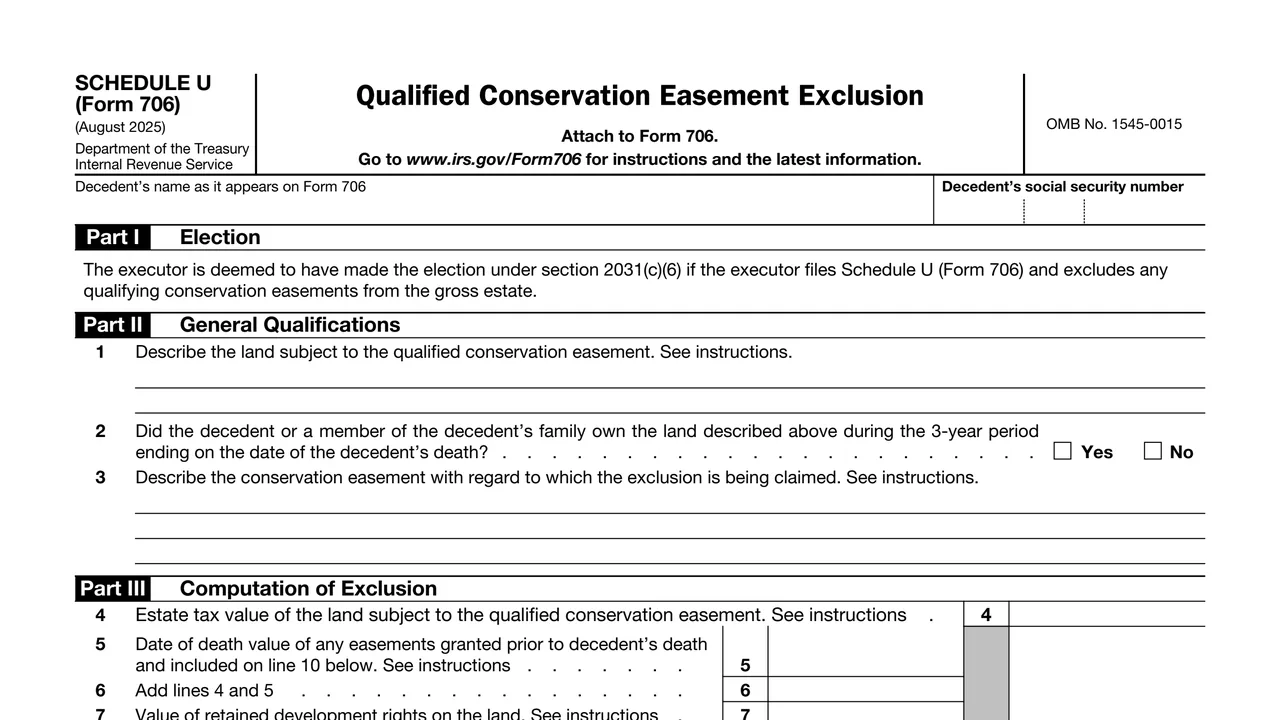
The decedent's name as it appears on Form 706 and the decedent's Social Security number.
A statement that the executor is deemed to have made the section 2031(c)(6) election by filing the schedule and excluding qualifying conservation easements.
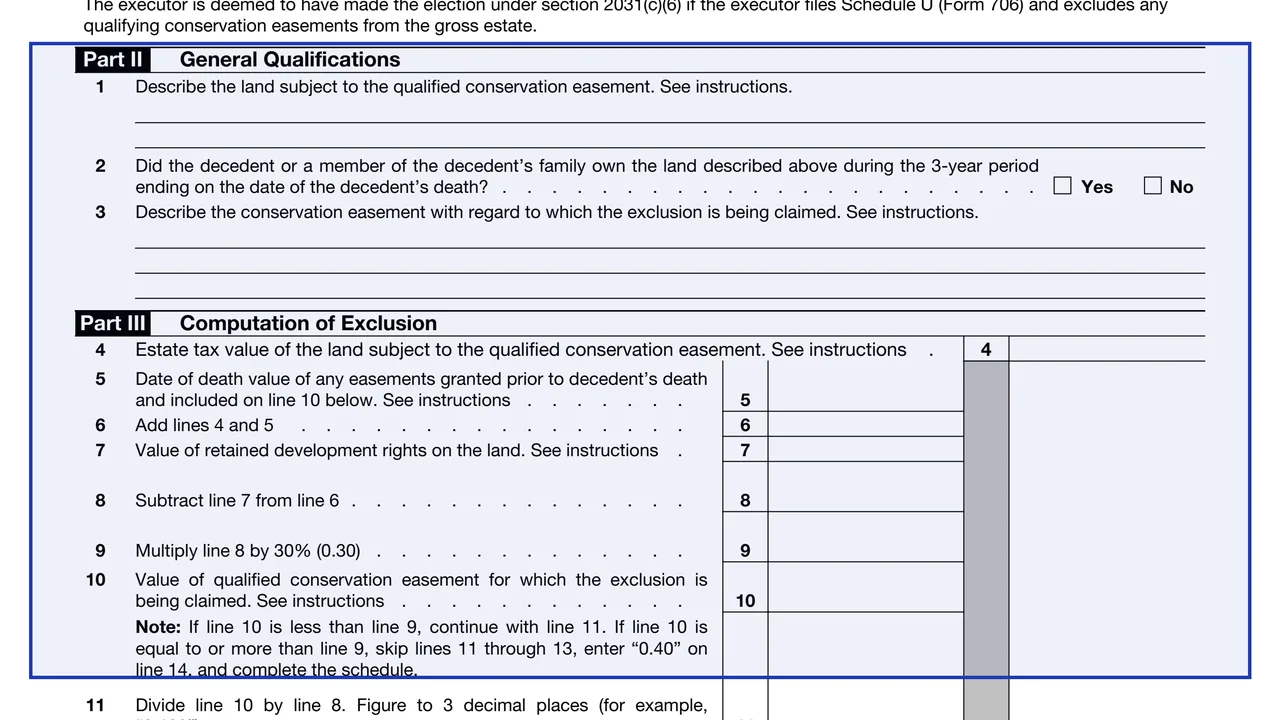
Line 1 describes the land, line 2 asks whether the decedent or a family member owned it during the 3-year period ending on the date of death, and line 3 describes the easement.
Estate tax value of the land, earlier easements, retained development rights, 30% of the net figure on line 9, and the value of the easement claimed on line 10.
A ratio of line 10 to line 8, figured to 3 decimal places, that sets the percentage on line 14. The form says the estate does not qualify if line 11 is equal to or less than 0.100.
Reductions for the section 2055(f) deduction and indebtedness, the net value of the land, and the exclusion on line 20, which also goes on Form 706, Part V, item 12.
If the land is reported as items on a Form 706 schedule, the instructions say to list the schedule, line numbers and item numbers, and to describe the part subject to the easement if it is only part of an item.
Answer Yes or No on line 2. On line 3, the instructions say to give enough information for the IRS to value the easement, including the date it was granted and by whom.
Line 4 is the gross value of the land from the asset schedule, not reduced by any mortgage. Line 5 is the date of death value of earlier qualifying easements. Line 7 is the value of retained development rights.
Subtract line 7 from line 6, multiply by 30% on line 9, and enter the easement value on line 10. The instructions say to explain how that value was determined and attach copies of any appraisals.
If line 10 is equal to or more than line 9, the form says to skip lines 11 through 13 and enter 0.40 on line 14. Otherwise follow the rounding rule on line 12 and multiply by 2.0 on line 13.
Enter any section 2055(f) deduction and the acquisition indebtedness, subtract the total reductions from line 4, multiply by line 14, and enter the smaller of line 19 or the exclusion limitation on line 20.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to Form 706." The Form 706 instructions give Department of the Treasury, Internal Revenue Service, Kansas City, MO 64999 as the filing address, and the About page points to Filing estate and gift tax returns for the latest address.
The instructions say the election is made on a timely filed Form 706, including extensions. They give a Form 706 due date of 9 months after the date of death, with Form 4768 for an automatic 6-month extension.
The instructions say that once made, the election is irrevocable.
If the easement, land or development right values at the time of contribution differ from the estate tax values, the instructions call for a separate computation on a copy of Schedule U, with "worksheet attached" entered at the top.
The instructions say to include the decedent's interest in the land on Schedule A, B, E, F, G or H of Form 706, as appropriate.
706
316 fields, 5 pages
706 Sch. A
223 fields, 2 pages
706 Sch. O
168 fields, 2 pages
706 Sch. T
858 fields, 8 pages
706 Sch. E
265 fields, 2 pages
706 Sch. G
268 fields, 2 pages
The executor of a decedent's estate completes Schedule U and attaches it to Form 706, which is filed with the IRS. The Form 706 instructions say the term executor includes the executor, personal representative or administrator of the estate.
No tool matches that search.
The executor of the estate completes it and attaches it to Form 706.
The form says the executor is deemed to have made the election under section 2031(c)(6) by filing Schedule U and excluding qualifying conservation easements from the gross estate.
The instructions say the exclusion is the lesser of the applicable percentage of the value of the land (after certain reductions) or $500,000.
No. The instructions say that once made, the election is irrevocable.
The form says that if line 11 is equal to or less than 0.100, the estate does not qualify for the conservation easement exclusion.
The form says to also enter it on Form 706, Part V, item 12.