Decedent's name and SSN
The decedent's name as it appears on Form 706 and the decedent's Social Security number.
706 Sch. P
Credit for Certain Foreign Taxes
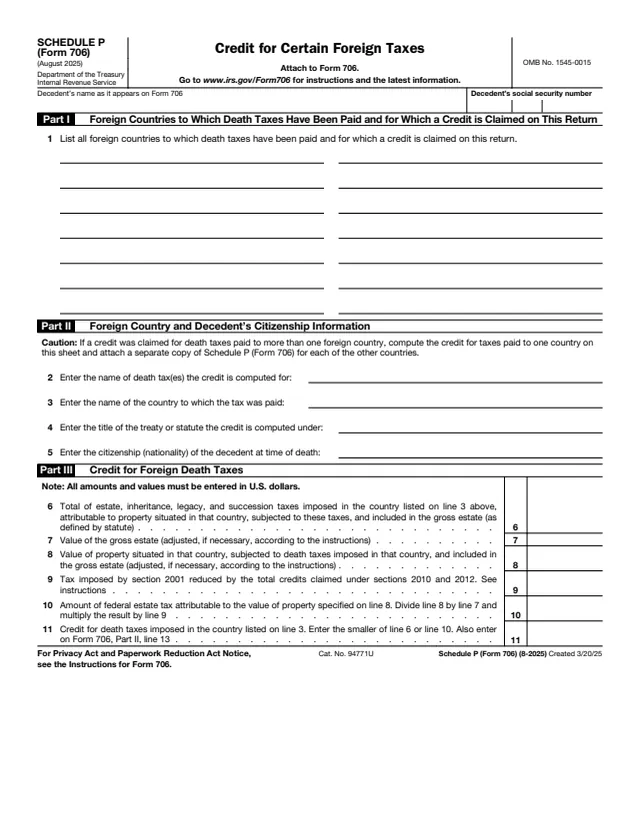
Schedule P (Form 706), Credit for Certain Foreign Taxes, is a one-page schedule attached to Form 706, the United States Estate (and Generation-Skipping Transfer) Tax Return. The IRS describes it as the schedule used to claim a credit for certain foreign taxes when authorized under a statute or a treaty.
The executor of a decedent's estate files Form 706. The Form 706 instructions say that if a credit is claimed on Form 706, Part II, line 13, Schedule P is completed and filed with the return, and Form(s) 706-CE are attached to support the credit. The credit for foreign death taxes is allowable only if the decedent was a citizen or resident of the United States, with the exceptions the instructions describe.
The schedule lists the foreign countries, names the tax, the country, the treaty or statute and the decedent's citizenship, then figures the credit in U.S. dollars on lines 6 to 11. You can fill out Schedule P free in your browser on this page and download it without an account.
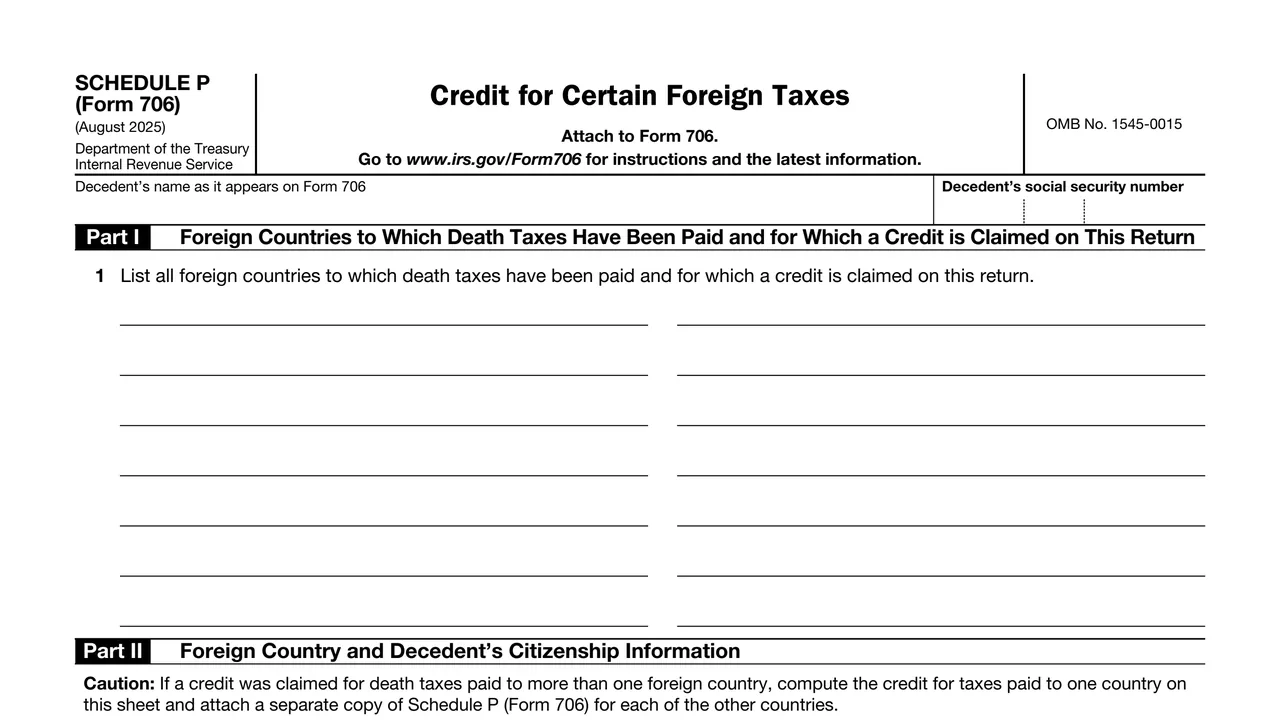
The decedent's name as it appears on Form 706 and the decedent's Social Security number.
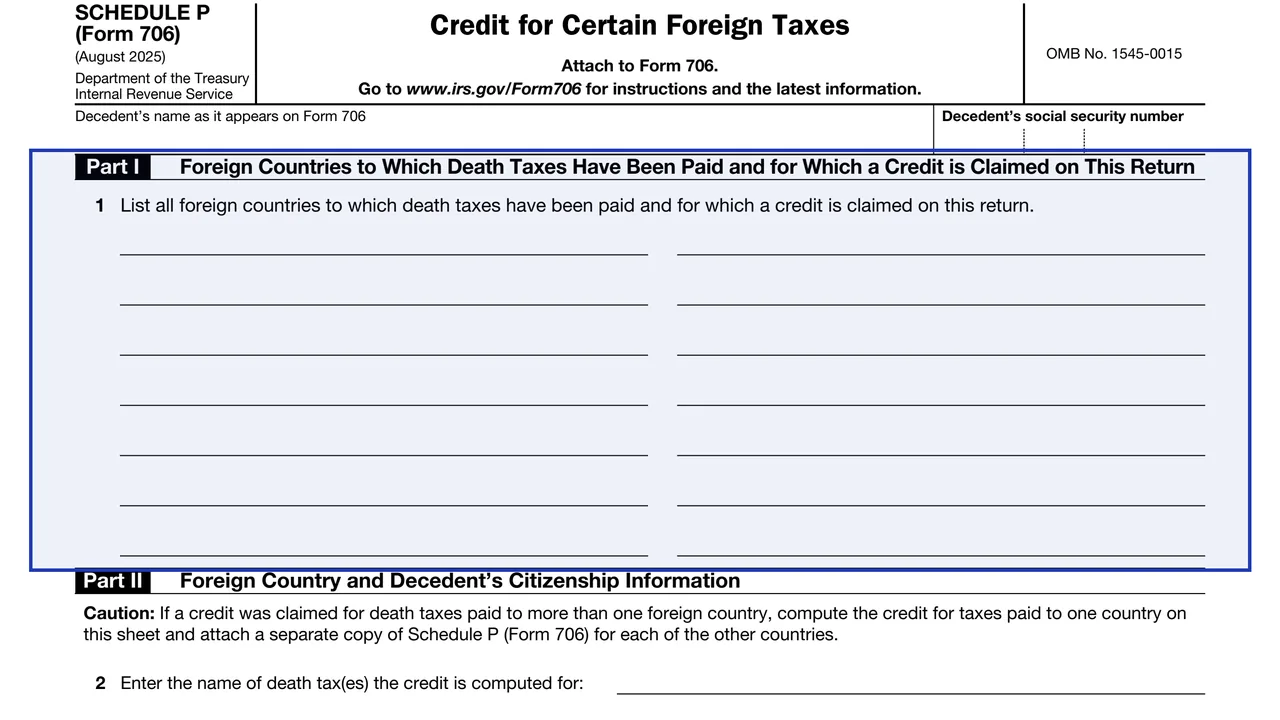
Line 1 lists all foreign countries to which death taxes have been paid and for which a credit is claimed on the return.
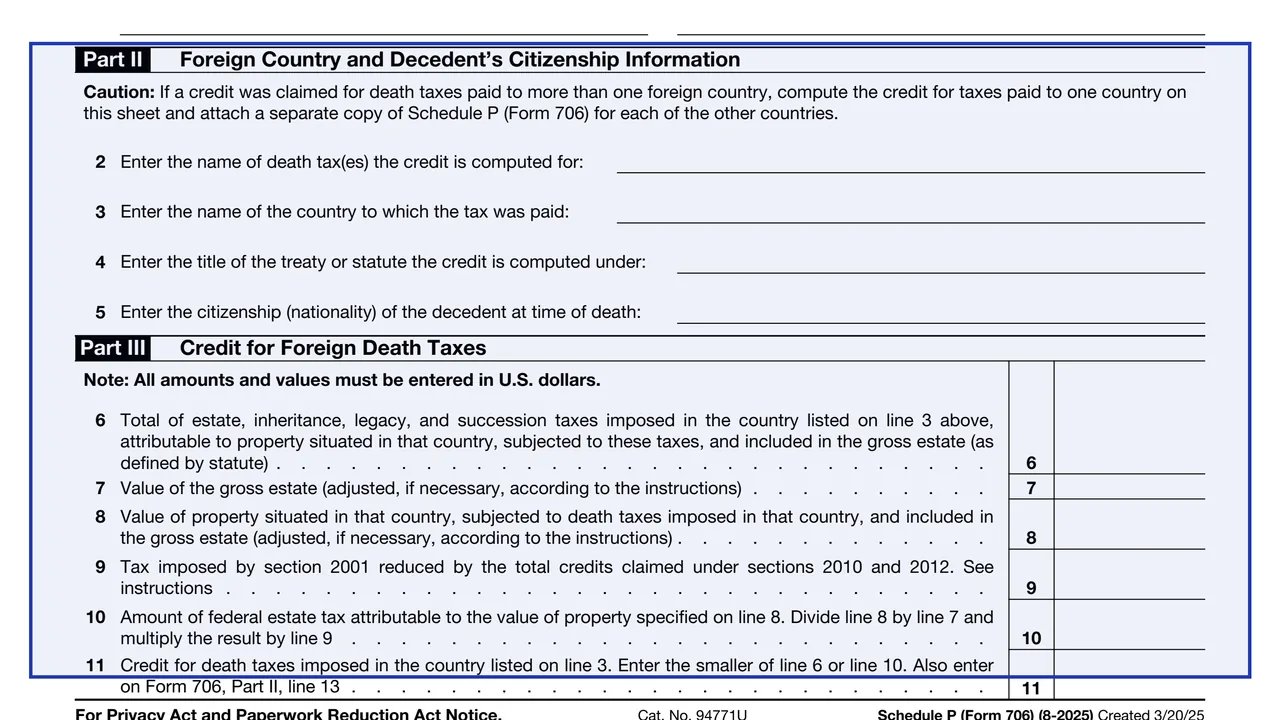
Lines 2 to 5 name the death tax, the country it was paid to, the treaty or statute the credit is computed under and the decedent's citizenship at death.
Lines 6 to 8 hold the foreign death taxes, the value of the gross estate and the value of property situated in that country, all in U.S. dollars.
Lines 9 to 11 figure the federal estate tax attributable to that property and the credit, which is the smaller of line 6 or line 10.
Enter the decedent's name as on Form 706 and the Social Security number, then list every foreign country on line 1 for which a credit is claimed.
On lines 2 to 5, name the death tax, the country, the treaty or statute and the decedent's citizenship. Use one sheet per country.
The instructions say to enter the death taxes paid to that country for property situated there, subjected to those taxes and included in the gross estate, and to attach the computation.
Line 7 is the gross estate less the deductions from Form 706, Part V, items 21 and 22. Line 8 is the value of the property in that country, less the parts of the Schedules M and O deductions that relate to it.
The instructions say to subtract Form 706, Part II, line 15 from line 12 for the statutory credit. For a treaty credit, the credit for tax on prior transfers on line 14 is also subtracted, so Schedule Q comes first.
Divide line 8 by line 7 and multiply by line 9 for line 10. Line 11 is the smaller of line 6 or line 10, also entered on Form 706, Part II, line 13.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Schedule P is not filed alone. The schedule says "Attach to Form 706," and the instructions say to file it with the return.
The instructions say to attach Form(s) 706-CE to Form 706 to support any credit claimed. If the foreign government refuses to certify Form 706-CE, it is filed directly with the IRS as Form 706-CE instructs.
The Form 706 instructions give the address Department of the Treasury, Internal Revenue Service, Kansas City, MO 64999. The About page also points to the IRS page on filing estate and gift tax returns for the latest address.
The instructions say Form 706 is filed within 9 months after the date of the decedent's death, and Form 4768 applies for an automatic 6-month extension of time to file.
The instructions say the credit is limited to foreign taxes actually paid and claimed within the later of 4 years after the return is filed, the end of any extension of time to pay, or 60 days after a final Tax Court decision on a timely petition.
The schedule says all amounts and values are entered in U.S. dollars. The instructions say to convert using the exchange rate in effect when each payment of foreign tax was made.
706
316 fields, 5 pages
706-CE
111 fields, 2 pages
706 Sch. Q
42 fields, 1 page
706-NA
259 fields, 3 pages
4768
35 fields, 1 page
706 Sch. W
303 fields, 2 pages
The executor completes Schedule P as part of the estate's Form 706. The Form 706 instructions say the term executor includes the executor, personal representative or administrator of the decedent's estate.
No tool matches that search.
The executor of the decedent's estate, as part of Form 706. The instructions say it is completed when a credit is claimed on Form 706, Part II, line 13.
Yes. The schedule says to compute the credit for one country per sheet and attach a separate copy of Schedule P for each of the other countries.
The instructions say Form(s) 706-CE are attached to Form 706 to support the credit, and the computation of the line 6 amount is also attached.
The instructions say the anticipated credit may be figured on the return, but it cannot finally be allowed until the foreign tax has been paid and a Form 706-CE evidencing payment is filed.
The instructions list Australia, Austria, Canada, Denmark, Finland, France, Germany, Greece, Ireland, Italy, Japan, the Netherlands, South Africa, Switzerland and the United Kingdom.
The instructions say section 2014(g) treats each U.S. territory as a foreign country for the foreign death tax credit.