Lines A to I
The tax year, the filer type, the name and EIN or SSN, the address with boxes for an address change or amended return, the related trust's name and EIN, and who keeps the books.
6069
Return of Certain Excise Taxes on Mine Operators, Black Lung Trusts, and Other Persons Under Sections 4951, 4952, and 4953
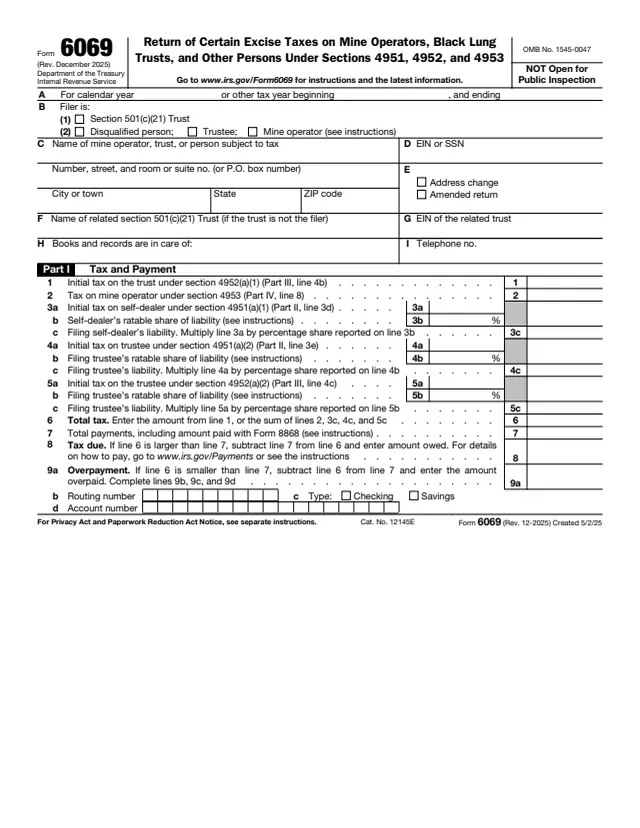
Form 6069, Return of Certain Excise Taxes on Mine Operators, Black Lung Trusts, and Other Persons Under Sections 4951, 4952, and 4953, is a return for section 501(c)(21) trusts (black lung benefit trusts), their trustees, disqualified persons and coal mine operators.
The IRS About page says the form is primarily a worksheet used to determine the maximum allowable income tax deduction under section 192 for contributions made by coal mine operators to tax-exempt black lung benefit trusts. It is also used to determine the excise tax imposed under section 4953 on contributions that are more than that maximum deduction. The form also covers the initial taxes on self-dealing (section 4951) and on taxable expenditures (section 4952).
The form is marked "NOT Open for Public Inspection" and says to go to www.irs.gov/Form6069 for instructions. You can fill out Form 6069 free in your browser on this page and download the result without an account.
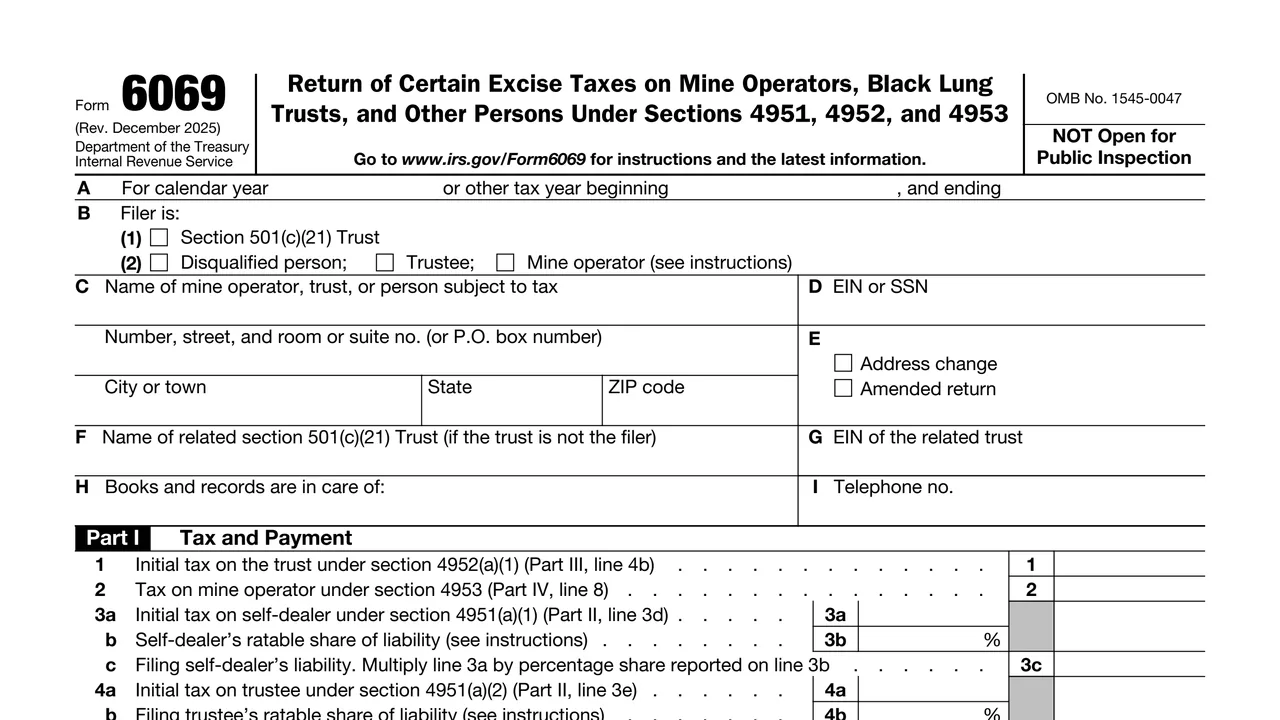
The tax year, the filer type, the name and EIN or SSN, the address with boxes for an address change or amended return, the related trust's name and EIN, and who keeps the books.
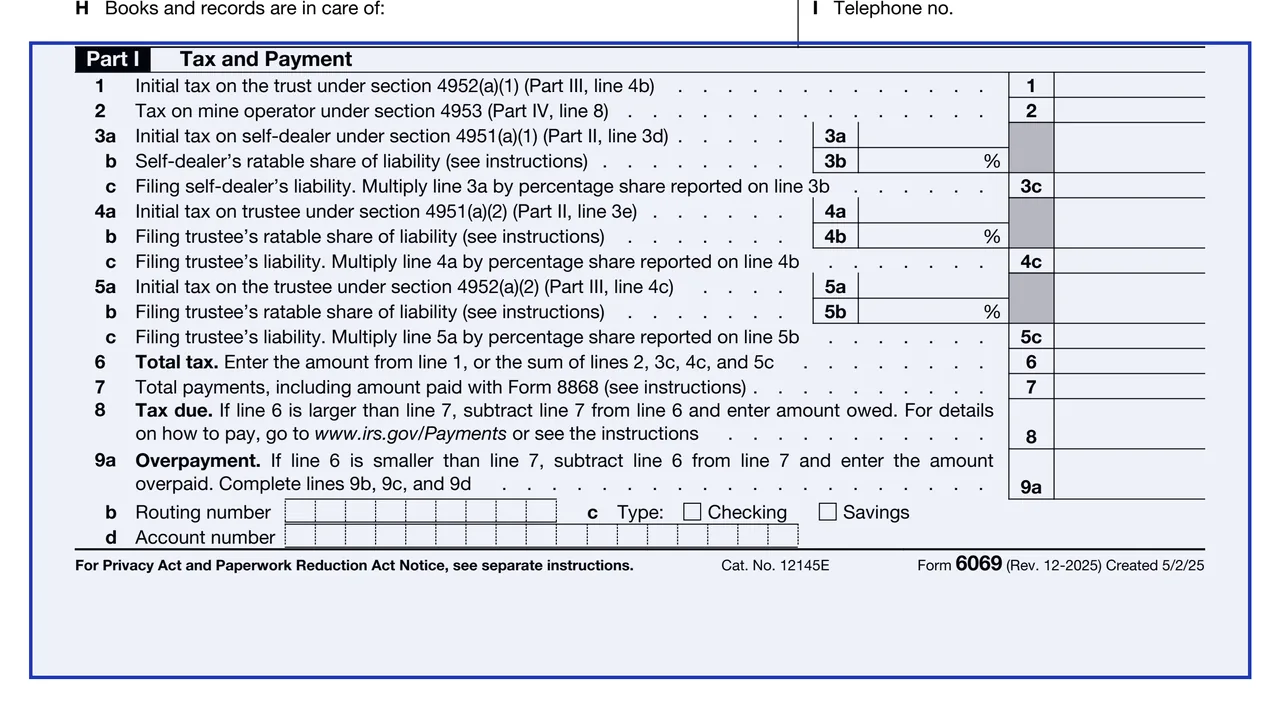
Lines 1 to 6 total the taxes from the other parts, with ratable share percentages on lines 3b, 4b and 5b. Lines 7 to 9 show payments, tax due or an overpayment, with a routing number, account type and account number on lines 9b to 9d.
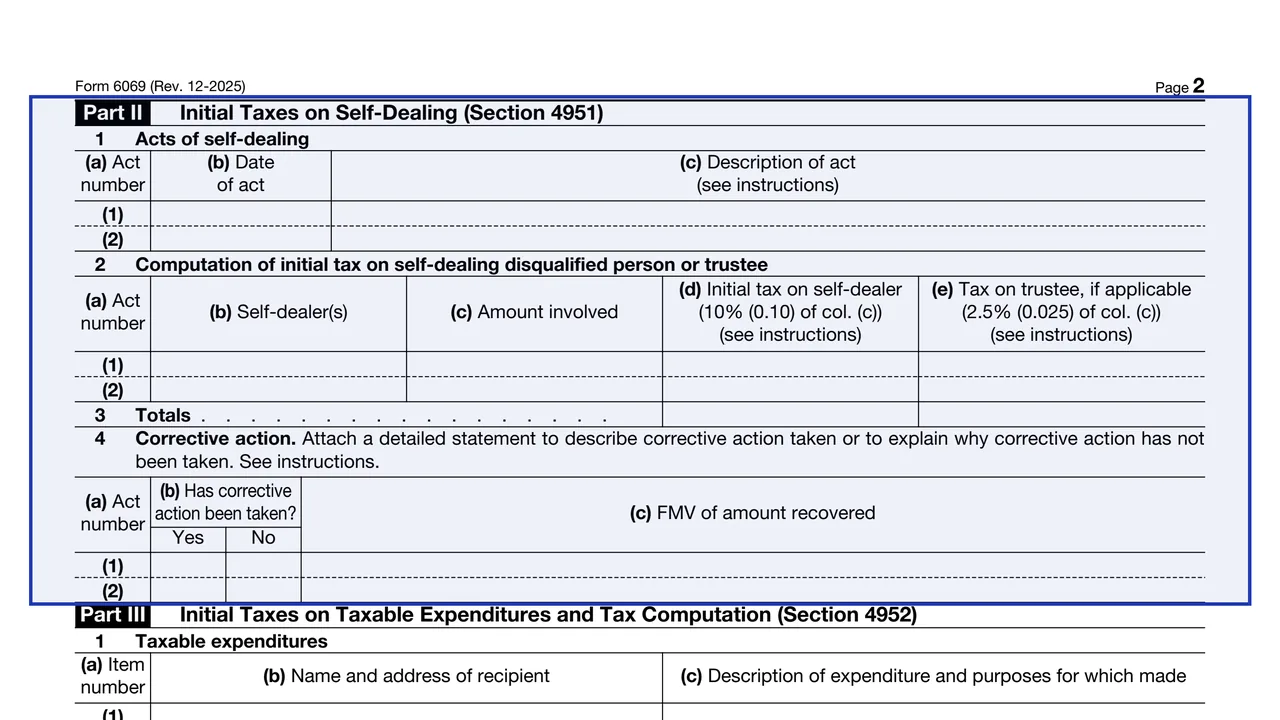
Each act of self-dealing with its date and description, the self-dealers, the amount involved, the initial tax at 10% (0.10) and the trustee tax at 2.5% (0.025), and corrective action.
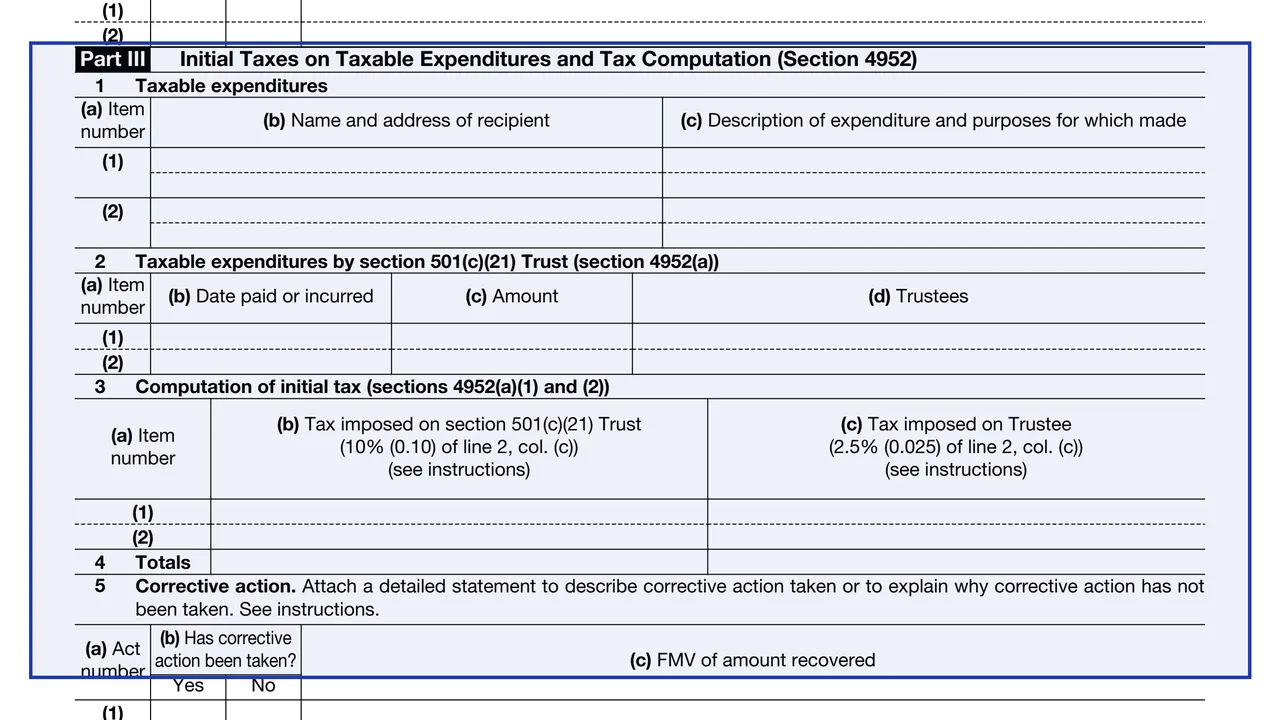
Each taxable expenditure with its recipient, purpose, date, amount and trustees, the tax on the trust at 10% (0.10) and on the trustee at 2.5% (0.025), and corrective action.
Lines 1 to 3b figure the operator's maximum section 192 deduction. Lines 3c to 7 figure excess contributions, and line 8 is the tax at 5% (0.05) of line 7.
A signature line for the trustee with title, several lines for each trustee, self-dealer or mine operator, and the paid preparer section.
Enter the calendar or other tax year, check the filer type in box B, and enter the name, EIN or SSN and address. If the trust is not the filer, name the related section 501(c)(21) trust and its EIN on lines F and G.
List each act with its date and description, then each self-dealer and the amount involved. Column (d) is 10% of column (c) and column (e) is 2.5% for the trustee. The form asks for an attached statement on corrective action.
List each expenditure, its recipient and purpose, the date and amount and the trustees. Figure 10% of the amount for the trust and 2.5% for the trustee, and attach the corrective action statement.
Work through lines 1a to 3b to reach the maximum allowable deduction, then lines 3c to 7 for excess contributions. Line 8 is 5% of line 7 and also goes on Part I, line 2.
Carry the taxes to lines 1 to 5c, using each filer's ratable share on lines 3b, 4b and 5b. Line 6 is the total tax and line 7 the payments, including any amount paid with Form 8868. Complete line 8 or lines 9a to 9d.
The trustee signs with title and date, and each trustee, self-dealer or mine operator signs with the organization or entity name if applicable. A paid preparer completes the preparer section.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form refers to separate instructions and says to go to www.irs.gov/Form6069 for instructions and the latest information. Several lines say "see instructions", including the ratable shares and Part IV.
Line 8 shows tax due when line 6 is larger than line 7. The form says to go to www.irs.gov/Payments or see the instructions for details on how to pay.
An overpayment on line 9a is completed with the routing number, account type and account number on lines 9b, 9c and 9d.
Part II, line 4 and Part III, line 5 ask for a detailed statement describing corrective action taken, or explaining why it has not been taken.
Line 7 includes any amount paid with Form 8868. Box E has checkboxes for an address change and an amended return.
Box B on the form names the filer: a section 501(c)(21) trust, or a disqualified person, trustee or mine operator. Lines F and G name the related trust when the trust is not the filer.
No tool matches that search.
The IRS About page says it is primarily a worksheet to determine the maximum section 192 deduction for coal mine operators' contributions to black lung benefit trusts, and the section 4953 excise tax on contributions above that amount.
Box B lists a section 501(c)(21) trust, a disqualified person, a trustee or a mine operator.
The form prints 10% (0.10) and 2.5% (0.025) for the self-dealer and trustee in Part II, 10% and 2.5% for the trust and trustee in Part III, and 5% (0.05) of excess contributions in Part IV.
No. The top of the form says "NOT Open for Public Inspection."
The form says the instructions are separate and to go to www.irs.gov/Form6069 for instructions and the latest information.
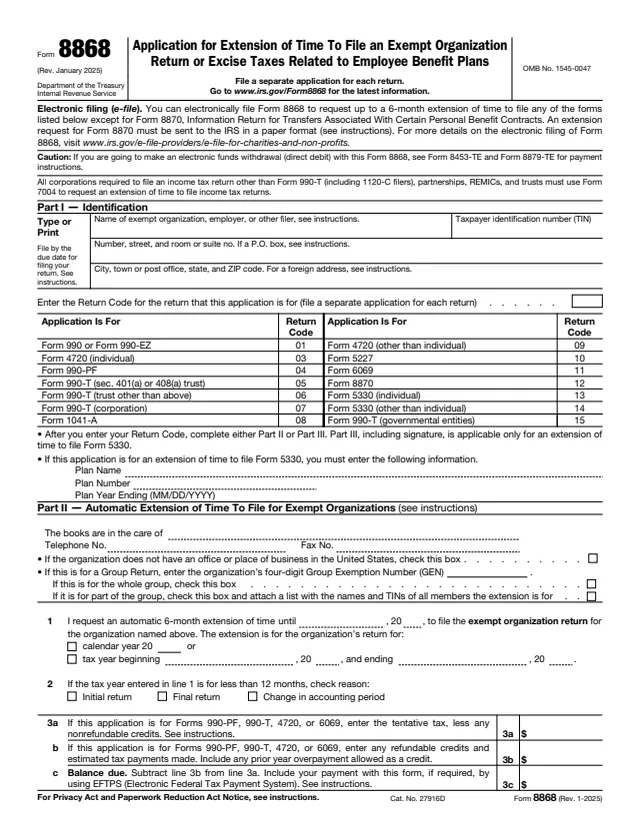
Line 7, total payments, includes the amount paid with Form 8868, the application for extension of time to file.