Name and SSN
The name shown on the return and the social security number. The instructions say each spouse enters only their own name and number on their own form.
5405
Repayment of the First-Time Homebuyer Credit
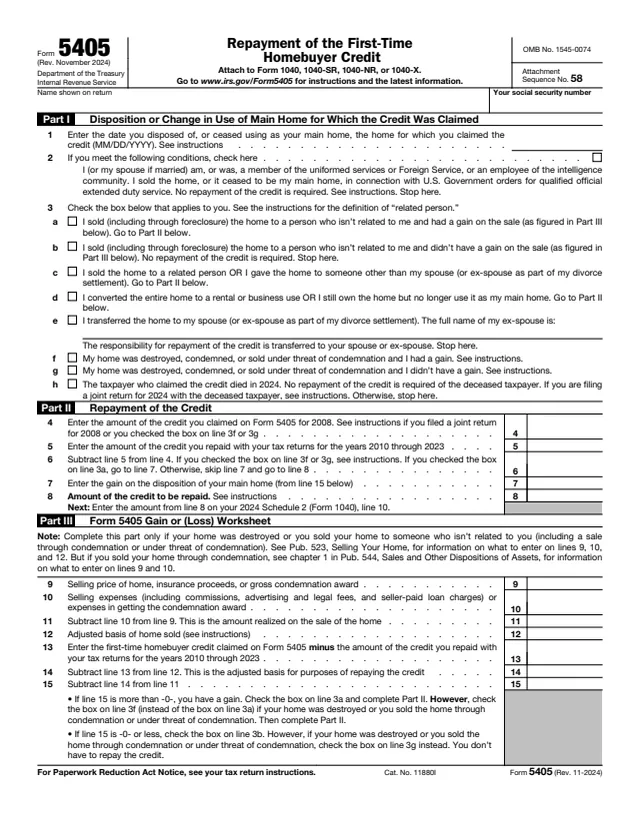
Form 5405, Repayment of the First-Time Homebuyer Credit, is attached to Form 1040, 1040-SR, 1040-NR or 1040-X. The instructions say it is used to notify the IRS that a home purchased in 2008, for which the credit was claimed, was disposed of or ceased to be the main home in 2024, and to figure the amount of the credit to repay with the 2024 tax return.
It is an individual taxpayer's form. The instructions say the repayment requirement has expired for homes purchased after 2008 and continues to apply to homes purchased in 2008, whose 15-year repayment period began with the 2010 tax return and ends with the 2024 tax return. They also say 2024 is the last year to file Form 5405 and the 2024 revision is its last revision. The IRS About page lists a recent development titled "Form 5405 will no longer be revised".
Part I records what happened to the home, Part II figures the repayment and Part III is a gain or loss worksheet. You can fill out Form 5405 free in your browser on this page and download the result without an account.
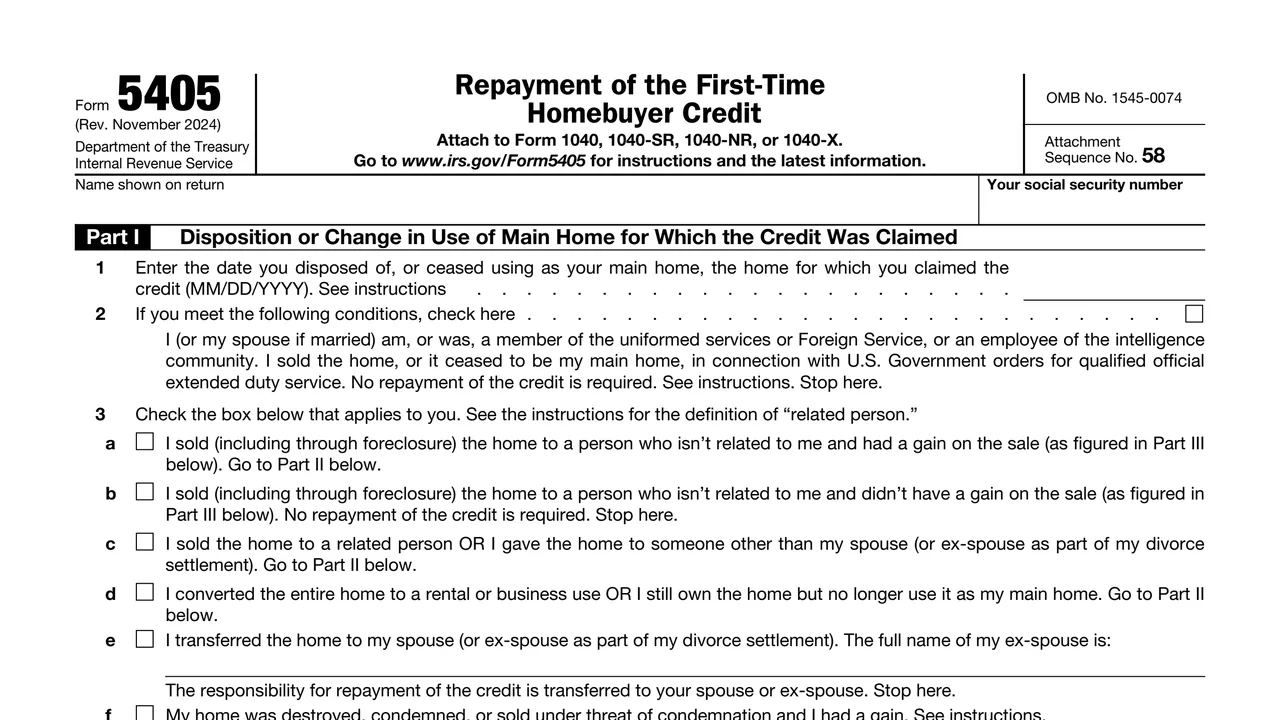
The name shown on the return and the social security number. The instructions say each spouse enters only their own name and number on their own form.
Line 1 is the date the home was disposed of or stopped being the main home (MM/DD/YYYY). Line 2 is a check box for qualified official extended duty under U.S. Government orders.
Eight boxes, 3a to 3h: sale to an unrelated person with or without a gain, sale to a related person or a gift, conversion to rental or business use, transfer to a spouse, destruction or condemnation with or without a gain, and death of the taxpayer.
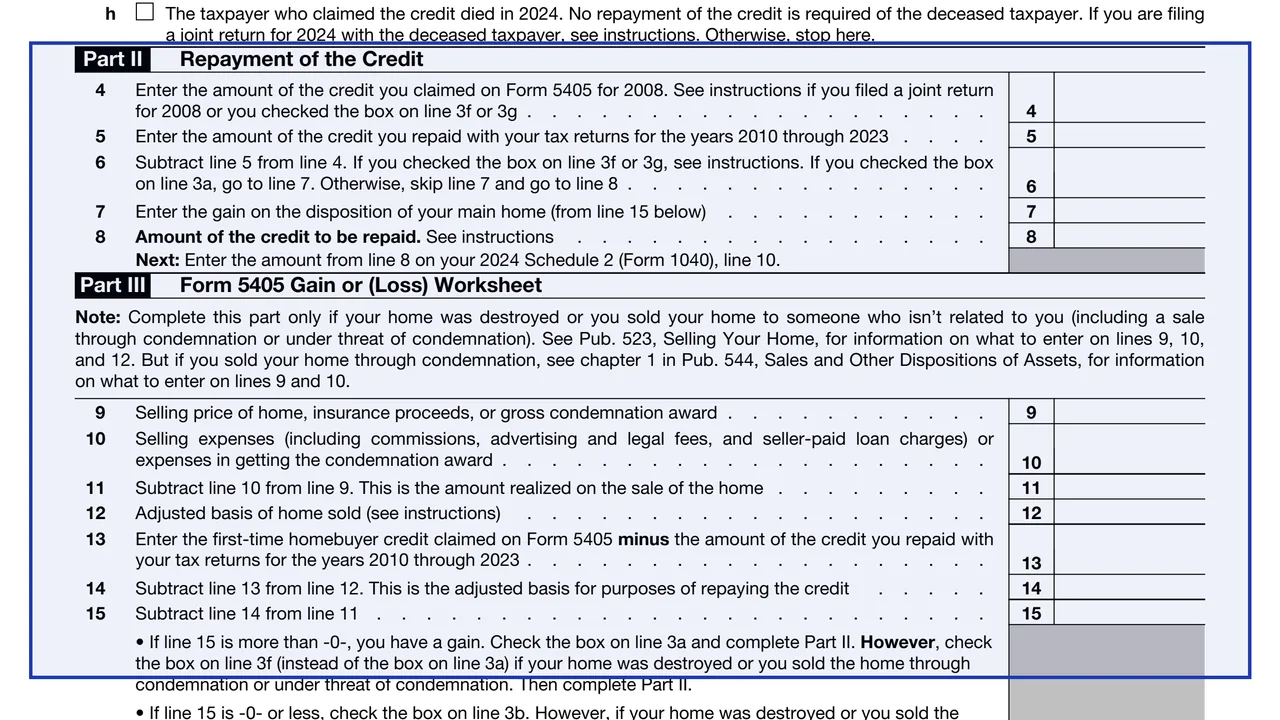
Lines 4 to 8: the credit claimed on Form 5405 for 2008, the amount repaid with the 2010 through 2023 returns, the balance, the gain from line 15 and the amount to be repaid.
Lines 9 to 15: selling price or award, selling expenses, amount realized, adjusted basis, credit claimed minus amounts repaid, the adjusted basis for repaying the credit, and the gain or loss.
Enter the date the home was disposed of or ceased to be the main home. For a destroyed or condemned home, the instructions say to use the date of that event or the date it ceased to be the main home, whichever is earlier.
Check line 2 if its conditions apply and stop. Otherwise check the one box on line 3 that applies, and follow the form's note after it to go to Part II or stop.
Complete lines 9 to 15 if the home was destroyed or sold to someone who isn't related. The instructions say line 12 is line 6 of Worksheet 2 in Pub. 523. A gain on line 15 points to box 3a or 3f, zero or less to 3b or 3g.
Enter the credit claimed for 2008 and the amount repaid with the 2010 through 2023 returns, then subtract. The instructions cover joint returns, a deceased spouse and a transfer between spouses for line 4. Line 7 takes the gain from line 15 when box 3a or 3f applies.
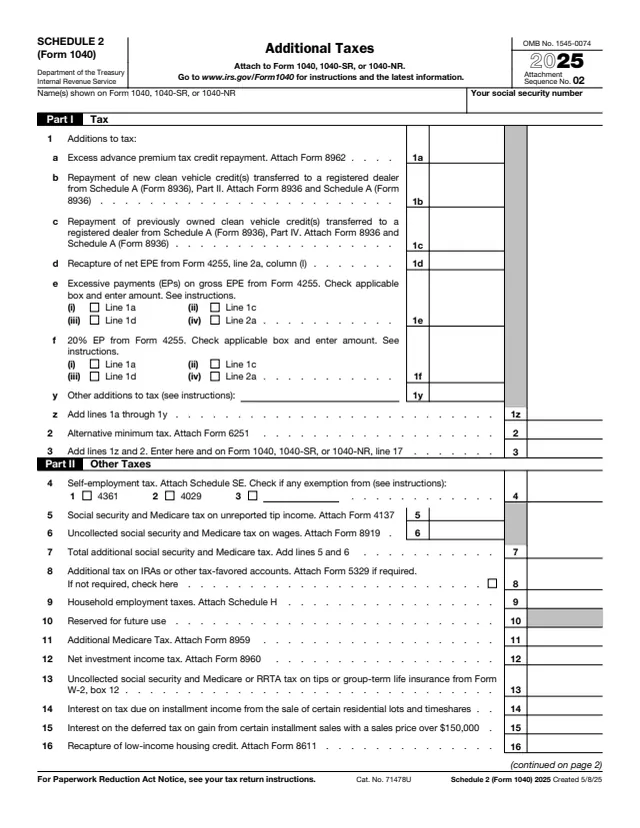
The instructions say to enter the smaller of line 6 or line 7 after box 3a, and line 6 after box 3c or 3d. The form says the line 8 amount goes on 2024 Schedule 2 (Form 1040), line 10.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 1040, 1040-SR, 1040-NR or 1040-X, and the instructions say it is filed with the 2024 tax return.
The instructions say 2024 is the last year to file Form 5405, because the 15-year repayment period for homes purchased in 2008 ends with the 2024 tax return.
For a sale, including through foreclosure, the instructions say the credit is repaid with the return for the tax year the sale is completed, generally when the purchaser or lender obtains title.
The instructions say at least one-fifteenth of the credit is repaid with every return during the repayment period, and a taxpayer who repaid more with a prior return may have a final 2024 payment below the minimum.
The instructions say Form 5405 is filed with the 2024 tax return by a taxpayer who purchased the home in 2008 and disposed of it, or ceased using it as the main home, in 2024. They list exceptions and cases where no form is filed.
No tool matches that search.
The instructions say it is filed with the 2024 tax return by a taxpayer who purchased the home in 2008 and disposed of it, or ceased using it as the main home, in 2024, subject to listed exceptions.
No. The instructions say a taxpayer who owned and used the home as the main home during all of 2024 enters the repayment on 2024 Schedule 2 (Form 1040), line 10 without filing Form 5405.
The instructions say the repayment requirement has expired for homes purchased after 2008 and continues to apply to homes purchased in 2008.
Yes. The instructions say 2024 is the last year to file Form 5405 and the 2024 revision is the last revision of the form and its instructions.
The form says to check line 3b, and that no repayment of the credit is required. Part III is used to figure whether there was a gain.
The instructions say repayment of the remaining balance isn't required unless the credit was claimed on a joint return, in which case the surviving spouse continues repaying their half if no other exception applies.