Employer name
The opening line where the employer's name goes before the words "makes the following agreement under section 408(k)."
5305-SEP
Simplifies Employee Pension-Individual Retirement Accounts Contribution Agreement
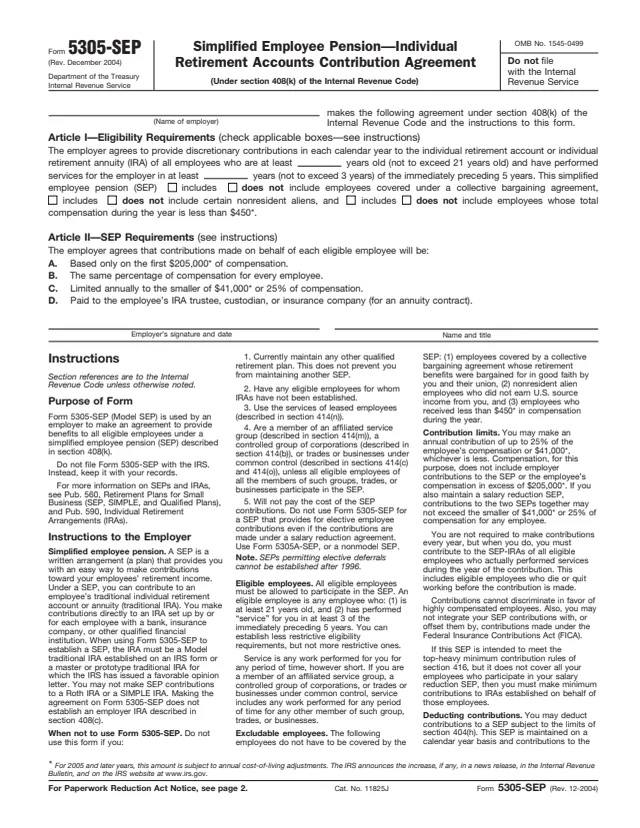
Form 5305-SEP, the Simplified Employee Pension-Individual Retirement Accounts Contribution Agreement, is what the IRS calls the Model SEP. The instructions say it is used by an employer to make an agreement to provide benefits to all eligible employees under a simplified employee pension (SEP) described in section 408(k).
Under a SEP, the employer contributes to a traditional IRA set up by or for each employee with a bank, insurance company or other qualified financial institution. The form has the employer's name, Article I on eligibility, Article II on SEP requirements and the employer's signature, followed by Instructions to the Employer and Information for the Employee.
The form says "Do not file Form 5305-SEP with the IRS. Instead, keep it with your records." This is the December 2004 revision. Amounts marked with an asterisk are, as the form says, subject to annual cost-of-living adjustments for 2005 and later years. You can fill it out free in your browser on this page and download the result without an account.
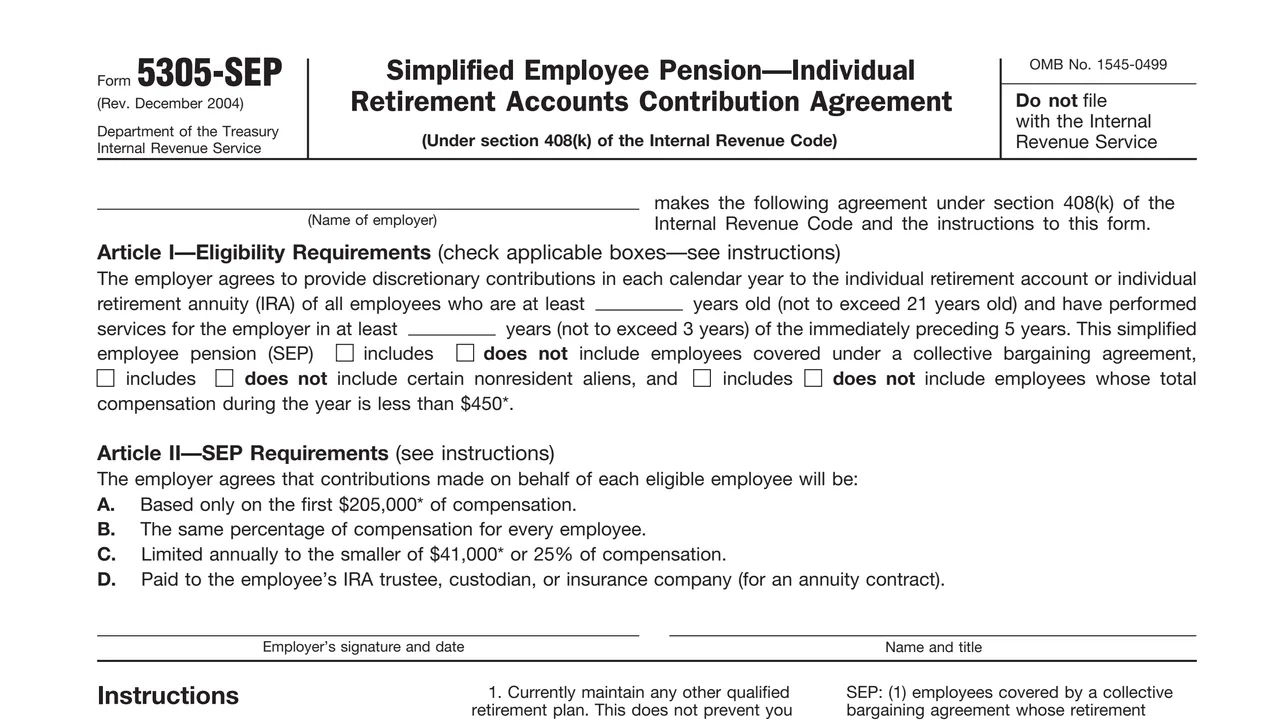
The opening line where the employer's name goes before the words "makes the following agreement under section 408(k)."
Blanks for the minimum age (not to exceed 21) and years of service (not to exceed 3 of the preceding 5), and boxes for three groups of employees.
Four items, A to D, on the compensation used, the same percentage for every employee, the annual limit, and payment to the employee's IRA trustee, custodian or insurance company.
The employer's signature and date, and the signer's name and title.
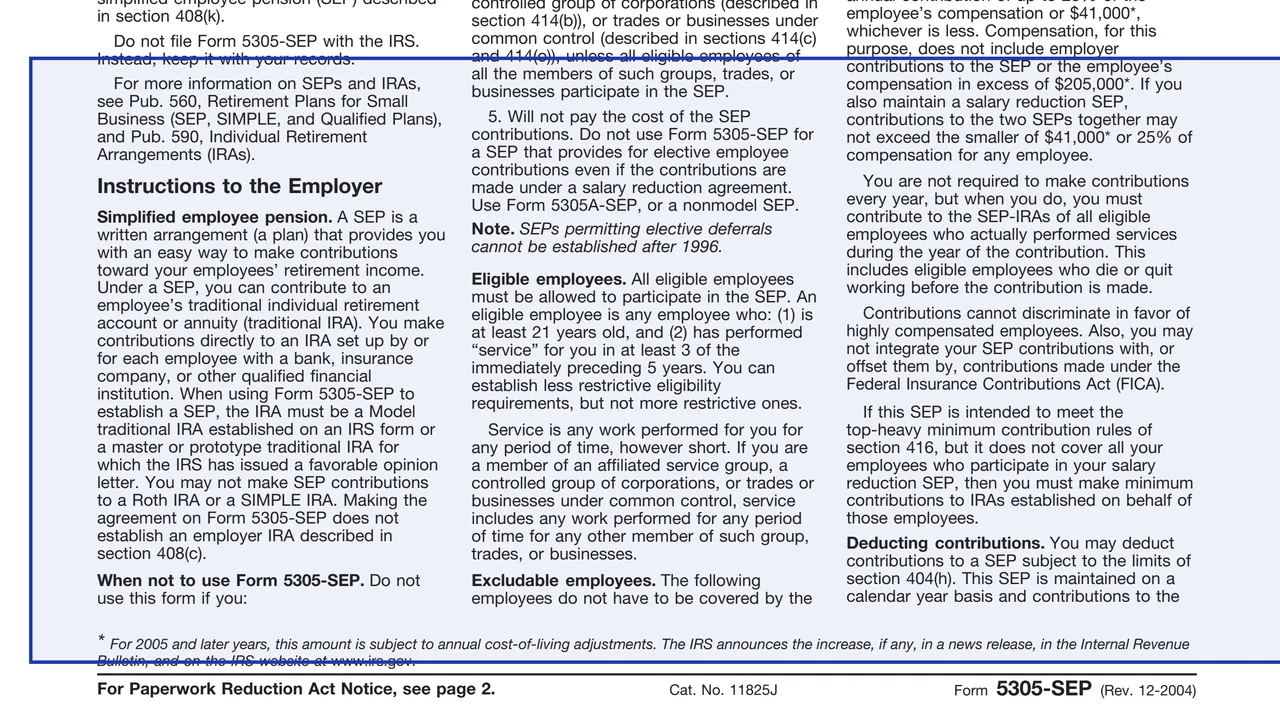
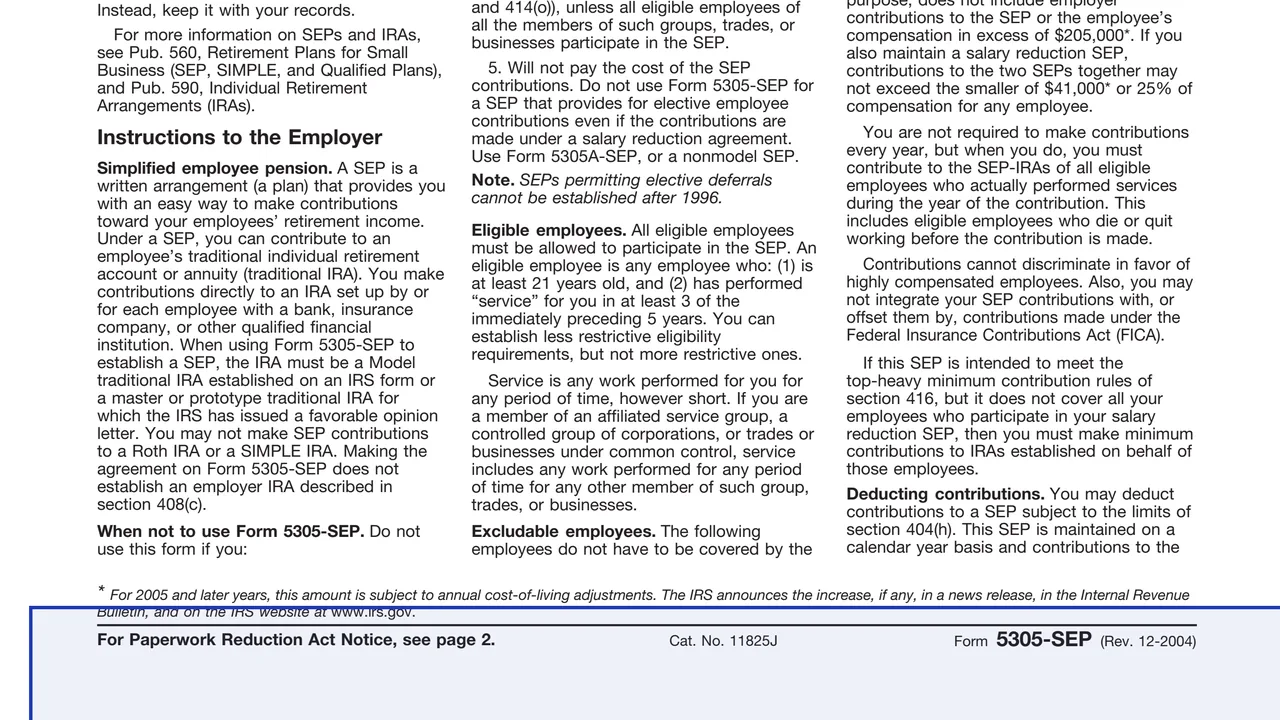
Who may not use the form, eligible and excludable employees, contribution limits, deducting contributions and completing the agreement.
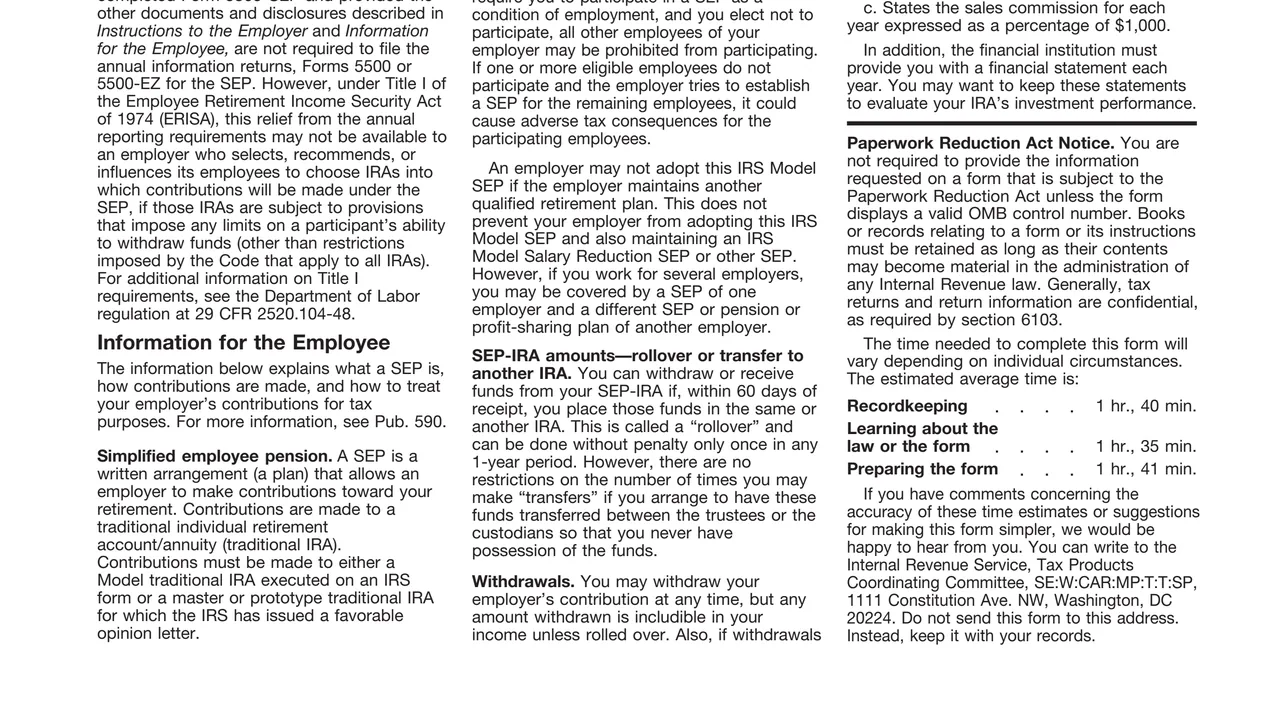
What a SEP is, contribution limits, tax treatment, rollovers and transfers, withdrawals, excess contributions and financial institution requirements.
Enter the name of the employer on the opening line.
Enter the minimum age and the years of service. The instructions say the employer can set less restrictive eligibility requirements than age 21 and 3 of the preceding 5 years, but not more restrictive ones.
Check includes or does not include for employees under a collective bargaining agreement, certain nonresident aliens, and employees paid less than $450* during the year.
Review requirements A to D. They have no blanks and apply to contributions for each eligible employee.
Sign and date, and enter the signer's name and title on the line below Article II.
The instructions say the agreement is adopted when IRAs exist for all eligible employees, all blanks are filled, and each eligible employee has a copy of the form and the statements the instructions list.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Nowhere. The form says "Do not file Form 5305-SEP with the IRS. Instead, keep it with your records."
The instructions say employers that set up a SEP with this form and give employees the copies and disclosures described are not required to file Forms 5500 or 5500-EZ for the SEP, with an ERISA Title I exception.
The instructions say contributions for a particular tax year are made by the due date of the employer's income tax return (including extensions) for that tax year.
This revision prints the smaller of $41,000* or 25% of compensation, using compensation up to $205,000*. The asterisk note says these amounts are subject to annual cost-of-living adjustments for 2005 and later years.
The instructions say the administrator gives each participant written notice of employer contributions by the later of January 31 of the following year or 30 days after the contribution.
The instructions say each participant gets a copy of any amendment and a written explanation of its effects within 30 days of the amendment's effective date.
5305A-SEP
221 fields, 8 pages
5500-EZ
78 fields, 2 pages
W-2
568 fields, 11 pages
5305-SIMPLE
32 fields, 6 pages
5304-SIMPLE
32 fields, 6 pages
5498
83 fields, 4 pages
The employer completes and signs the agreement. Eligible employees and the financial institutions that hold their IRAs receive information under it.
No tool matches that search.
No. The form says "Do not file Form 5305-SEP with the IRS. Instead, keep it with your records."
The employer. The form has one line for the employer's signature and date, plus the signer's name and title.
The instructions say not to use the form if the employer currently maintains any other qualified retirement plan. That does not prevent maintaining another SEP.
No. The instructions say not to use it for a SEP that provides for elective employee contributions, and to use Form 5305A-SEP or a nonmodel SEP instead.
The instructions say the employer is not required to make contributions every year, but contributions that are made go to the SEP-IRAs of all eligible employees who performed services that year.
The December 2004 revision prints $41,000*, $205,000* and $450*. Its note says these are subject to annual cost-of-living adjustments, announced in a news release, the Internal Revenue Bulletin and on www.irs.gov.
The form says employer contributions within the limits will not be included on the employee's Form W-2.