Name, number and address
Name(s) and identifying number as shown on the tax return, then the street address, city, state and ZIP code.
5213
Election to Postpone Determination as To Whether the Presumption Applies That an Activity is Engaged in for Profit
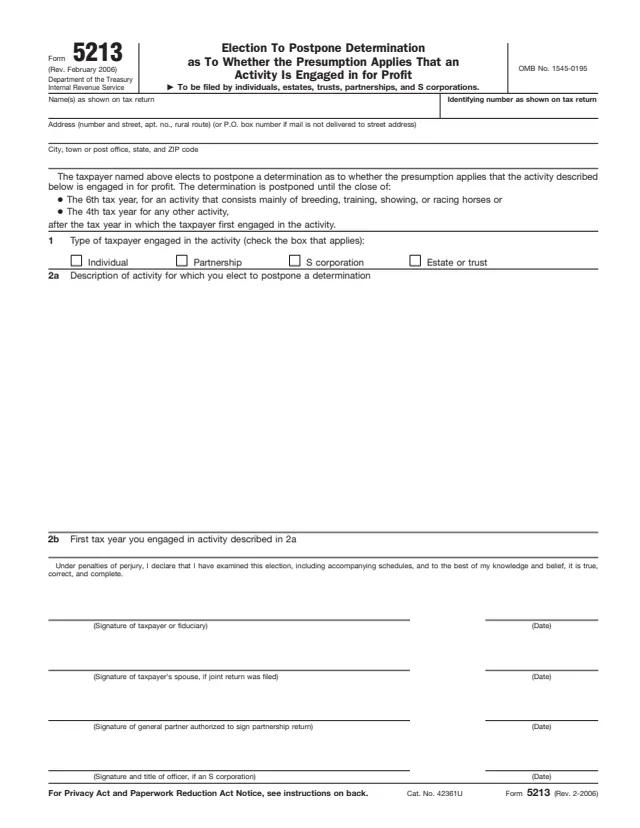
Form 5213 is the Election To Postpone Determination as To Whether the Presumption Applies That an Activity Is Engaged in for Profit. The form says it is to be filed by individuals, estates, trusts, partnerships and S corporations.
The instructions on page 2 explain that if an activity is not engaged in for profit, some deductions may not be allowed. An activity is presumed to be engaged in for profit if its gross income exceeds its deductions for 3 or more of the tax years in a period of 5 consecutive tax years, or for 2 or more of 7 consecutive tax years for an activity that consists mainly of breeding, training, showing or racing horses. That period of 5 (or 7) tax years is called the presumption period.
The form says that with a timely election the IRS will generally postpone its determination until after the end of the 4th tax year (6th for horses) after the year the activity began. Filing also extends the period of limitations for tax on the activity. You can fill out Form 5213 free in your browser on this page and download it without an account.
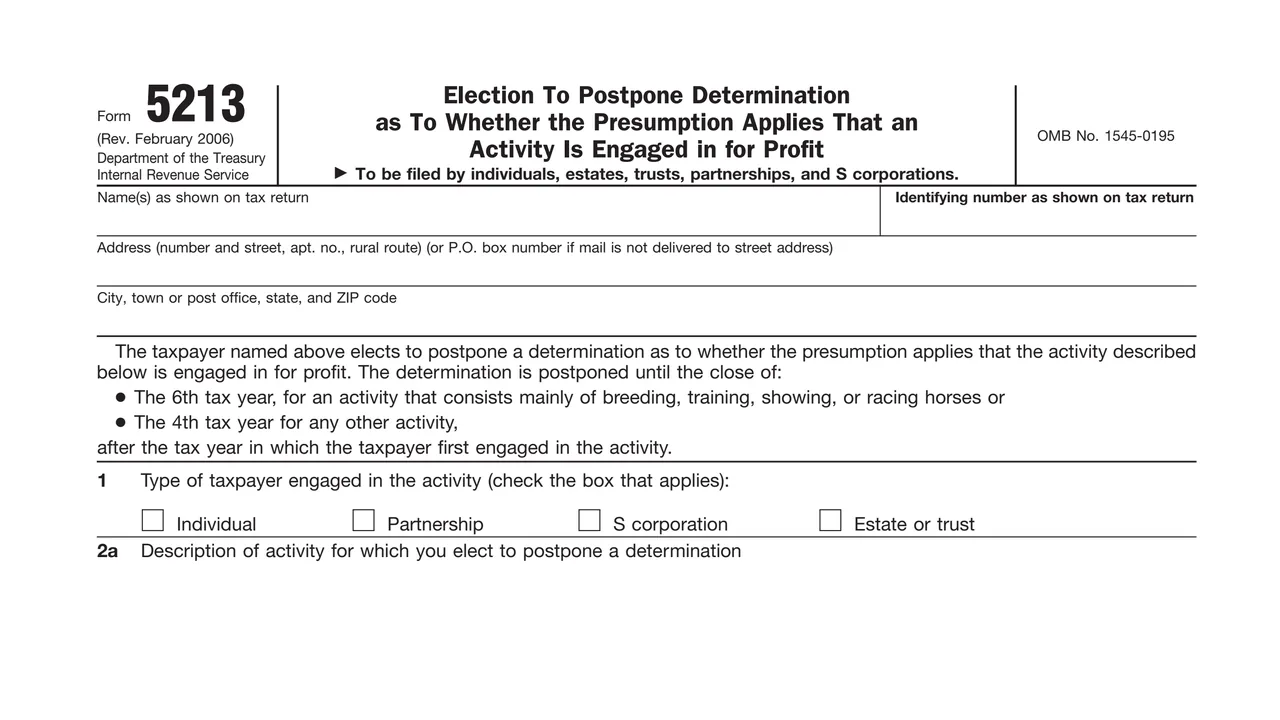
Name(s) and identifying number as shown on the tax return, then the street address, city, state and ZIP code.
The taxpayer elects to postpone the determination until the close of the 6th tax year for a horse activity, or the 4th tax year for any other activity, after the first year in the activity.
Four boxes: individual, partnership, S corporation, and estate or trust.
A description of the activity, and the first tax year you engaged in it.
Lines for the taxpayer or fiduciary, the spouse on a joint return, a general partner, or an S corporation officer and title, each with a date.
Enter them as shown on your tax return for the first tax year you engaged in the activity. Individuals use an SSN, others an EIN. On a joint return, enter both names and the SSN shown first.
Check the one box for the type of taxpayer engaged in the activity.
Describe the activity in detail. The form says to file a separate Form 5213 for each activity, or one form for several activities that have the same presumption period.
Enter the first tax year you engaged in the activity described on line 2a.
Sign and date on the line or lines that apply, and keep a copy for your records.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to file within 3 years after the due date of your return (determined without extensions) for the first tax year in which you engaged in the activity.
If you received a written notice that the IRS proposes to disallow deductions for an activity not engaged in for profit (section 183), the form says to file within 60 days after receiving it. That does not extend the 3-year period.
With the Internal Revenue Service Center where you file your return, and not with any other return. After a notice, file with the IRS office that sent it.
The form says filing generally extends the period for assessing tax attributable to the activity until 2 years after the due date (without extensions) for the last tax year in the presumption period.
The form says the extension of the period of limitations also applies to partners or shareholders in the activity.

1040
199 fields, 2 pages
1040
105 fields, 2 pages
1040
89 fields, 2 pages
1041
173 fields, 3 pages
1065
440 fields, 6 pages
1120-S
390 fields, 5 pages
The form says it is to be filed by individuals, estates, trusts, partnerships and S corporations that want to postpone the IRS determination.
No tool matches that search.
It elects to postpone an IRS determination as to whether the presumption applies that an activity is engaged in for profit, until the end of the presumption period.
The form says within 3 years after the due date of your return (determined without extensions) for the first tax year in the activity, or within 60 days after an IRS notice proposing to disallow deductions under section 183.
The form says to file it with the Internal Revenue Service Center where you file your return, not with any other return, because that will delay processing. After a notice, send it to the IRS office that sent the notice.
Generally a separate Form 5213 is filed for each activity. The form says one form may cover several activities if all have the same presumption period, with each described in detail.
Yes. The form says filing generally extends the period of limitations for assessing income tax attributable to the activity during the presumption period.
The form says it may not be used by someone engaged in a horse activity for more than 7 years, or in any other activity for more than 5 years.