Name, address and SSN
Your name and SSN, your spouse's for a joint return, your home address, and fields for a foreign country, province or county and postal code.
2350
Application for Extension of Time To File U.S. Income Tax Return
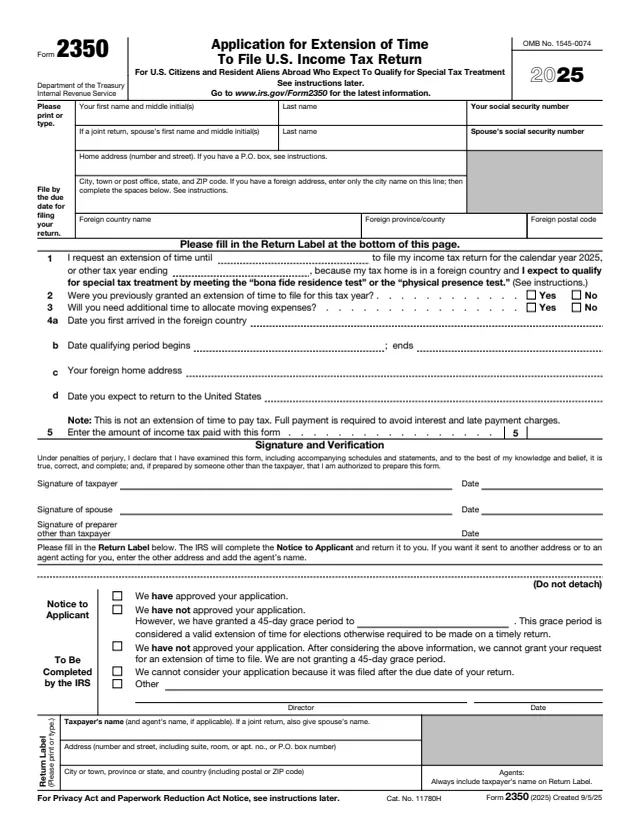
Form 2350 is the application U.S. citizens and resident aliens abroad use to ask for more time to file their income tax return when they expect to qualify for special tax treatment. The instructions say to use it only if you expect to file Form 2555 and need the time to meet either the bona fide residence test or the physical presence test to qualify for the foreign earned income exclusion and/or the foreign housing exclusion or deduction. All other taxpayers file Form 4868 to request an extension, the instructions say.
If an extension is given, it will generally run to a date 30 days after the date you expect to meet either test. Form 2350 does not extend the time to pay taxes. For a 2025 calendar year return, the instructions give April 15, 2026, as the filing date, or June 15, 2026, if you have 2 extra months because you were out of the country.
You can fill out Form 2350 free in your browser on this page and download the result without an account.
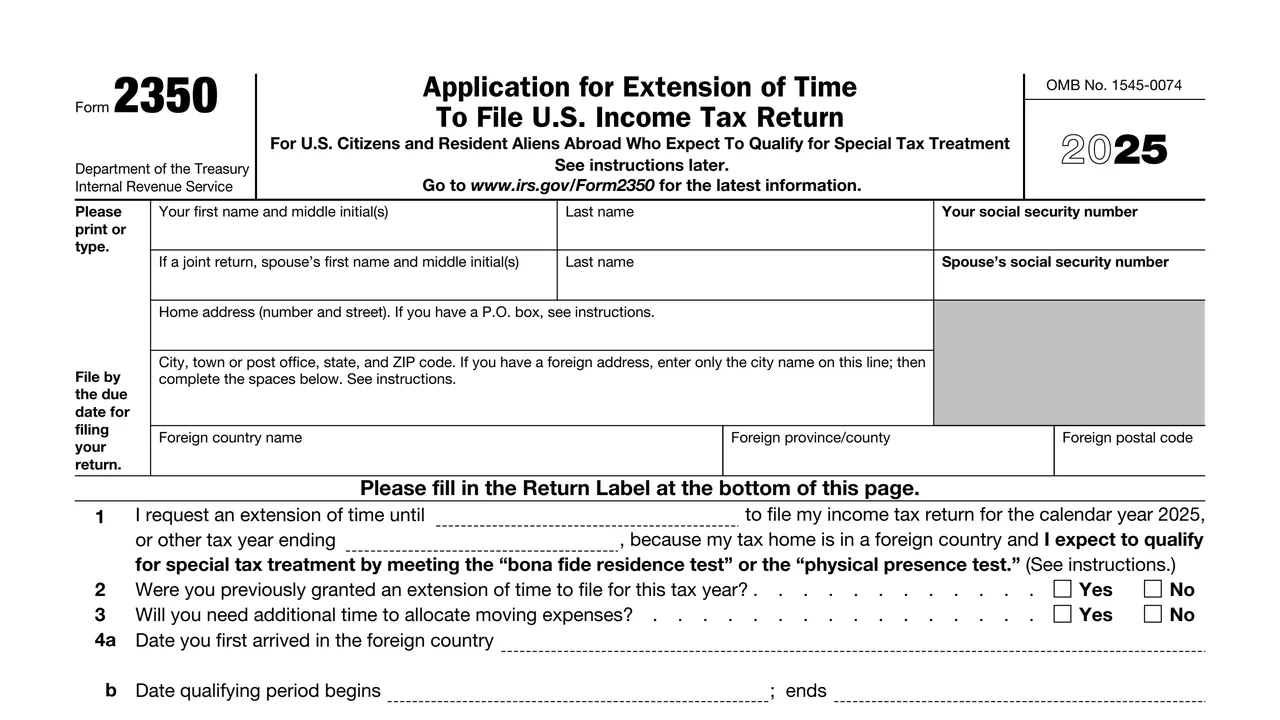
Your name and SSN, your spouse's for a joint return, your home address, and fields for a foreign country, province or county and postal code.
The date you ask for, with the statement that your tax home is in a foreign country and you expect to meet the bona fide residence or physical presence test.
Whether you were already granted an extension for this tax year, and whether you need more time to allocate moving expenses.
The date you first arrived in the foreign country, the start and end of the qualifying period, your foreign home address and the date you expect to return to the United States.
Income tax paid with the form, then signatures of the taxpayer, the spouse and any preparer other than the taxpayer.
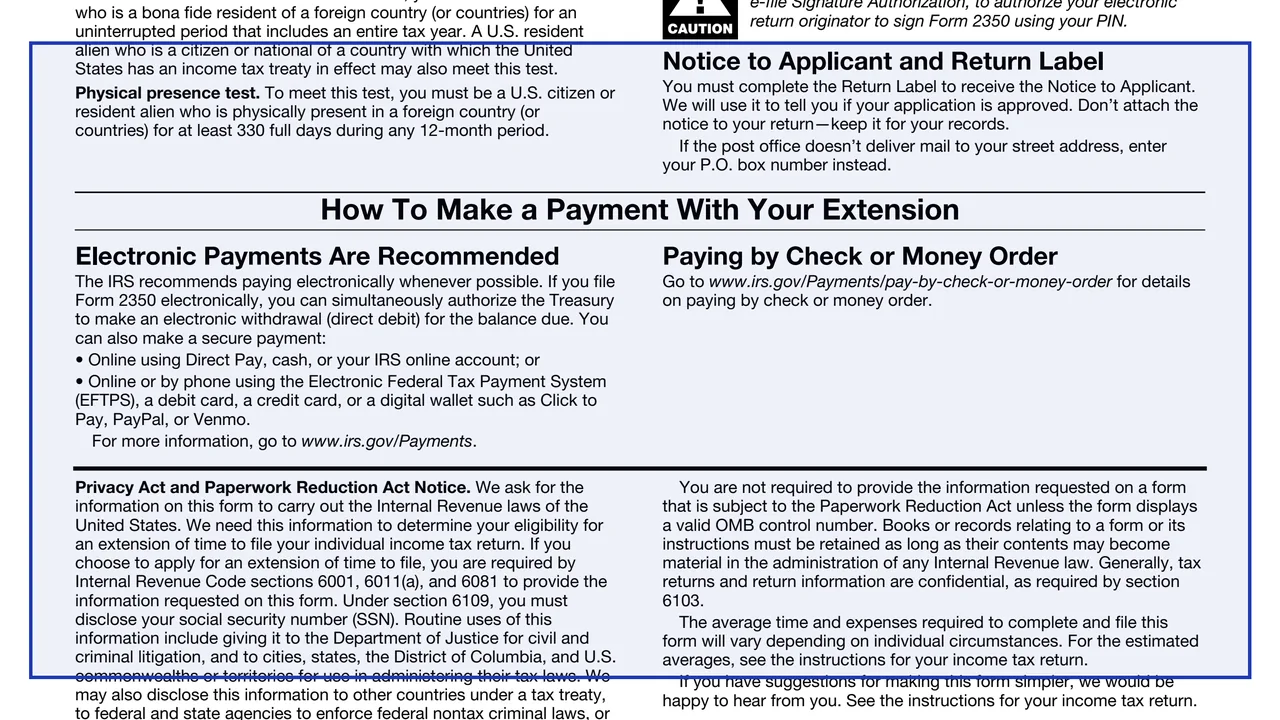
The IRS completes the notice to show whether the application is approved and mails it to the name and address on the Return Label.
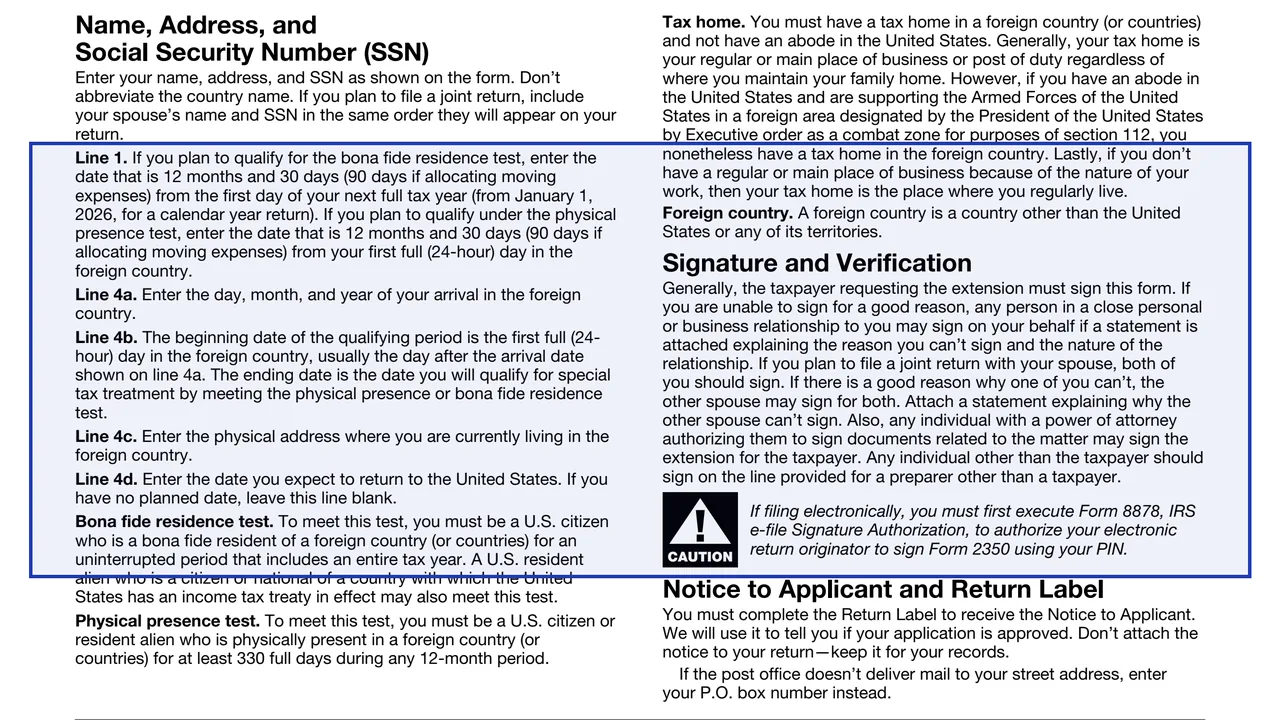
Enter names, SSNs and address as shown on the form. Do not abbreviate the country name. For a joint return, list your spouse in the same order as on the return.
For the bona fide residence test, enter the date 12 months and 30 days (90 days if allocating moving expenses) from the first day of your next full tax year. For the physical presence test, count from your first full (24-hour) day in the foreign country.
Enter your arrival date, the first full day abroad as the start of the qualifying period and the date you expect to meet the test as its end, your current foreign address, and your planned return date. Leave 4d blank if you have none.
Enter any income tax paid with the form. When you later file Form 1040 or 1040-SR, the payment goes on Schedule 3 (Form 1040), line 10.
Generally the taxpayer requesting the extension signs. A person holding a power of attorney, or another signer with an attached statement, signs on the preparer line.
Fill in the Return Label so the IRS can send the Notice to Applicant. The instructions say to keep the notice for your records and not attach it to your return.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
On or before the due date of Form 1040 or 1040-SR: April 15, 2026, for a 2025 calendar year return, or June 15, 2026, with 2 extra months for being out of the country. The instructions say to file early enough to still file on time if it is not approved.
The IRS recommends electronic filing and sends an electronic acknowledgment. Do not also send a paper Form 2350. The instructions say fiscal year taxpayers file a paper Form 2350.
Department of the Treasury, Internal Revenue Service, Austin, TX 73301-0045. A paper form can also be given to a local IRS representative or other IRS employee.
Form 2350 does not extend the time to pay. Interest runs on tax not paid by the regular due date. Options listed include Direct Pay, EFTPS, debit or credit card, digital wallet, or check or money order.
The late payment penalty is usually ½ of 1% per month, up to 25%. The late filing penalty is usually 5% per month, generally up to 25%. If more than 60 days late, the minimum is $525 or the tax due, whichever is smaller.
An extension to file the 2025 calendar year income tax return also extends the time to file Form 709 for 2025, but not the time to pay gift and GST tax. Form 8892 covers that payment.
2555
160 fields, 3 pages
4868
17 fields, 4 pages

1040
199 fields, 2 pages
8878
19 fields, 2 pages
709
1,851 fields, 10 pages
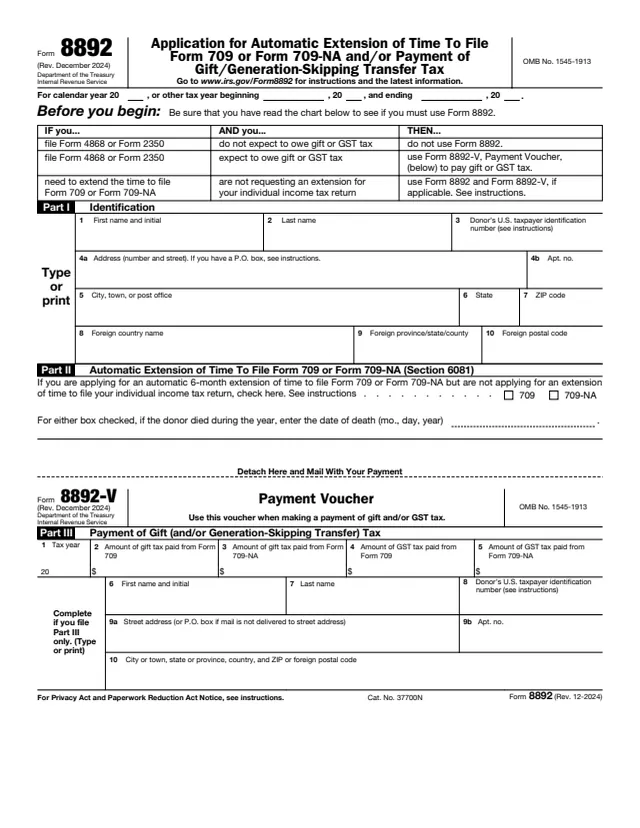
8892
30 fields, 1 page
The instructions say to file it if all three apply: you are a U.S. citizen or resident alien; you expect to qualify for the exclusions by meeting either test, but not until after your return is due; and your tax home is in a foreign country throughout the qualifying period.
No tool matches that search.
The instructions say Form 2350 is only for those who expect to file Form 2555 and need time to meet the bona fide residence or physical presence test. All other taxpayers file Form 4868.
Generally to a date 30 days after the date you expect to meet either test. With moving expenses to allocate, it may run up to 90 days after the end of the year following the year you moved.
No. The form says it is not an extension of time to pay tax. Interest is owed on tax not paid by the regular due date, and penalties may apply.
Yes. The IRS recommends it. Fiscal year taxpayers file on paper. If an electronic return originator signs with your PIN, Form 8878 is executed first.
The IRS completes the Notice to Applicant and mails it to the Return Label address. It can approve, deny, or deny with a 45-day grace period that the form says counts as a valid extension for elections.
The instructions say not to file it more than once for each move overseas. If you stay abroad in later tax years after qualifying and need more time, they point to Form 4868.
The bona fide residence test covers a U.S. citizen who is a bona fide resident of a foreign country for an uninterrupted period that includes an entire tax year. The physical presence test covers at least 330 full days abroad in any 12-month period.