Box 1: the taxpayer
Name, taxpayer identification number (TIN) and address of the person making the election.
15620
Section 83(b) Election
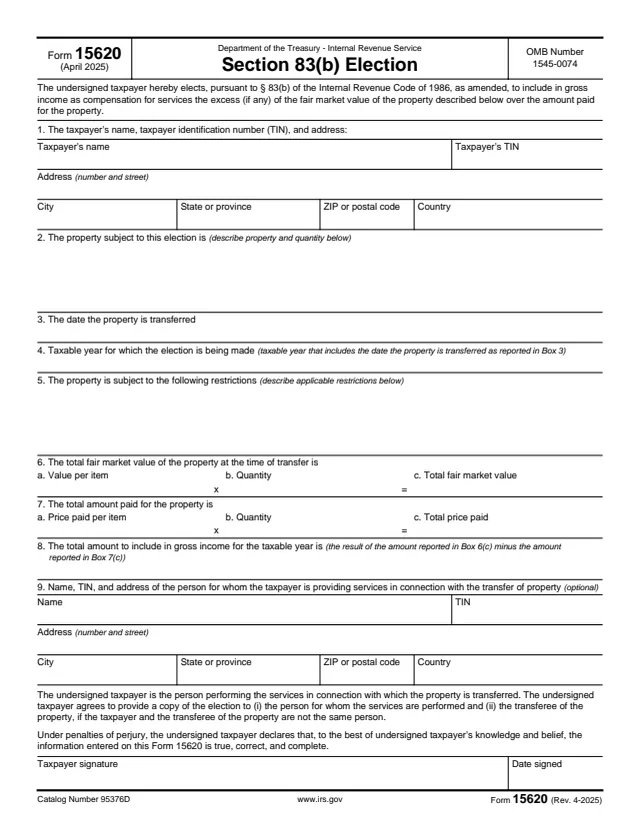
Form 15620, Section 83(b) Election, is an IRS form for making the election under section 83(b) of the Internal Revenue Code. The instructions say that when substantially nonvested property is transferred in connection with the performance of services, the person who performs the services may elect to include in gross income now the excess (if any) of the property's fair market value at the time of transfer over the amount (if any) paid for it, rather than when the property later becomes substantially vested.
The form has nine boxes: who is making the election, the property, the transfer date, the taxable year, the restrictions, the fair market value, the amount paid, the amount to include in gross income and, optionally, the service recipient. The Privacy Act notice says Form 15620 is provided by the IRS for convenience and its use is voluntary. The instructions say a written statement that satisfies Treas. Reg. § 1.83-2 is the alternative.
The instructions are on pages 2 and 3 of the same PDF. You can fill out Form 15620 free in your browser on this page and download it without an account.
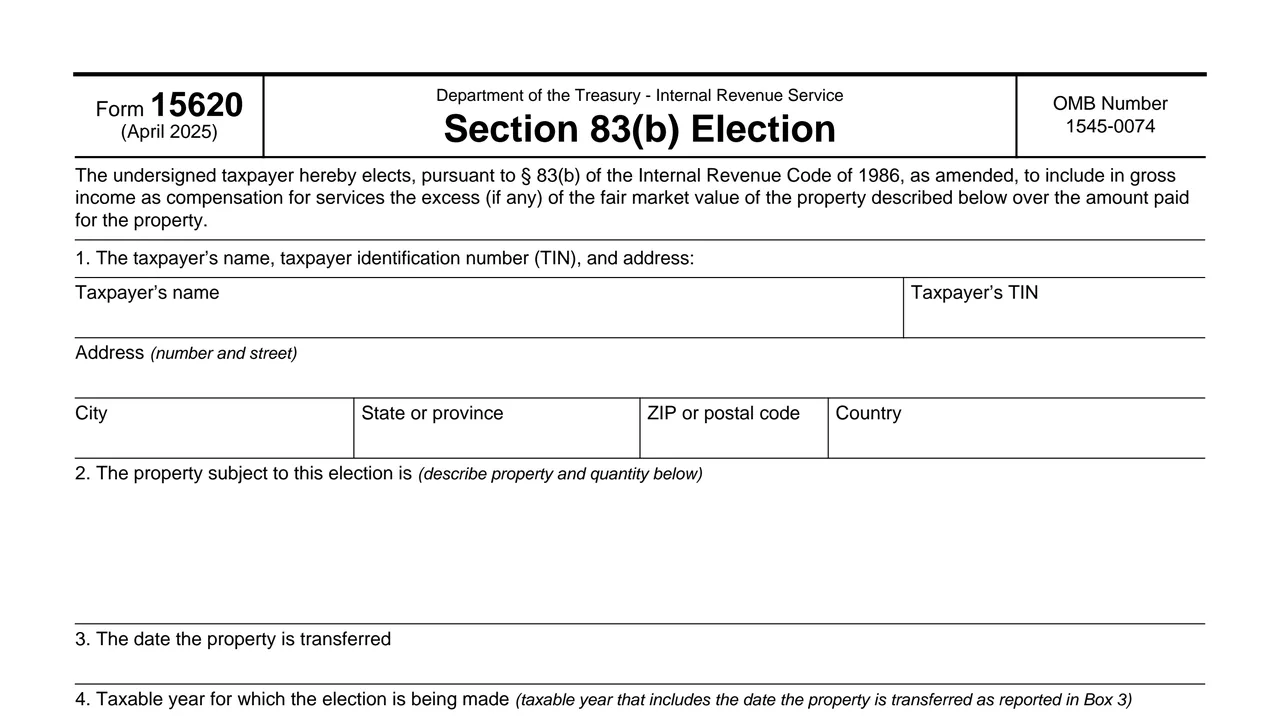
Name, taxpayer identification number (TIN) and address of the person making the election.
A description and quantity of the property, and the date it is transferred.
The taxable year that includes the transfer date, and a description of the restrictions on the property.
Fair market value per item times quantity, and price paid per item times quantity, each with a total.
Box 6(c) minus Box 7(c), the total amount to include in gross income for the taxable year.
Optional name, TIN and address of the service recipient, then the copy agreement, the penalties of perjury declaration, the signature and the date signed.
Enter the name, TIN and address of the person making the 83(b) election.
Describe the property and quantity, such as the instructions' example "1,000 shares of Class A common stock of Corporation B," and enter the transfer date.
Enter the taxable year that includes the transfer date, for example "calendar year 2025" or "fiscal year ending May 31, 2025," as the instructions show.
Describe the restrictions on the substantially nonvested property, such as forfeiture terms in a restricted stock agreement, as in the instructions' example.
Multiply value per item by quantity for 6(c) and price paid per item by quantity for 7(c), then enter 6(c) minus 7(c) in Box 8. The instructions say fair market value is determined without regard to any lapse restriction.
Box 9 is optional and, the instructions say, not required to make a valid election. Sign and date the form.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say an 83(b) election must be filed no later than 30 days after the date the property was transferred. If the thirtieth day falls on a Saturday, Sunday or legal holiday, a postmark by the next day that is not one of those counts as timely under IRC § 7503.
The instructions say to submit the completed and signed form to the IRS by mail, to the IRS office with which the person who performs the services files a federal income tax return.
A copy goes to the person for whom the services are performed, and another to the transferee of the property if that is a different person, the instructions say.
The instructions say an 83(b) election may not be revoked except with the consent of the IRS, and point to Treas. Reg. § 1.83-2(f) and Revenue Procedure 2006-31.
The instructions say the election may also be made by filing a written statement that satisfies the requirements of Treas. Reg. § 1.83-2.
The instructions refer to the Restricted Property section of Publication 525 for a description of the tax consequences.

1040
199 fields, 2 pages
3921
43 fields, 4 pages
3922
33 fields, 3 pages
W-2
568 fields, 11 pages
1099-NEC
140 fields, 6 pages
The instructions say the person who performs the services makes the election, for example an employee or an independent contractor.
No tool matches that search.
The instructions say no later than 30 days after the date the property was transferred, with a Saturday, Sunday or legal holiday rule under IRC § 7503.
No. The instructions say the election may also be made with a written statement that satisfies Treas. Reg. § 1.83-2, and the Privacy Act notice says use of the form is voluntary.
The instructions say a copy goes to the person for whom the services are performed, and to the transferee of the property if that is a different person.
The instructions say only with the consent of the IRS.
No. The instructions say Box 9 is optional and not required to make a valid 83(b) election.
The instructions say to subtract the total price paid in Box 7(c) from the total fair market value in Box 6(c).