Header
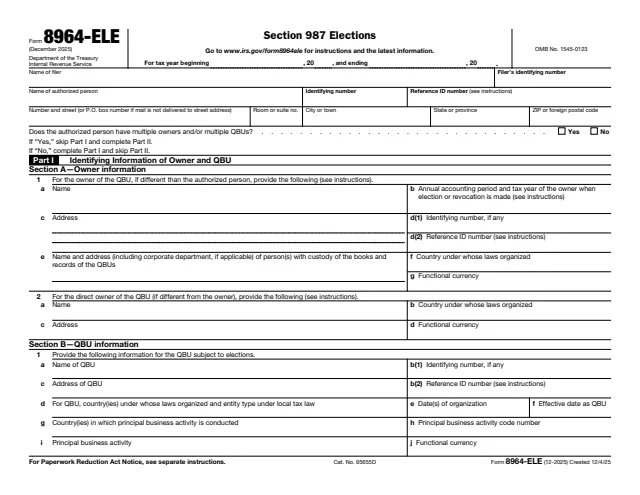
The tax year, the filer's name and identifying number, the authorized person's name, identifying number and reference ID number, the address, and a Yes or No question on multiple owners or QBUs.
8964-ELE
Section 987 Elections
Form 8964-ELE is used to make or revoke elections under the section 987 regulations. The About page says it satisfies the reporting requirements of Regulations section 1.987-1(g).
Section 987 applies, the instructions say, to any taxpayer that has a qualified business unit (QBU) with a functional currency other than the dollar. Final regulations were issued on December 11, 2024 (TD 10016). The December 2025 form identifies the QBU owner and each section 987 QBU, then lists ten elections in Part III, such as the current rate election, the annual recognition election and the section 988 mark-to-market election.
The form is filed by the authorized person for the QBU owner, for example a U.S. corporation, a partnership or the controlling domestic shareholders of a controlled foreign corporation. You can fill it out free in your browser on this page and download the result without an account.
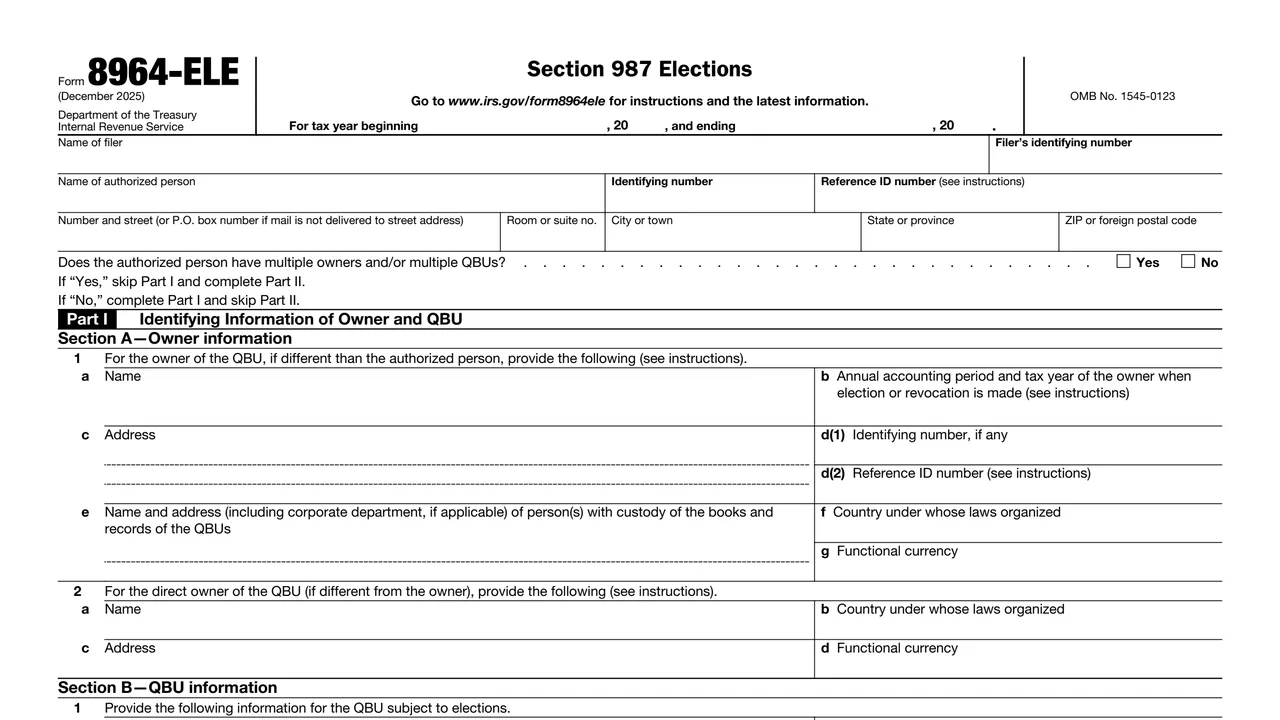
The tax year, the filer's name and identifying number, the authorized person's name, identifying number and reference ID number, the address, and a Yes or No question on multiple owners or QBUs.
Section A gives the QBU owner and direct owner, with country and functional currency. Section B gives the QBU's name, country, entity type, effective date, business activity, functional currency and U.S. office.
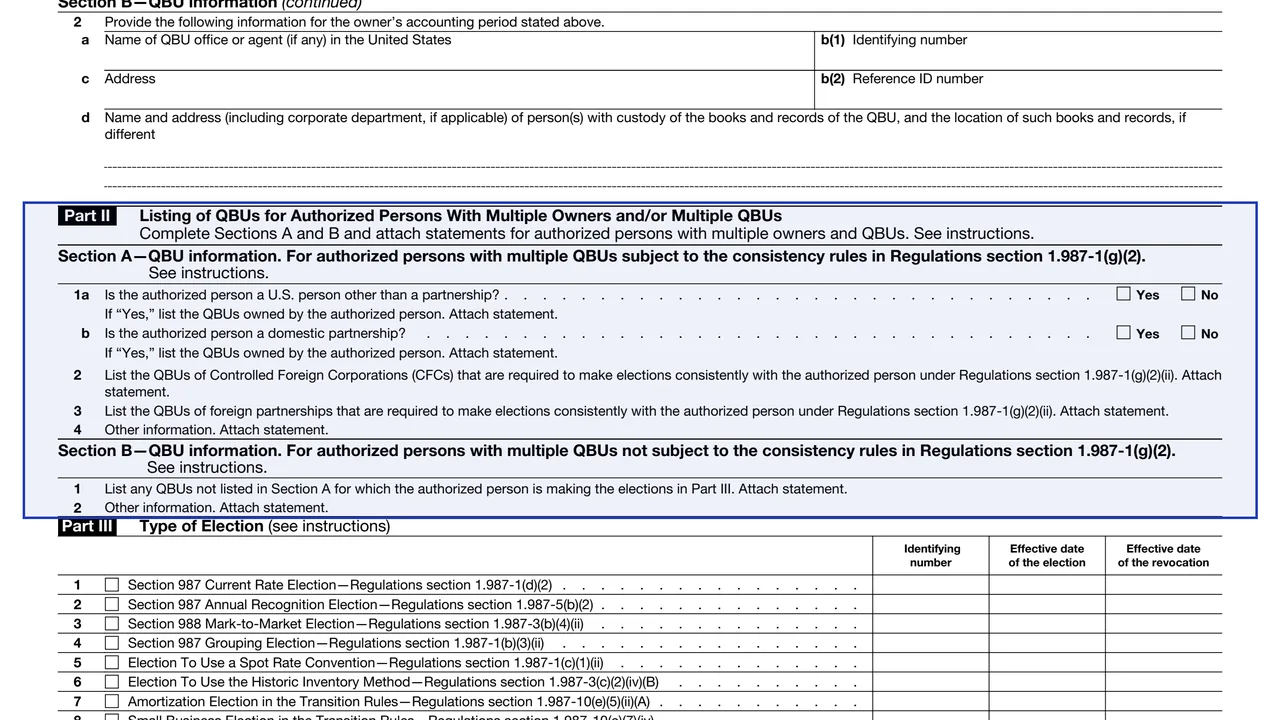
Section A lists QBUs subject to the consistency rules, including QBUs of CFCs and foreign partnerships. Section B lists other QBUs. Each line asks for an attached statement.
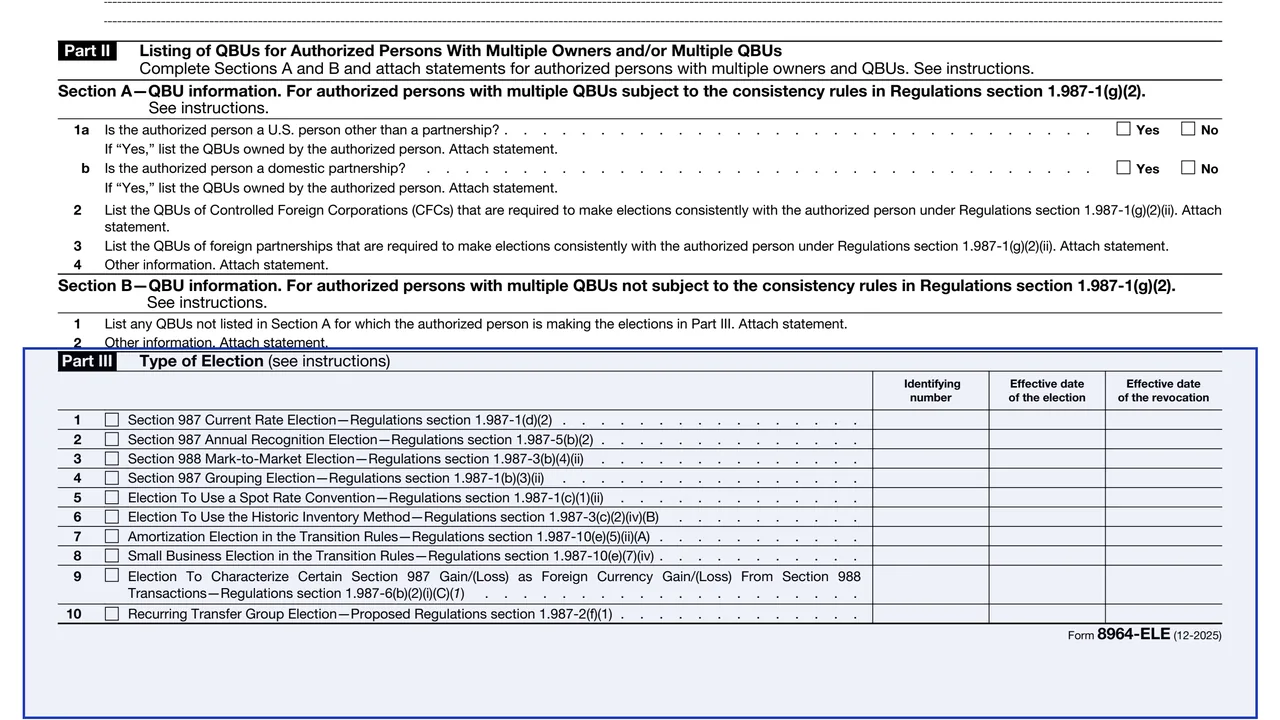
Ten election lines, from the current rate election (line 1) to the recurring transfer group election (line 10), each with an identifying number and effective dates of the election and any revocation.
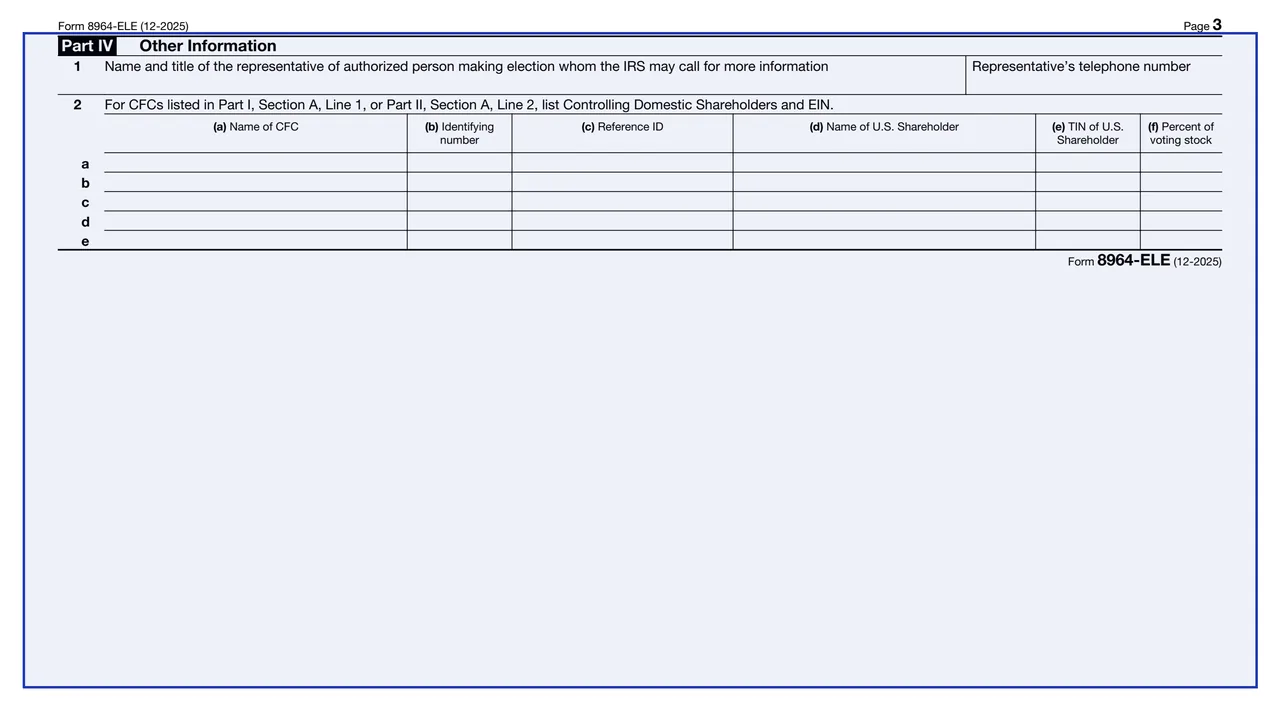
Line 1 names the representative the IRS may call, with a telephone number. Line 2 lists each CFC's controlling domestic shareholders, their TINs and percent of voting stock.
Enter the accounting period, then the filer's name and EIN or reference ID number. The instructions say a reference ID is alphanumeric, up to 50 characters, and needs no IRS application.
Check Yes for multiple owners or multiple QBUs and complete only Part II. Otherwise check No and complete only Part I.
Use two-letter country codes, the six-digit business activity code from the Form 1120 instructions, and the three-character ISO 4217 code for each functional currency. Write "branch" if the QBU is not a legal entity.
Check each election being made or revoked, and any earlier election still in effect. Give the EIN of the authorized person and the effective dates. For a spot rate convention, attach a statement.
Name a representative with power of attorney, such as on Form 2848. When space runs out, the instructions say to fill every space first and attach the rest, not to write "See attached".
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say the authorized person attaches Form 8964-ELE to its original, timely filed (including extensions) return for the tax year the elections are made.
In later years, a current rate, annual recognition or section 988 mark-to-market election is filed before the start of the tax year by e-Fax to 833-312-2650, with a copy on the timely filed return.
The instructions say other elections can be made or revoked in later years only with the Commissioner's consent through a private letter ruling, with a copy attached to the return.
The instructions say a current rate, annual recognition or section 988 mark-to-market election may not be revoked without consent for any year beginning within 60 months of the year it was made.
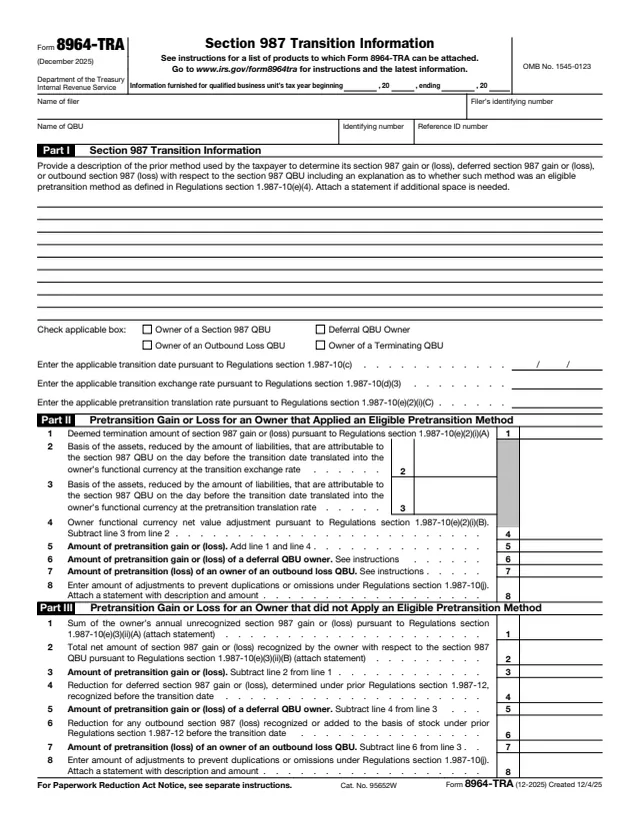
QBU owners compute pretransition gain or loss on Form 8964-TRA. Owners of foreign branches or disregarded entities may also file Form 8858.
A corrected Form 8964-ELE is filed with an amended return, with "Corrected" at the top and a statement identifying the changes.
8964-TRA
35 fields, 1 page
8858
190 fields, 4 pages

5471
437 fields, 6 pages
8865
461 fields, 6 pages

1120
481 fields, 6 pages

1065
440 fields, 6 pages
The instructions say a section 987 election is made or revoked for an owner of a section 987 QBU by the authorized person, and the filer is typically that authorized person.
No tool matches that search.
The instructions say it is used to make or revoke elections under the section 987 regulations and satisfies the reporting requirements of Regulations section 1.987-1(g).
The instructions define it as an eligible qualified business unit with a functional currency different from that of its owner.
The instructions say the controlling domestic shareholders of the CFC are treated as the authorized person. Part IV, line 2 lists their names, TINs and percent of voting stock.
Only for current rate, annual recognition or section 988 mark-to-market elections in later years, filed before the tax year starts. The instructions give the e-Fax number 833-312-2650 and say to file a copy with the timely filed return.
The instructions say a section 987 election is made for an owner and a tax year, applies to every section 987 QBU the owner holds while in effect, and stays in effect until revoked.
File a corrected Form 8964-ELE with an amended return, enter "Corrected" at the top and attach a statement identifying the changes.