Lines 1 and 2: names
Line 1 holds the name of the individual or entity and needs an entry. Line 2 holds a business name or disregarded entity name if different.
W-9
Request for Taxpayer Identification Number and Certification (Spanish Version)
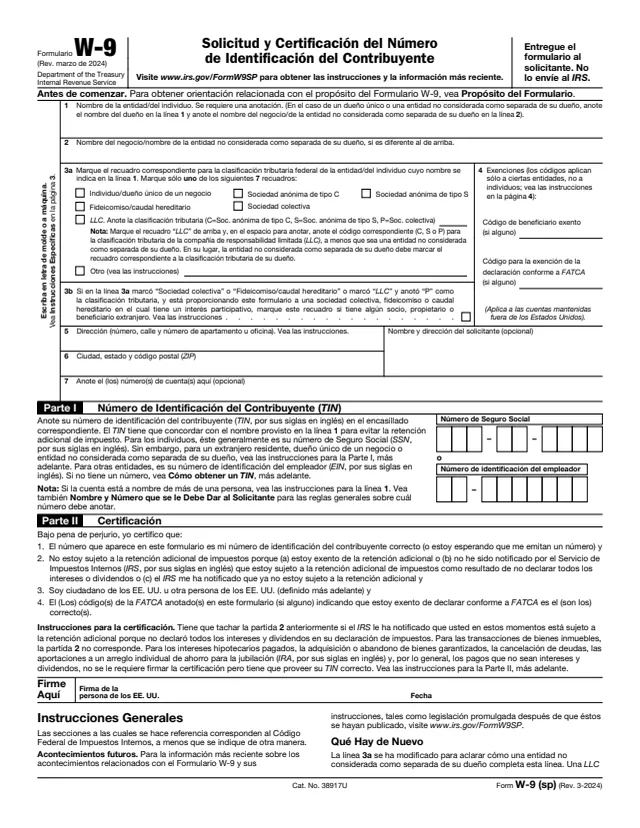
Form W-9 (sp) is the Spanish version of Form W-9, Request for Taxpayer Identification Number and Certification. The PDF is in Spanish under the title "Solicitud y Certificación del Número de Identificación del Contribuyente" and is dated March 2024 ("Rev. marzo de 2024", Rev. 3-2024). The six-page PDF holds the form and its general and specific instructions, all in Spanish.
The form explains that a person or business that has to file an information return with the IRS (the requester) gives you this form to get your correct taxpayer identification number (TIN): an SSN, ITIN, ATIN or EIN. The examples it lists include Forms 1099-INT, 1099-DIV, 1099-MISC, 1099-NEC, 1099-B, 1099-S, 1099-K, 1098, 1098-E, 1098-T, 1099-C and 1099-A. It is only for U.S. persons, including resident aliens.
The top of the form says to give it to the requester and not to send it to the IRS. In a few places the Spanish form asks for English words, such as "NEW" and "Applied For". The English edition, Form W-9, has its own page. You can fill out this Spanish PDF free in your browser on this page and download it without an account.
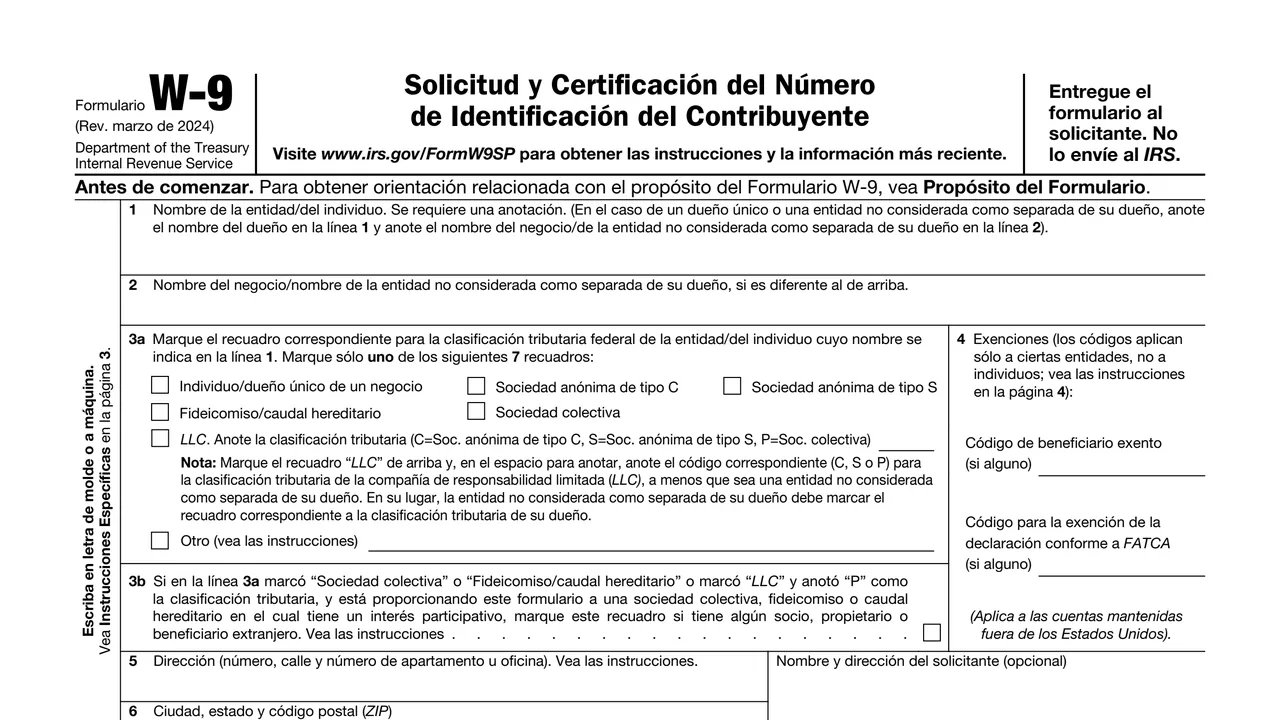
Line 1 holds the name of the individual or entity and needs an entry. Line 2 holds a business name or disregarded entity name if different.
Line 3a has 7 boxes for the federal tax classification, with a C, S or P code for an LLC. Line 3b is for partnerships, trusts and estates with foreign partners, owners or beneficiaries.
Spaces for an exempt payee code and a FATCA exemption code. The form says these codes apply only to certain entities, not individuals.
Your address, your city, state and ZIP code, optional account numbers, and an optional box for the requester's name and address.
Two boxes, one for a Social Security number and one for an employer identification number. The TIN has to match the name on line 1.
Four statements made under penalty of perjury, then the signature of the U.S. person and the date.
Enter the name that matches your tax return and do not leave it blank. If your last name changed without telling the SSA, the form says to enter your first name, the last name on your Social Security card and your new last name.
Check only one box. An LLC that is not disregarded checks the LLC box and enters C, S or P. A disregarded entity checks the box for its owner's classification.
The form says individuals, including sole proprietors, generally are not exempt from backup withholding. If you give the form only because of an account held in the United States, the form says the FATCA code space can stay blank.
Enter your address and your city, state and ZIP code. If the address differs from the one the requester has on file, write "NEW" at the top, as the form says.
Enter the SSN or EIN that matches line 1. A resident alien without an SSN enters an ITIN in the SSN boxes. With no TIN yet, the form says to apply for one and write "Applied For" in the TIN space.
Sign and date. Cross out item 2 if the IRS has told you that you are currently subject to backup withholding for not reporting all interest and dividends.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Give the completed form to the requester. The top of the form says not to send it to the IRS.
The form says that under certain conditions payers withhold 24% of certain payments and pay it to the IRS, for example when no TIN is given or the IRS reports the TIN as incorrect.
For interest, dividend and certain readily tradable instrument payments, the form says you generally have 60 days to get a TIN and give it to the requester. Other payments face backup withholding until you do.
The form lists a $50 penalty for each failure to give a correct TIN, unless due to reasonable cause, and a $500 penalty for a false statement with no reasonable basis that results in no backup withholding.
The form says to give a new Form W-9 if the name or TIN on the account changes, and to update anyone you told you were an exempt payee if that is no longer true.
W-9
23 fields, 6 pages
W-7
68 fields, 1 page
SS-4
89 fields, 2 pages
W-8
23 fields, 1 page
8233
51 fields, 2 pages
1099-NEC
140 fields, 6 pages
The person or entity whose TIN is requested fills it out and gives it to the requester, who keeps it for its information returns. The form says to use it only if you are a U.S. person, which includes a resident alien.
No tool matches that search.
Yes. The IRS lists it as the Spanish version of Form W-9, and the form and its instructions are in Spanish. This page explains it in English.
No. The top of the form says to give it to the requester and not to send it to the IRS.
It says to write "NEW" above a changed address and "Applied For" in the TIN space while a TIN is pending. A requester may also mark the FATCA code line "Not Applicable".
The form says to apply right away: Form SS-5-SP from the SSA for an SSN, Form W-7 for an ITIN, or Form SS-4 for an EIN, which can also be requested online at www.irs.gov/EIN by choosing Español.
The form describes it as withholding 24% of certain payments, such as interest, dividends, rents, royalties and nonemployee pay, and paying it to the IRS.
The form says a sole proprietor with an EIN may enter either the SSN or the EIN, and its name and number table adds that the IRS recommends using the SSN.