Blocks 1 to 10: taxpayer and representative
Taxpayer's name, representative, SSN or EIN, business, home and representative phone numbers, and the taxpayer's street address, city, state and ZIP code.
9423
Collection Appeal Request
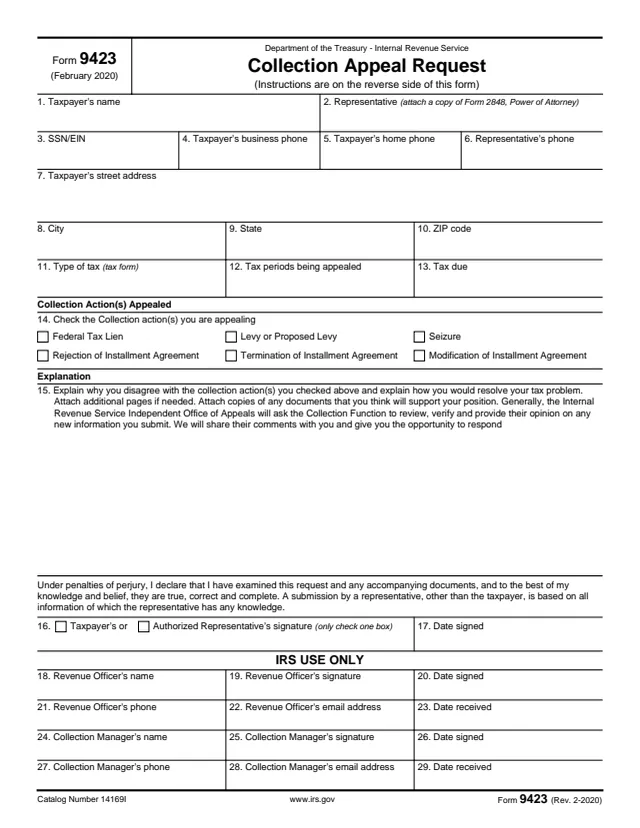
Form 9423 is the request form for the Collection Appeals Program (CAP). The instructions on its back say a taxpayer, or a third party whose property is subject to a collection action, may use it to appeal liens, levies and seizures, denied lien certificates, rejected, modified or terminated installment agreements, and disallowed requests or claims for the return of levied property.
The form asks for the taxpayer and any representative, the type of tax, the periods being appealed and the tax due, the collection actions being appealed, and an explanation of why the taxpayer disagrees and how they would resolve the tax problem. It is signed under penalties of perjury. The bottom block is marked IRS USE ONLY.
The instructions say the form is submitted to the Collection office or revenue officer involved in the action. You can fill out Form 9423 free in your browser on this page and download the result without an account.
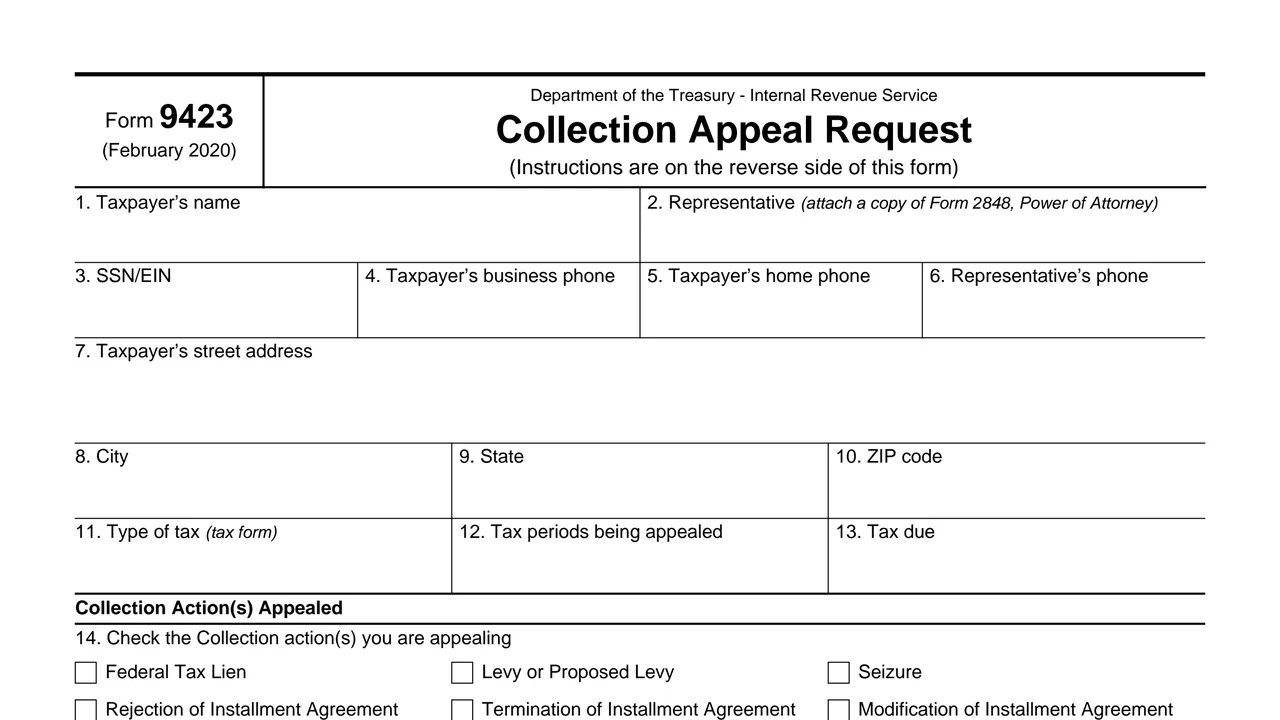
Taxpayer's name, representative, SSN or EIN, business, home and representative phone numbers, and the taxpayer's street address, city, state and ZIP code.
Type of tax (tax form), the tax periods being appealed and the tax due.
Boxes for Federal Tax Lien, Levy or Proposed Levy, Seizure, and Rejection, Termination or Modification of Installment Agreement.
Why the taxpayer disagrees with the checked actions and how they would resolve the tax problem, with additional pages and supporting documents attached if needed.
Signature by the taxpayer or the authorized representative, with only one box checked, under penalties of perjury, and the date signed.
Names, signatures, phone numbers, email addresses and dates for the revenue officer and the collection manager.
For a lien, levy or seizure, the instructions say to first request a conference with the IRS employee's manager. If the disagreement is not resolved, Form 9423 is submitted to request consideration by Appeals.
Enter the taxpayer's name, SSN or EIN, phone numbers and address. If a representative is named in block 2, attach a copy of Form 2848.
Enter the type of tax or tax form, the tax periods being appealed and the tax due.
Check each collection action being appealed.
Explain the disagreement and the proposed solution. If a manager did not make contact within 2 business days of a conference request, the instructions say to note the date of that request here and that no manager made contact.
Check whether the taxpayer or the authorized representative is signing, then sign and date. Submit the form to the Collection office or revenue officer that took the action.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
For a lien, levy or seizure, submit it to the Collection office involved. For an installment agreement, provide it to the office or revenue officer who took the action. The instructions say never to forward that request directly to Appeals.
The instructions say to let the Collection office know within two (2) business days after the manager conference, and that the form must be received or postmarked within three (3) business days of that conference or collection action may resume.
The instructions say an appeal after a seizure goes to the Collection manager within 10 business days after the Notice of Seizure is provided or left at the home or business.
The instructions say to provide the form within 30 calendar days. A managerial conference is not required, though the instructions strongly recommend one whenever possible.
The instructions say the IRS normally stops the collection actions under appeal until the appeal is settled, unless it has reason to believe collection or the amount owed is at risk.
The instructions say the Appeals decision is binding on both the taxpayer and the IRS and cannot get judicial review after a CAP. False information, missing pertinent information or fraud voids the decision.

2848
92 fields, 2 pages
12153
79 fields, 4 pages
12203
31 fields, 2 pages
9465
66 fields, 2 pages
433-D
168 fields, 4 pages
911
57 fields, 4 pages
The instructions say a taxpayer, or a third party whose property is subject to a collection action, may appeal under the Collection Appeals Program. The completed form goes to the IRS Collection office or revenue officer that took the action.
No tool matches that search.
For an installment agreement, the instructions say never to forward the request directly to Appeals. For a lien, levy or seizure, the form goes to the Collection office involved in the action.
For a lien, levy or seizure, the instructions say to first request a conference with the employee's manager. For an installment agreement, a managerial conference is not required but is strongly recommended.
For a lien, levy or seizure, the instructions say within three (3) business days of the manager conference. For an installment agreement, within 30 calendar days.
The instructions say the IRS will normally stop the actions under appeal until it is settled, unless collection or the amount owed is at risk.
Yes. An attorney, certified public accountant or person enrolled to practice before the IRS can represent the taxpayer. For the representative to appear alone, the instructions call for a properly completed Form 2848.
The instructions say there is no judicial review of the Appeals decision after a CAP, though other review may exist, such as a third party filing a wrongful levy action in district court.
The instructions list the Taxpayer Advocate Service at 877-777-4778 for IRS actions creating an economic harm or problems not resolved through normal channels.