Items A to F: building details
Name and identifying number, the building address and building identification number (BIN) from Form 8609, the date placed in service, and tax-exempt bond details when the building is financed with them.
8611
Recapture of Low-Income Housing Credit
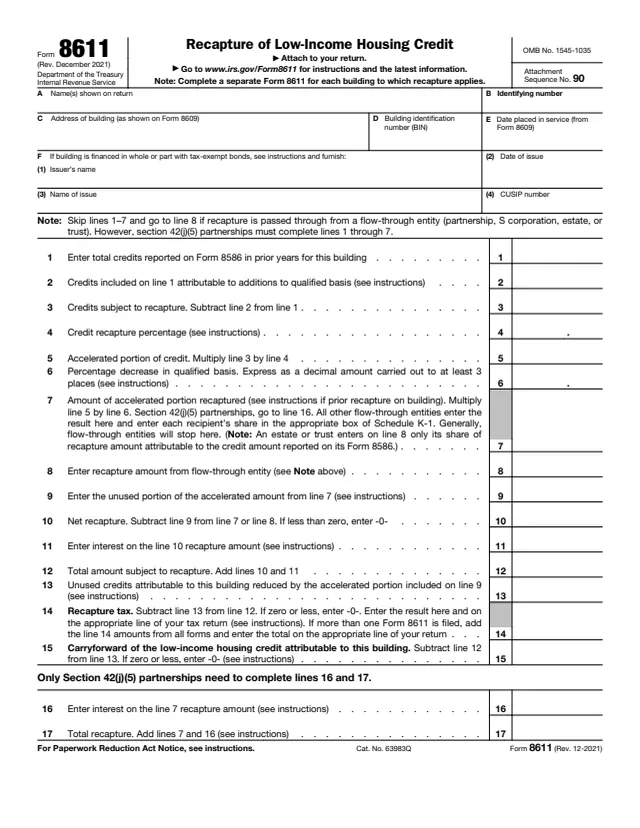
Form 8611, Recapture of Low-Income Housing Credit, figures and reports recapture of part of the low-income housing credit claimed in previous years. The form says it is used when the qualified basis decreased from one year to the next, or a building or an interest in it was disposed of, and the procedures that would have prevented recapture of the credit were not followed.
The form is attached to the filer's tax return, and a separate Form 8611 is completed for each building to which recapture applies. The recapture tax on line 14 goes to the appropriate line of the return, such as Schedule 2 (Form 1040), line 16, or Form 1120, Schedule J, line 9b.
The instructions are printed on pages 2 and 3 of the PDF, with the Line 2 Worksheet and the credit recapture percentage table. You can fill out the PDF free in your browser on this page and download it without an account.
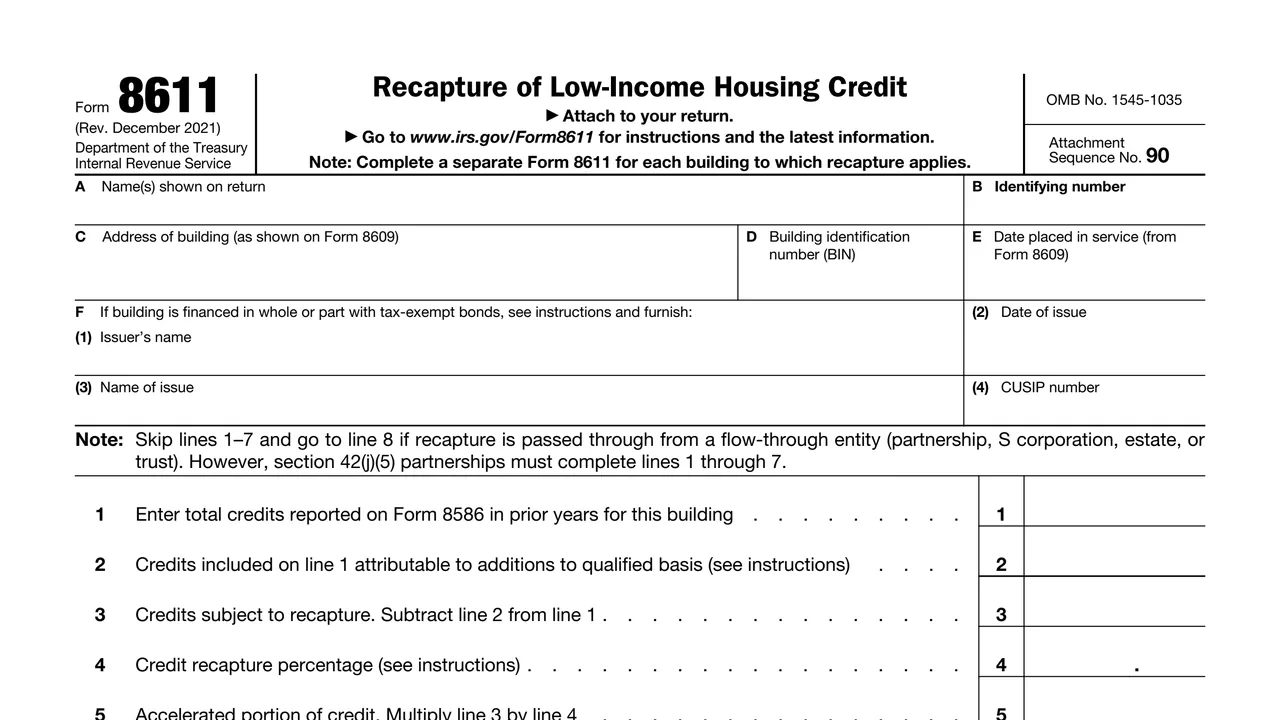
Name and identifying number, the building address and building identification number (BIN) from Form 8609, the date placed in service, and tax-exempt bond details when the building is financed with them.
Total credits reported on Form 8586 in prior years for the building, minus credits attributable to additions to qualified basis.
The credit recapture percentage, the accelerated portion of credit, the percentage decrease in qualified basis, and the amount of the accelerated portion recaptured.
The recapture amount from a flow-through entity, the unused portion of the accelerated amount, net recapture, interest, and the total amount subject to recapture.
Unused credits attributable to the building, the recapture tax that goes to the return, and any carryforward of the credit to the next tax year.
Interest on the line 7 recapture amount and total recapture. The form says only section 42(j)(5) partnerships need to complete these lines.
Enter the names and identifying number shown on the return, and the building address, BIN and placed in service date from Form 8609. For bond financing, the instructions ask for the issuer's name, date of issue, name of the issue and CUSIP number, or None if there is no CUSIP number.
On line 1, enter total credits claimed on the building for all prior years from all Forms 8586, before reduction for the tax liability limit, without credits taken by a previous owner. Figure line 2 with a separate Line 2 Worksheet for each prior year in which line 7 of Form 8609-A was completed.
Enter the credit recapture percentage from the table in the instructions, as a decimal carried to at least 3 places: .333 for years 2 through 11, then .267, .200, .133 and .067 for years 12 to 15.
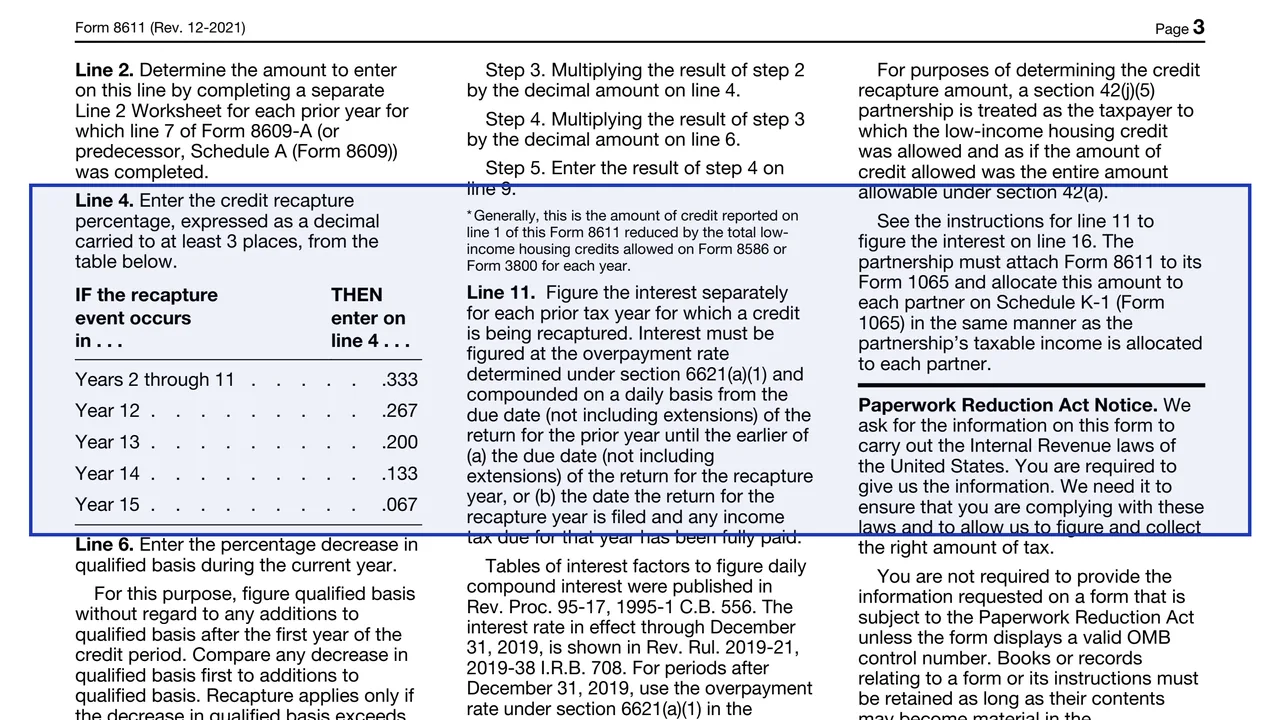
Enter the percentage decrease in qualified basis for the current year. The instructions say to enter 1.000 after a disposition that did not meet the requirements for avoiding recapture, or a decrease below the minimum set-aside requirements of section 42(g)(1).
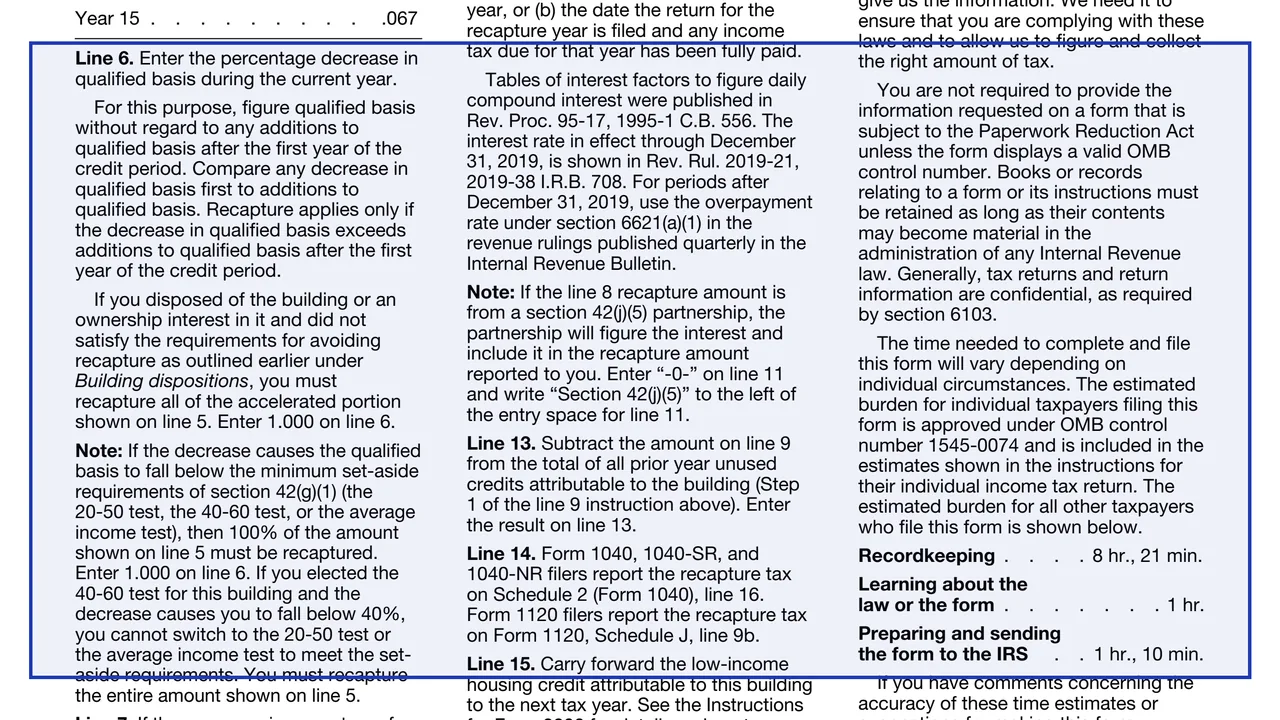
Figure the unused portion of the accelerated amount with the five steps in the instructions. Figure the line 11 interest separately for each prior year at the overpayment rate under section 6621(a)(1), compounded daily.
The instructions say Form 1040, 1040-SR and 1040-NR filers report the line 14 recapture tax on Schedule 2 (Form 1040), line 16, and Form 1120 filers on Form 1120, Schedule J, line 9b. A line 15 amount carries forward to the next tax year.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says Attach to your return. If more than one Form 8611 is filed, the line 14 amounts from all forms are added and the total goes on the return.
The form says to complete a separate Form 8611 for each building to which recapture applies.
The instructions list copies of the Forms 8586 (and Form 3800, if applicable), 8609, 8609-A and 8611 that were filed.
The instructions say to keep a copy of all Forms 8586, 8609, 8609-A, 8611 and 8693 for 3 years after the 15-year compliance period ends.
If the decrease in qualified basis comes from a change in the amount at risk on the building, the instructions say the credit taken in prior years is recalculated under section 42(k) first.
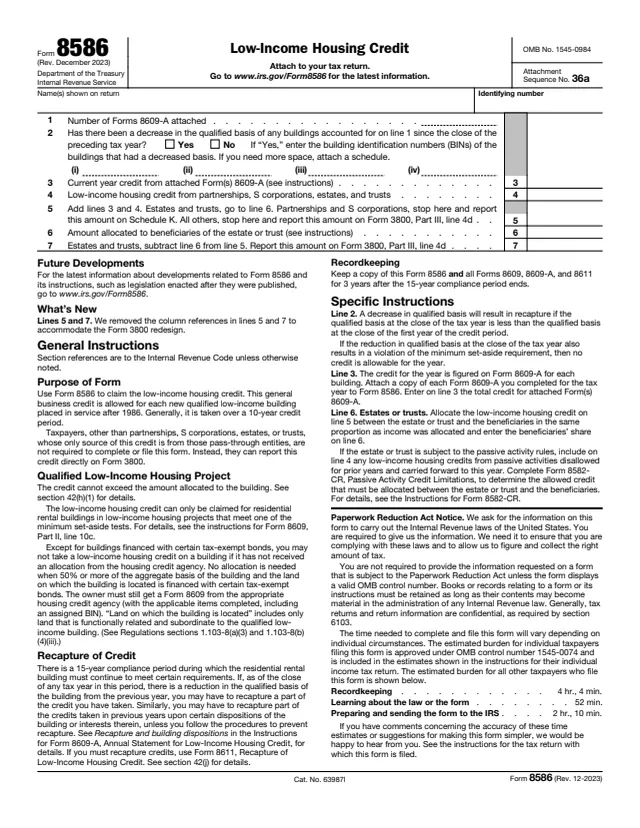
8586
14 fields, 1 page
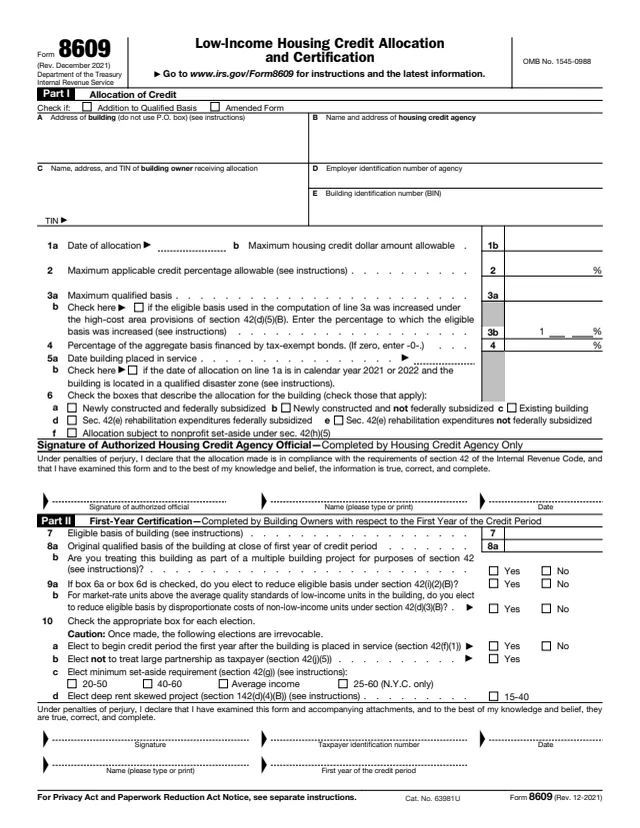
8609
44 fields, 1 page
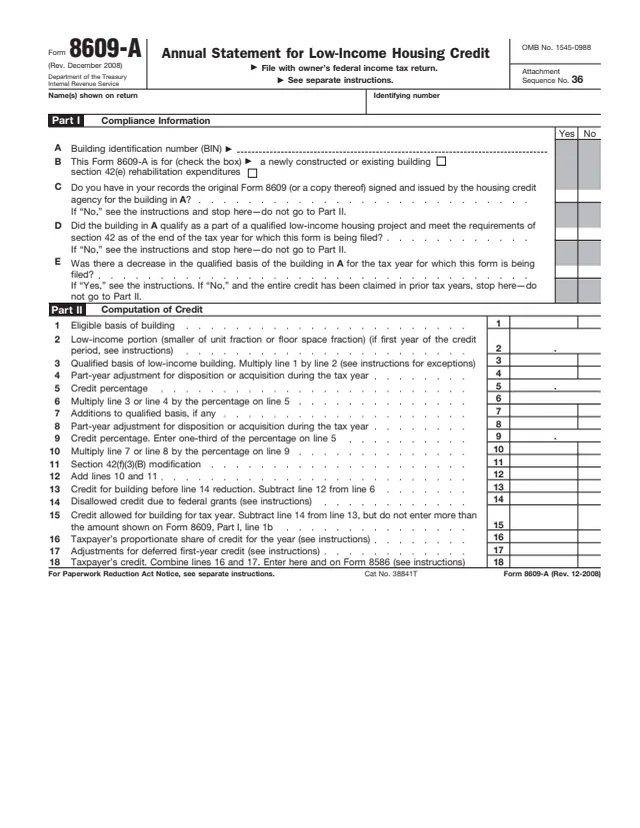
8609-A
43 fields, 1 page

3800
1,921 fields, 9 pages
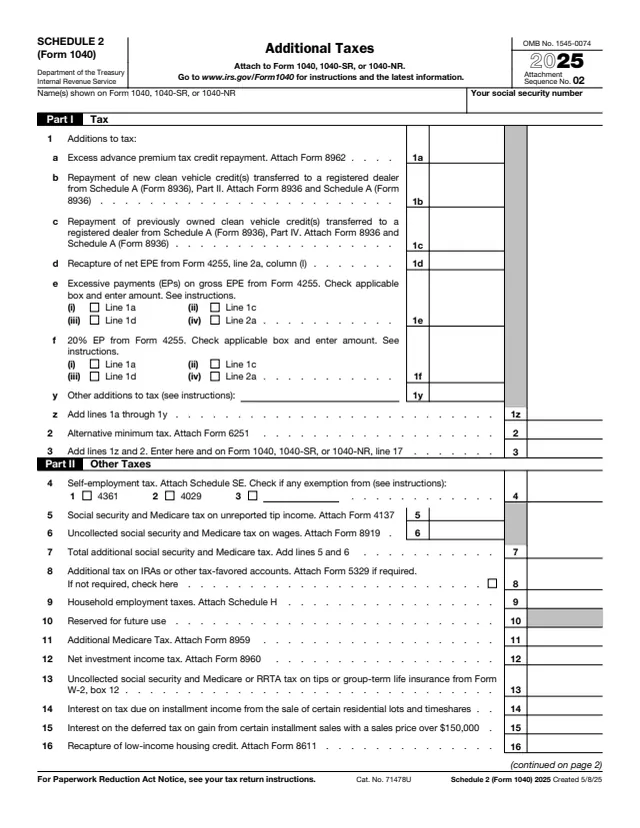
1040
63 fields, 2 pages

1065
440 fields, 6 pages
The form is filed by the taxpayer that claimed the low-income housing credit, attached to that taxpayer's return, and goes to the IRS with it.
No tool matches that search.
The taxpayer that claimed the low-income housing credit attaches it to its return when part of the credit is recaptured. Flow-through entities pass recapture to partners, shareholders and beneficiaries on Schedule K-1.
The form says a decrease in qualified basis from one year to the next, or disposing of a building or an interest in it, when the procedures that would have prevented recapture were not followed.
The instructions list exceptions, including a casualty loss when the property is restored or replaced within a reasonable period, and a decrease that does not exceed later additions to qualified basis.
The instructions say Form 1040, 1040-SR and 1040-NR filers use Schedule 2 (Form 1040), line 16, and Form 1120 filers use Form 1120, Schedule J, line 9b.
The instructions say it is a partnership with at least 35 partners, unless it elects not to be treated as one. An individual and his or her spouse, and their estates, count as one partner.
The About page lists only the form. The instructions are printed on pages 2 and 3 of the Form 8611 PDF.