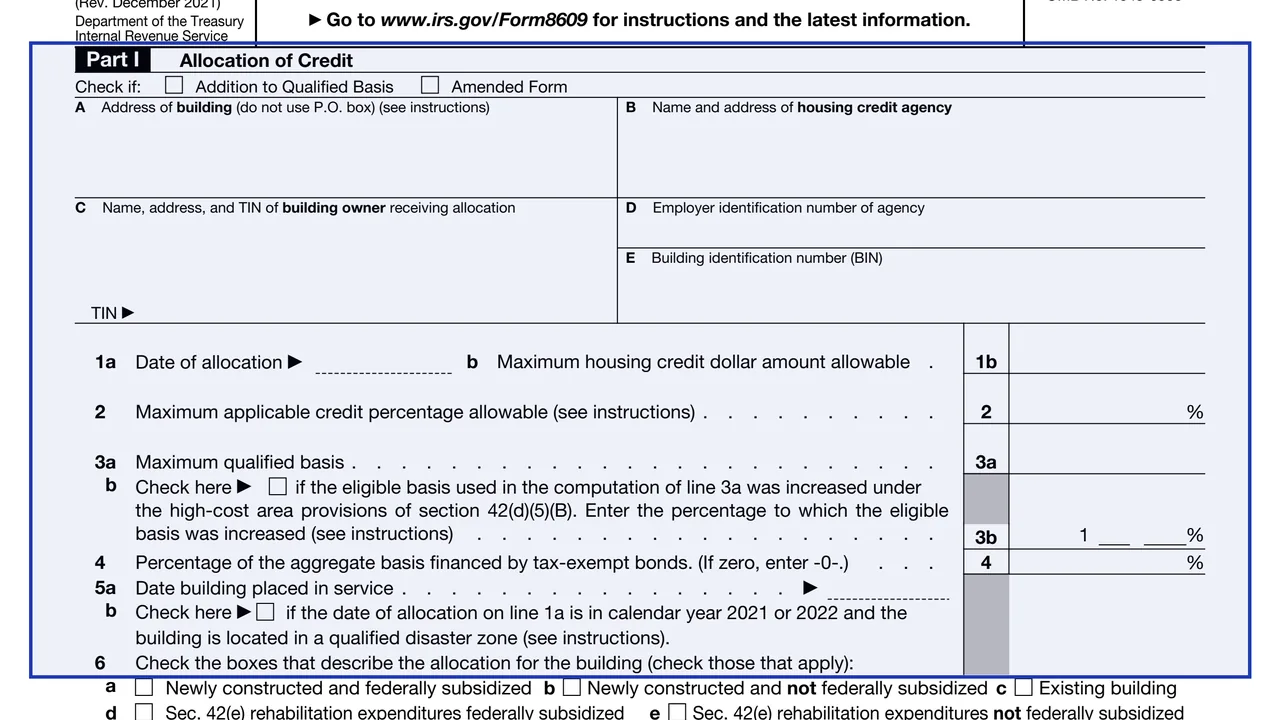
Part I, items A to E
Building address, agency name and address, owner name, address and TIN, agency EIN and building identification number (BIN), plus boxes for an addition to qualified basis or an amended form.
8609
Low-Income Housing Credit Allocation and Certification
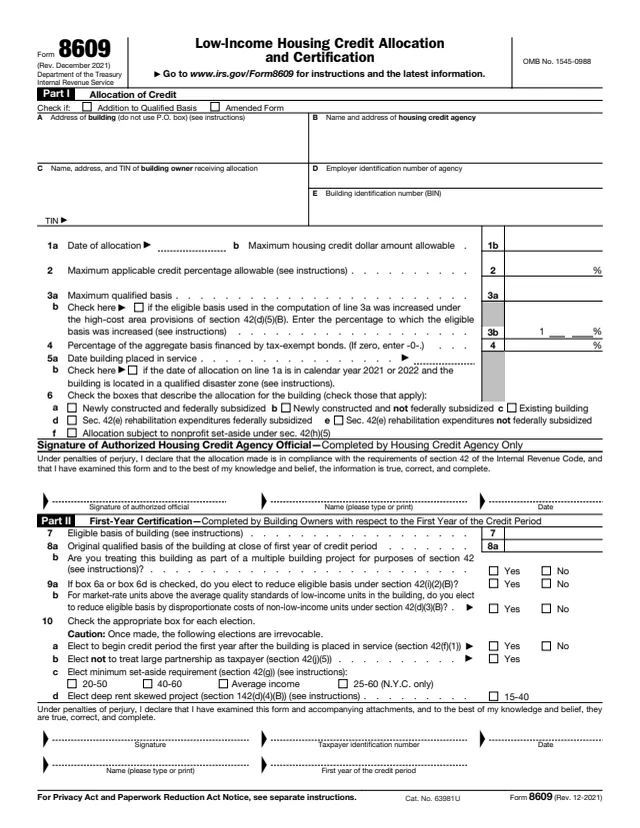
Form 8609, Low-Income Housing Credit Allocation and Certification, is part of the low-income housing credit. The About page says owners of residential low-income rental buildings are allowed the credit for each qualified building over a 10-year credit period, and that the form can be used to obtain a housing credit allocation from the housing credit agency and to certify certain information.
The form has two parts. Part I, Allocation of Credit, is completed and signed by the housing credit agency. Part II, First-Year Certification, is completed by the building owner for the first year of the credit period. The About page says a separate Form 8609 must be issued for each building in a multiple building project.
The building owner then files the original with the IRS once. You can fill out the PDF free in your browser on this page and download it without an account.
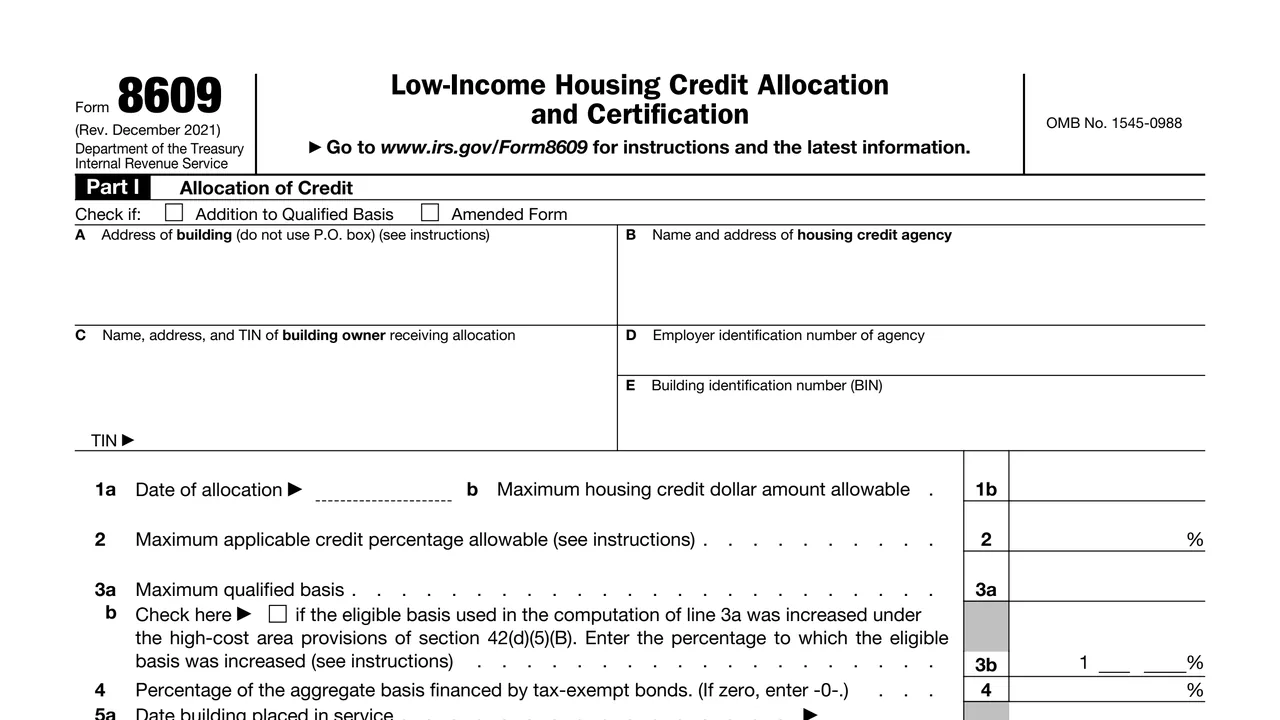
Building address, agency name and address, owner name, address and TIN, agency EIN and building identification number (BIN), plus boxes for an addition to qualified basis or an amended form.
Date of allocation, maximum housing credit dollar amount, maximum applicable credit percentage, maximum qualified basis, tax-exempt bond percentage and placed in service date.
Boxes describing the allocation, such as newly constructed, existing building or nonprofit set-aside, then the authorized agency official's signature.
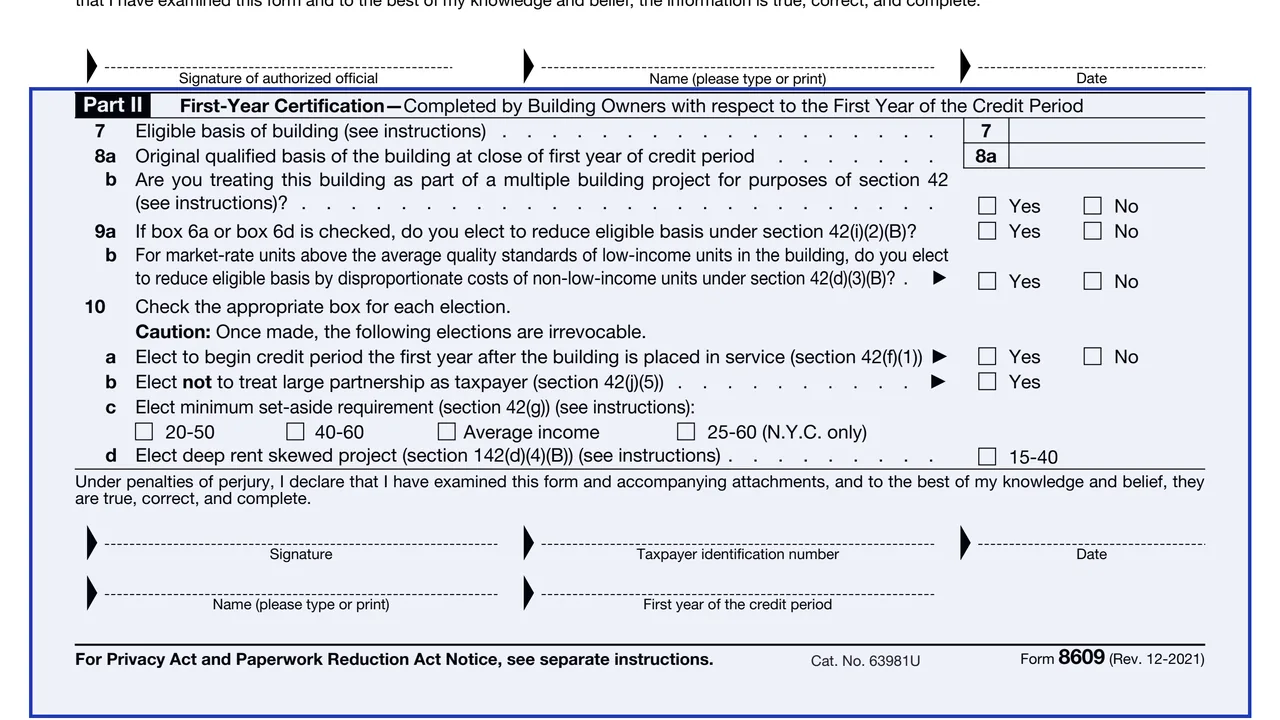
The owner's first-year figures: eligible basis, original qualified basis, multiple building project status, and elections to reduce eligible basis.
Elections on the start of the credit period, large partnership treatment, the minimum set-aside test and a deep rent skewed project. The form says they are irrevocable.
The owner's signature, taxpayer identification number, date, name and first year of the credit period.
The agency enters the allocation details. The instructions say line 1b should equal the line 2 percentage multiplied by line 3a, and line 4 shows -0- rather than a blank when no bonds were used.
The instructions say completing Part II certifies the placed in service date matches line 5a. If the date is wrong or missing, they say to get a new or amended form from the agency.
Enter the eligible basis in dollars at the close of the first year of the credit period. The instructions say it doesn't include land, and to multiply by any increased percentage on line 3b.
Multiply line 7 by the smaller of the unit fraction or the floor space fraction as of the close of the first year of the credit period.
The instructions say each building is a separate project unless a statement attached to Form 8609 identifies every building in the project, with names, addresses and BINs.
Answer the basis reduction questions and choose the elections; the form cautions that line 10 elections are irrevocable. Then sign and enter the TIN, date and first year of the credit period.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions describe a one-time submission to the Low-Income Housing Credit (LIHC) Unit at Department of the Treasury, Internal Revenue Service Center, Philadelphia, PA 19255-0549.
The instructions say the original goes in no later than the due date, including extensions, of the owner's first tax return filed with Form 8609-A.
The agency submits a copy with Form 8610 and keeps a copy. The instructions add that an agency may ask the owner for a copy with Part II completed.
The instructions say Form 8609-A is filed for each year of the 15-year compliance period, and the credit is claimed on Form 8586.
The instructions list keeping the original Form 8609 and related Forms 8609-A, 8586 and 8611 for 3 years after the due date of the return for the year the 15-year compliance period ends.
The About page lists updates to the Instructions for Form 8609 (Rev. December 2025) for projects financed with tax-exempt bonds, clarified May 29, 2026.
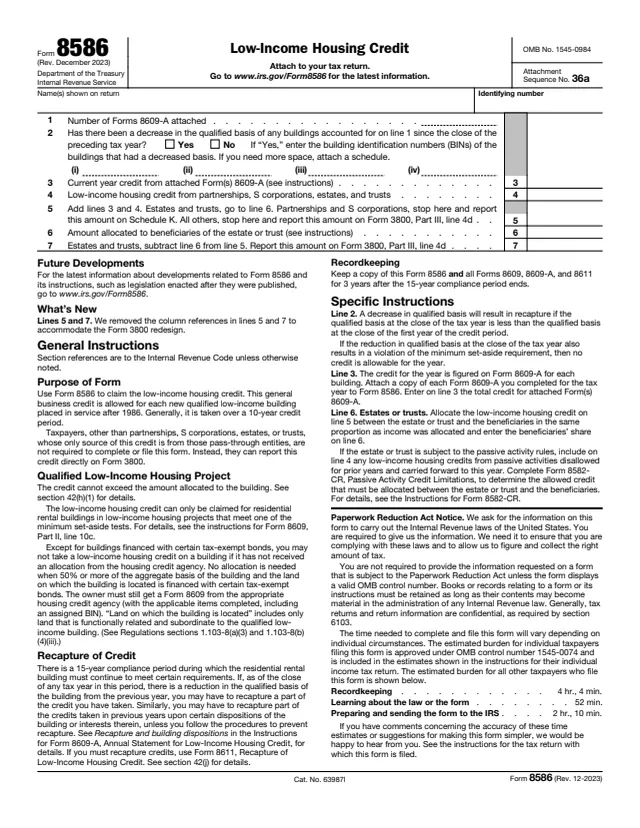
8586
14 fields, 1 page
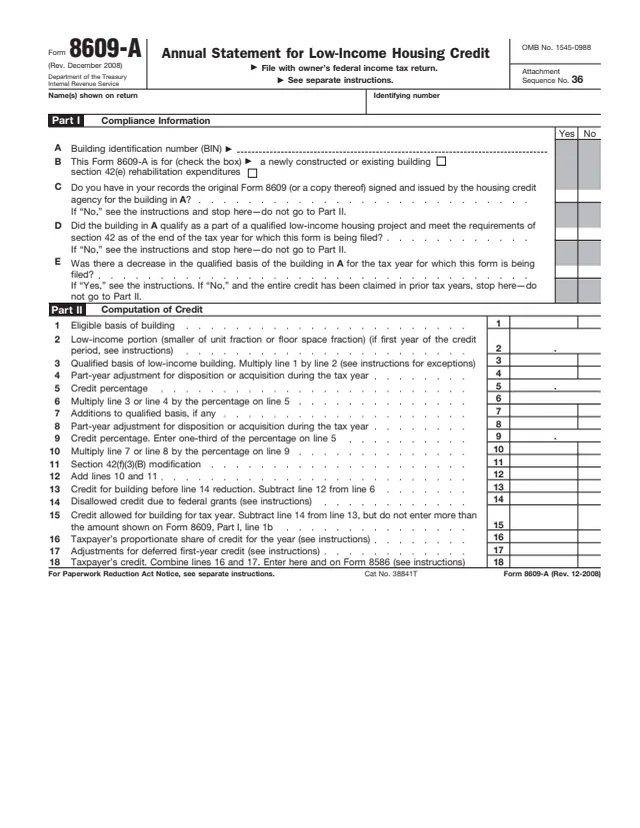
8609-A
43 fields, 1 page
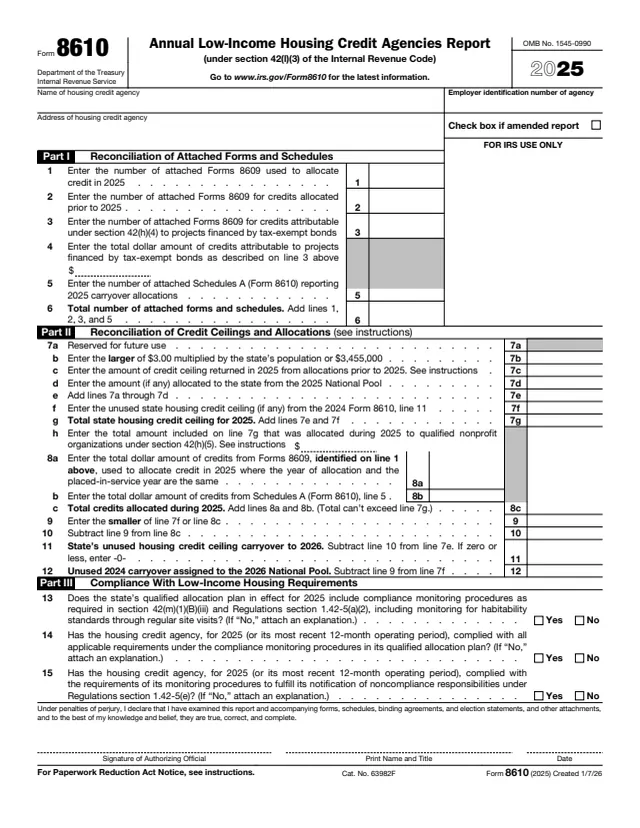
8610
32 fields, 3 pages
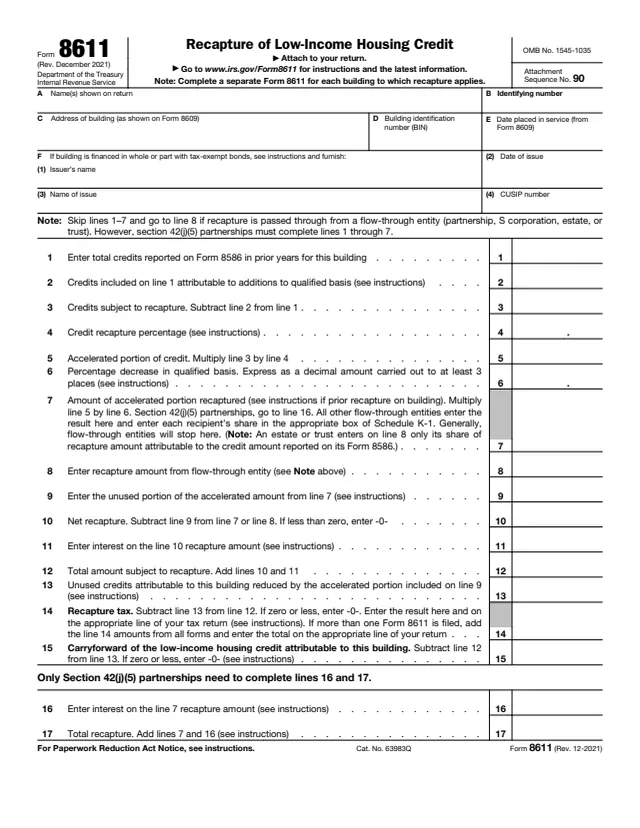
8611
37 fields, 3 pages
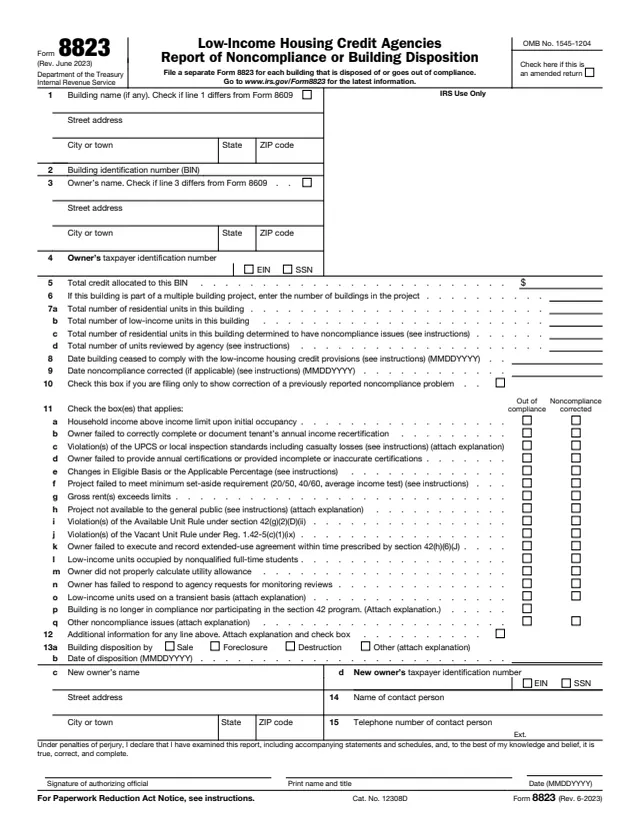
8823
84 fields, 5 pages
Two parties complete the form: the housing credit agency fills in Part I, and the building owner fills in Part II and files it.
No tool matches that search.
The housing credit agency. The form marks the signature as completed by housing credit agency only, and the instructions say the agency signs Part I and sends the original to the owner.
No. The About page says a separate Form 8609 must be issued for each building in a multiple building project.
The instructions give the LIHC Unit at Department of the Treasury, Internal Revenue Service Center, Philadelphia, PA 19255-0549, as a one-time submission.
The form says that once made, the line 10 elections are irrevocable.
The building identification number, assigned by the housing credit agency. The instructions say the BIN first assigned to a building is used for any later allocation that needs a separate Form 8609.
The instructions say the credit is claimed on Form 8586, and Form 8609-A is filed for each year of the 15-year compliance period.