Header
Name, employer identification number and address of the housing credit agency, and a box to check if this is an amended report.
8610
Annual Low-Income Housing Credit Agencies Report (under section 42(l)(3) of the Internal Revenue Code)
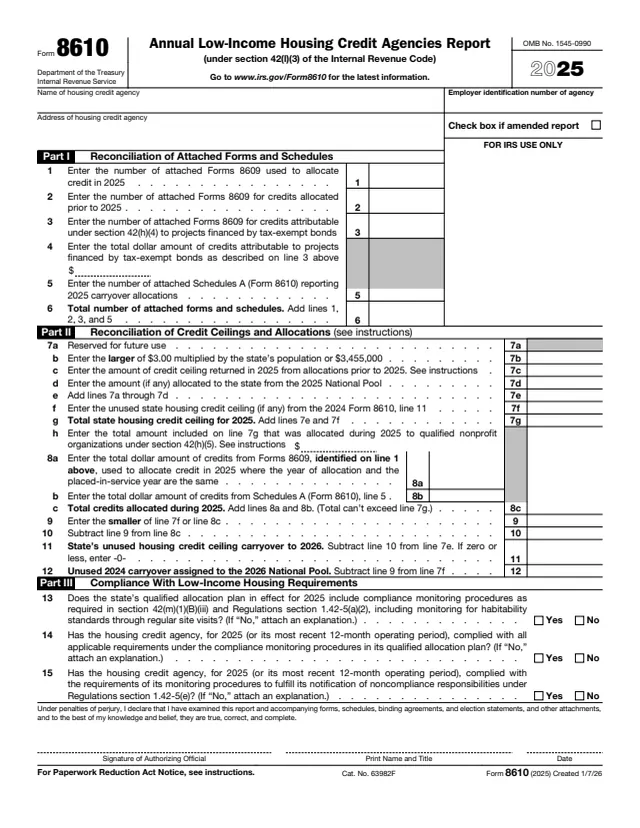
Form 8610, Annual Low-Income Housing Credit Agencies Report, is filed under section 42(l)(3) by housing credit agencies, not by building owners or individuals. The instructions say agencies use it to transmit Forms 8609, Low-Income Housing Credit Allocation and Certification, and Schedules A (Form 8610) to the IRS, and to report the dollar amount of housing credits allocated during the calendar year.
This page covers the 2025 form. Part I counts the attached forms and schedules, Part II reconciles the state housing credit ceiling with the credits allocated, and Part III asks three yes or no questions about compliance monitoring. An authorizing official of the agency signs it under penalties of perjury. The instructions on pages 2 and 3 of the PDF give the filing date and the IRS address.
You can fill out Form 8610 free in your browser on this page and download the result without an account.
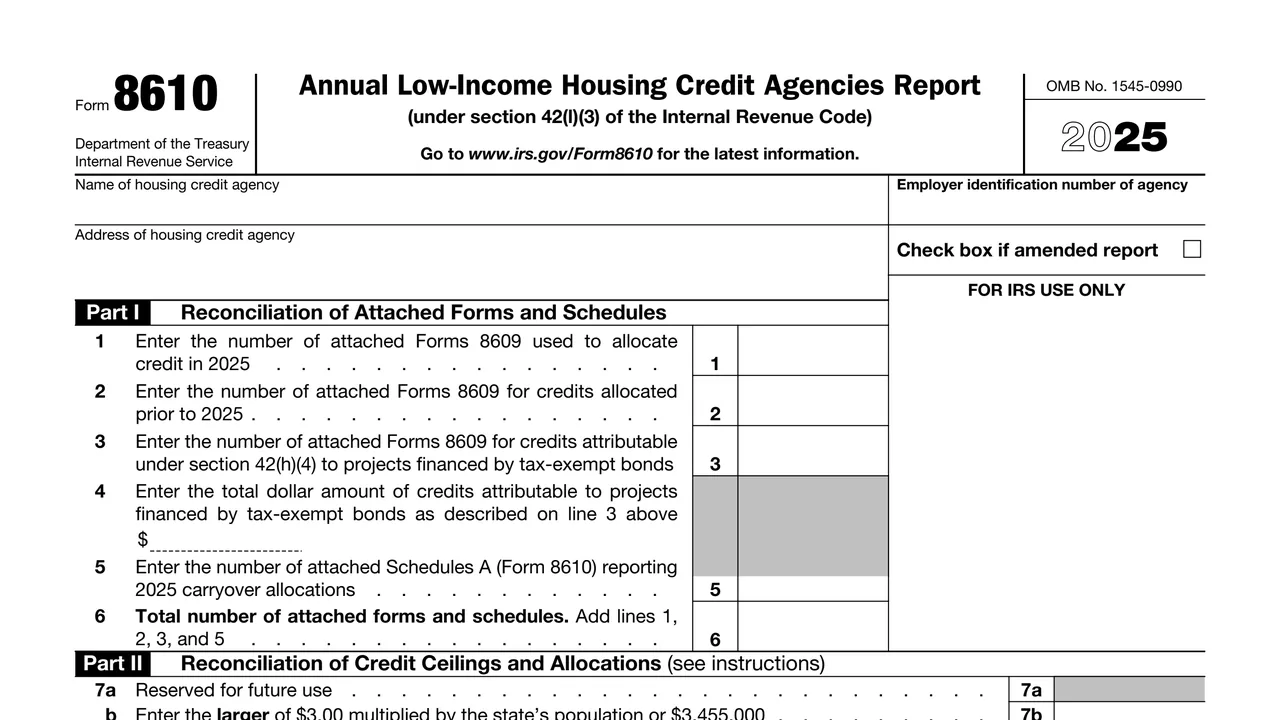
Name, employer identification number and address of the housing credit agency, and a box to check if this is an amended report.
Lines 1 to 6 count the Forms 8609 used to allocate credit in 2025, those for credits allocated before 2025, those for tax-exempt bond projects, the dollar amount of bond-financed credits, the Schedules A, and the total attached.
Lines 7a to 12 build the state housing credit ceiling for 2025, report credits allocated during 2025, and figure the unused ceiling carried to 2026 and the unused 2024 carryover assigned to the 2026 National Pool.
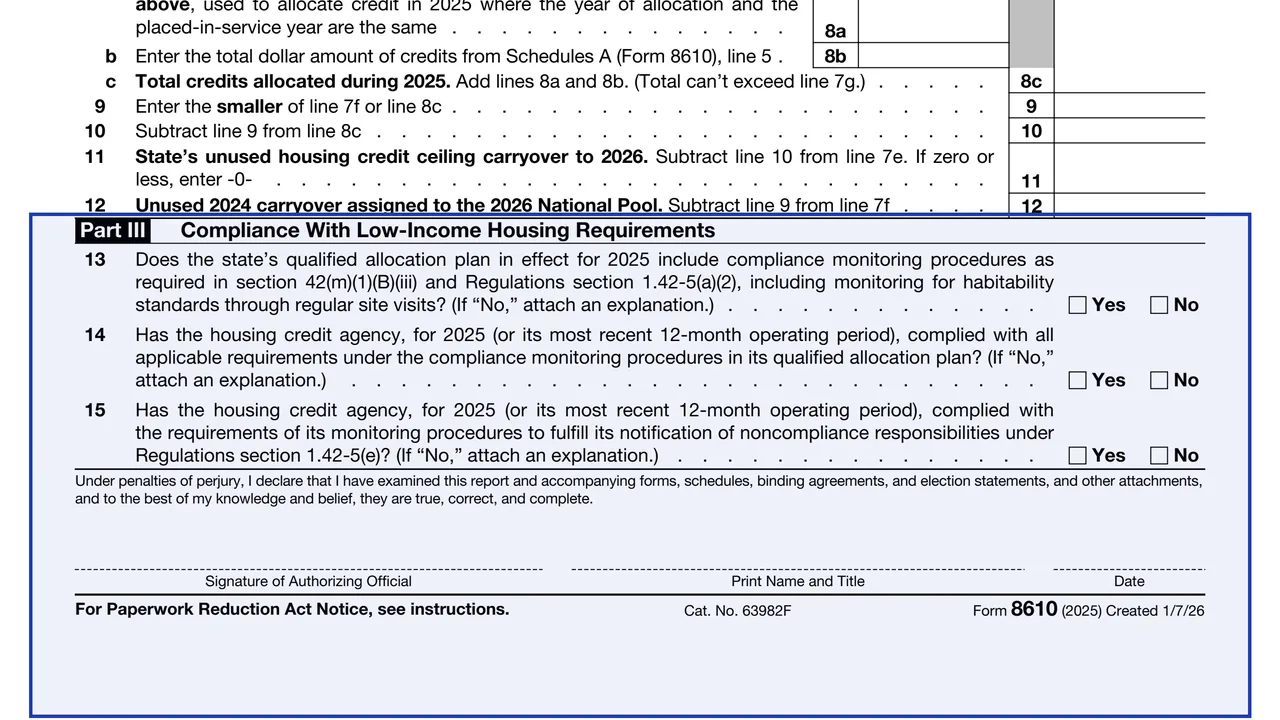
Lines 13 to 15 ask whether the qualified allocation plan includes compliance monitoring procedures and whether the agency complied with them and with its notification of noncompliance duties. A No answer needs an attached explanation.
Signature, printed name and title of the authorizing official, and the date, under a penalties of perjury declaration.
Enter the number of attached Forms 8609 on lines 1 to 3 and the Schedules A on line 5. The instructions say line 1 does not include Forms 8609 for allocations made before 2025 on carryover allocation documents; those go on line 2.
The form says to enter the larger of $3.00 multiplied by the state's population or $3,455,000. The instructions say population is determined under section 146(j) and point to Notice 2025-18 for the figures.
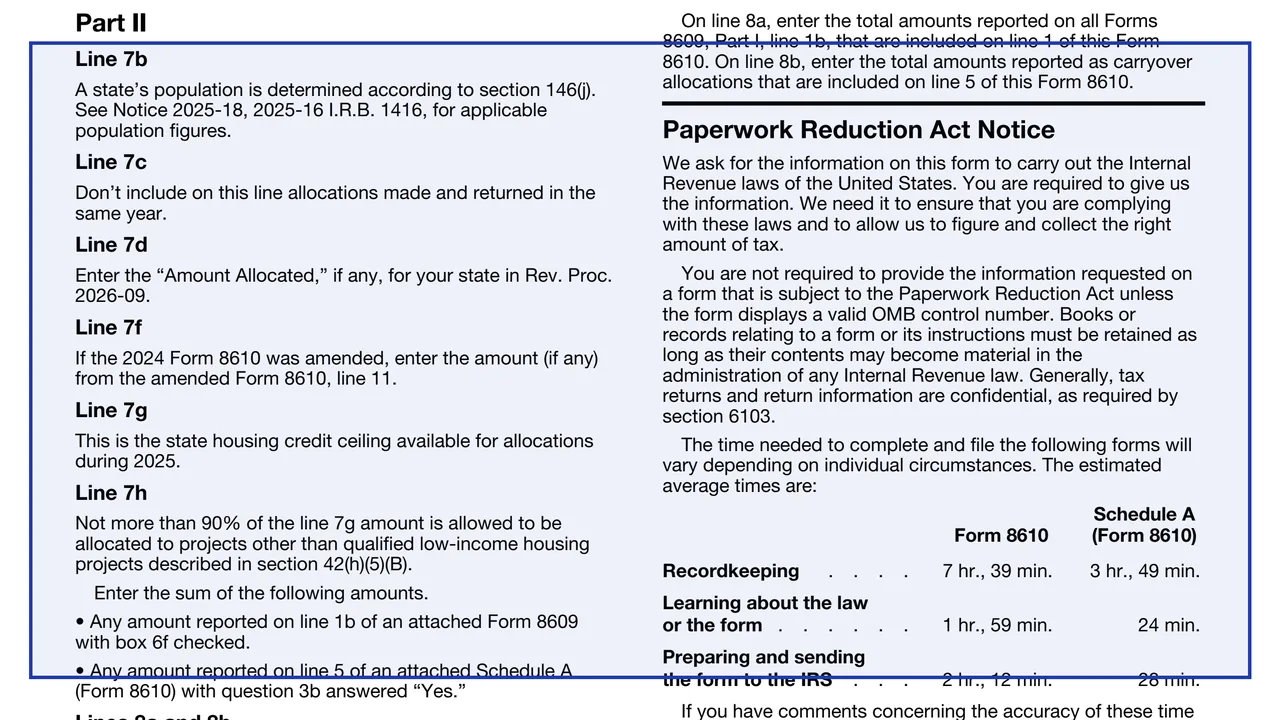
Add returned ceiling, any National Pool amount from Rev. Proc. 2026-09 and the unused 2024 ceiling from the 2024 Form 8610, line 11. Line 7h reports the amount allocated to qualified nonprofit organizations under section 42(h)(5).
Enter credits from the attached Forms 8609, Part I, line 1b, on line 8a and carryover allocations from Schedules A on line 8b. The form says the line 8c total can't exceed line 7g. Then figure the carryover lines 9 to 12.
Answer lines 13 to 15, attaching an explanation for any No answer, and have the authorizing official sign, print a name and title, and date the report.
The instructions say to attach Forms 8609 first, then Schedules A (Form 8610), then Schedules A for projects approved for carryover allocation relief under Rev. Proc. 2014-49.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to send Form 8610 and attached forms and schedules to Department of the Treasury, Internal Revenue Service Center, Philadelphia, PA 19255-0549.
The instructions say to file the 2025 Form 8610 with accompanying Forms 8609 (with only Part I completed) and Schedules A (Form 8610) by February 28, 2026.
The instructions say the $100 penalty under section 6652(j) applies to any failure to file Form 8610 when due.
Check the amended report box and use the same version of the form that was originally filed. Complete only the lines being amended and attach documentation explaining why.
An agency that granted relief under section 10 of Rev. Proc. 2014-49 attaches a signed statement labeled "Relief Under Section 10 of Rev. Proc. 2014-49" with the details the instructions list.
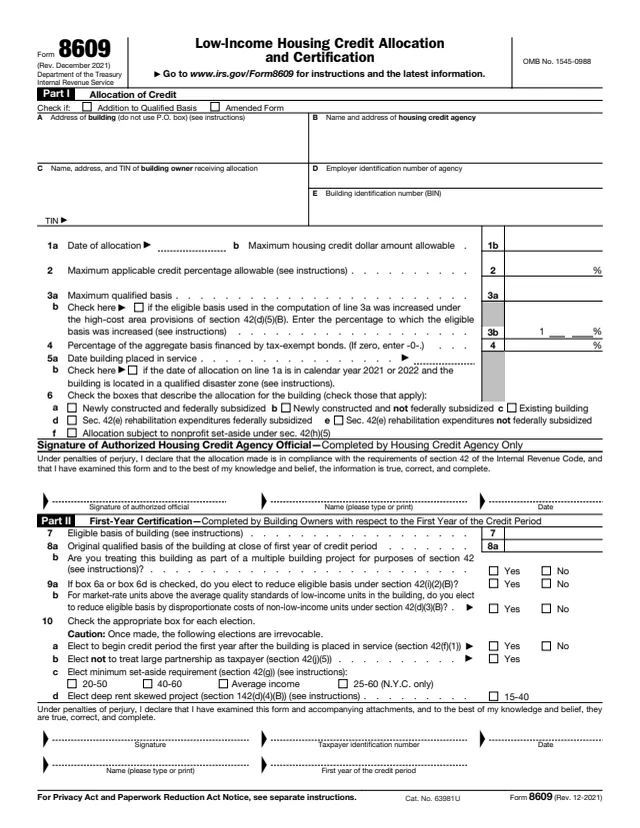
8609
44 fields, 1 page
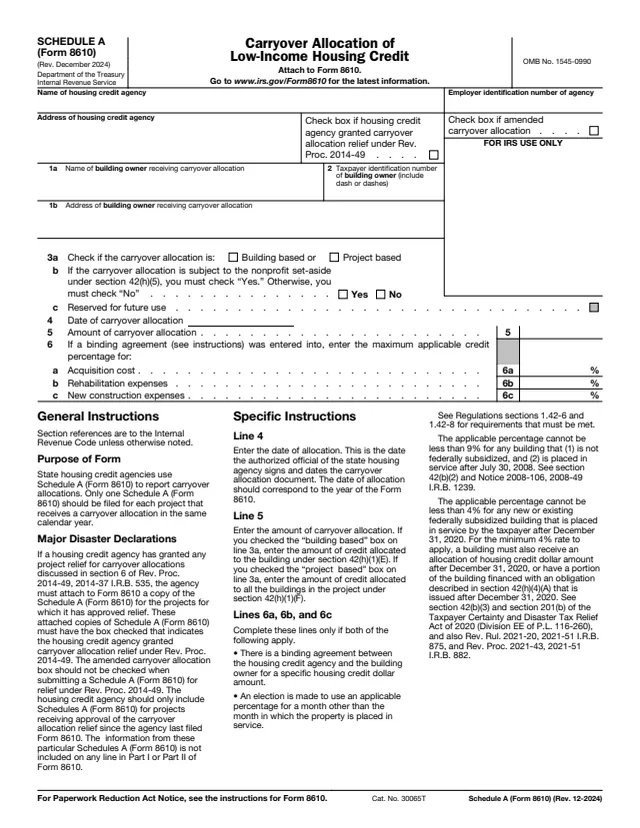
8610 Sch. A
18 fields, 1 page
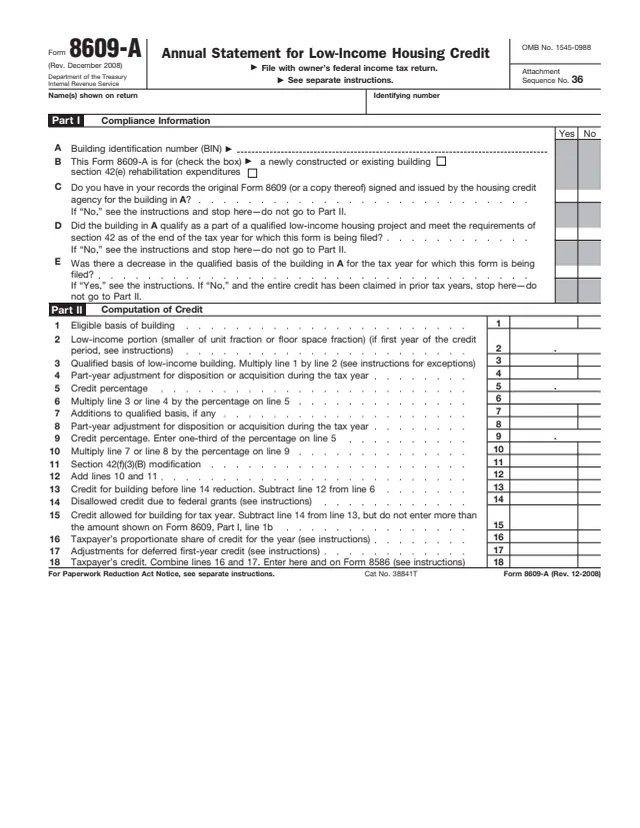
8609-A
43 fields, 1 page
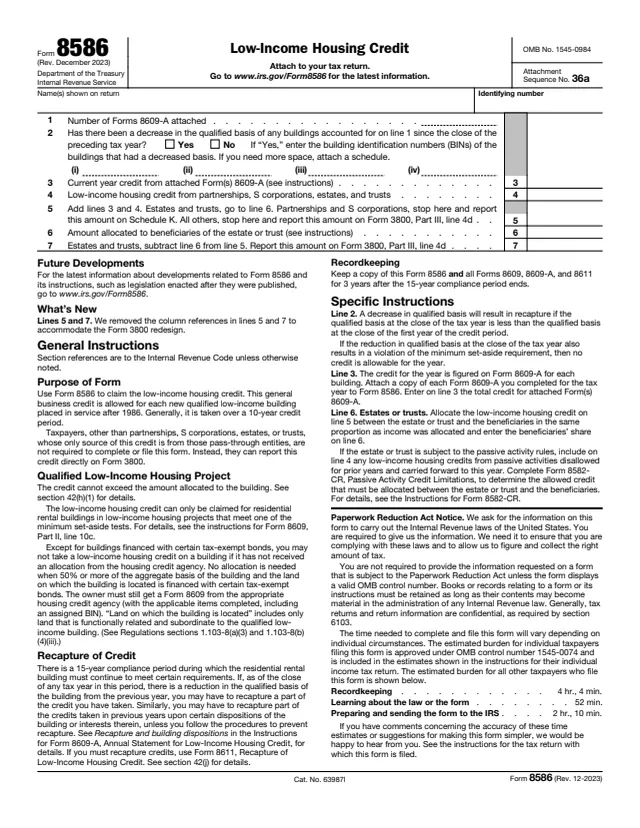
8586
14 fields, 1 page
8823
84 fields, 5 pages
The instructions say any housing credit agency authorized to make an allocation of the credit on a Form 8609, or a carryover allocation on a Schedule A (Form 8610), to an owner of a qualified low-income building during the calendar year completes and files Form 8610, even if no credit is actually allocated.
No tool matches that search.
Housing credit agencies authorized to allocate the low-income housing credit. The instructions say they file it even if no credit is actually allocated. Building owners do not file it.
Forms 8609 with only Part I completed and Schedules A (Form 8610) reporting carryover allocations, in the order the instructions list.
The instructions say to file it with the attached forms and schedules by February 28, 2026.
The instructions give Department of the Treasury, Internal Revenue Service Center, Philadelphia, PA 19255-0549.
The form says to enter the larger of $3.00 multiplied by the state's population or $3,455,000. Lines 7c, 7d and 7f add returned ceiling, any National Pool amount and the unused 2024 ceiling.
The instructions say to check the amended report box, use the same year's version of the form, complete only the lines being amended and attach an explanation.