Line 1: Forms 8609-A attached
The number of Forms 8609-A attached to Form 8586.
8586
Low-Income Housing Credit
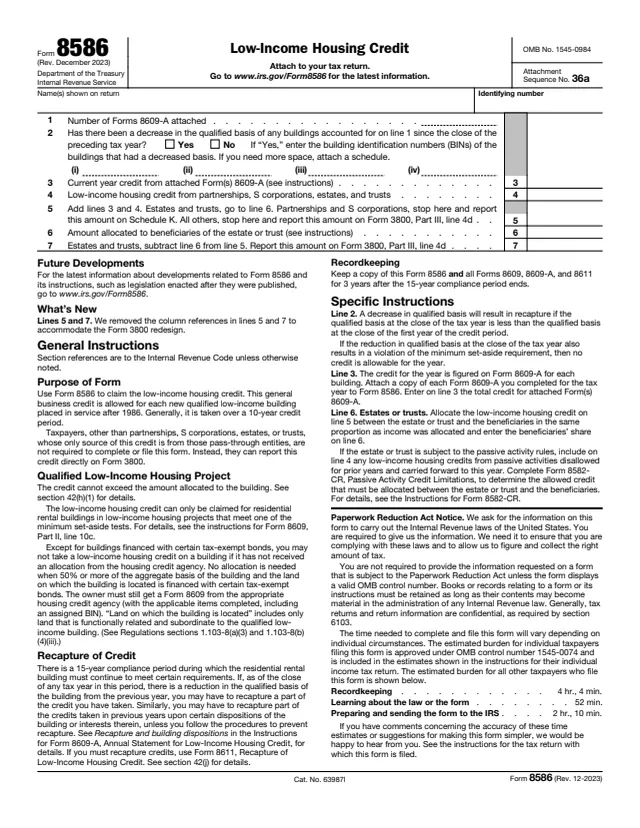
Form 8586, Low-Income Housing Credit, is the form used to claim the low-income housing credit. The IRS About page says it is used by owners of qualified residential rental buildings in low-income housing projects to figure the amount of their low-income housing credit, a component of the general business credit.
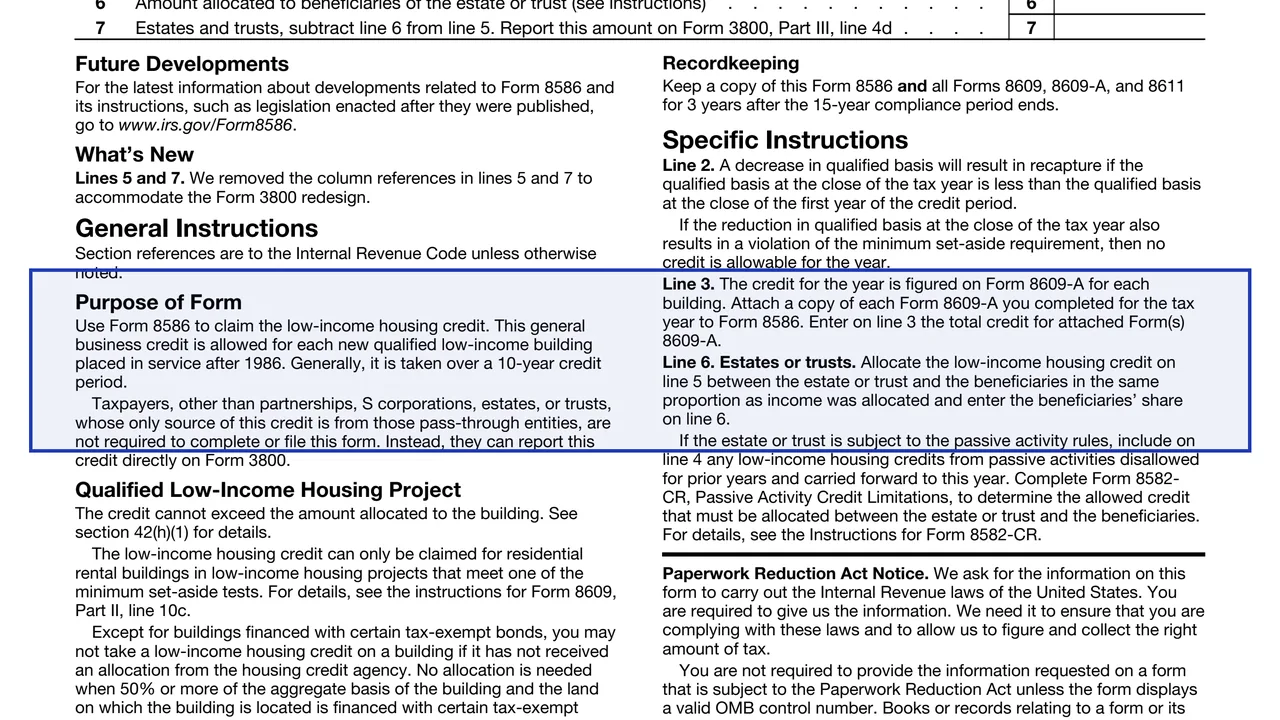
The form says this general business credit is allowed for each new qualified low-income building placed in service after 1986, and that it is generally taken over a 10-year credit period. The credit for each building is figured on Form 8609-A, and a copy of each Form 8609-A completed for the tax year is attached to Form 8586. Form 8586 itself is attached to the filer's tax return, and its instructions are printed on the form.
This page hosts the December 2023 revision. You can fill out Form 8586 free in your browser on this page and download the result without an account.
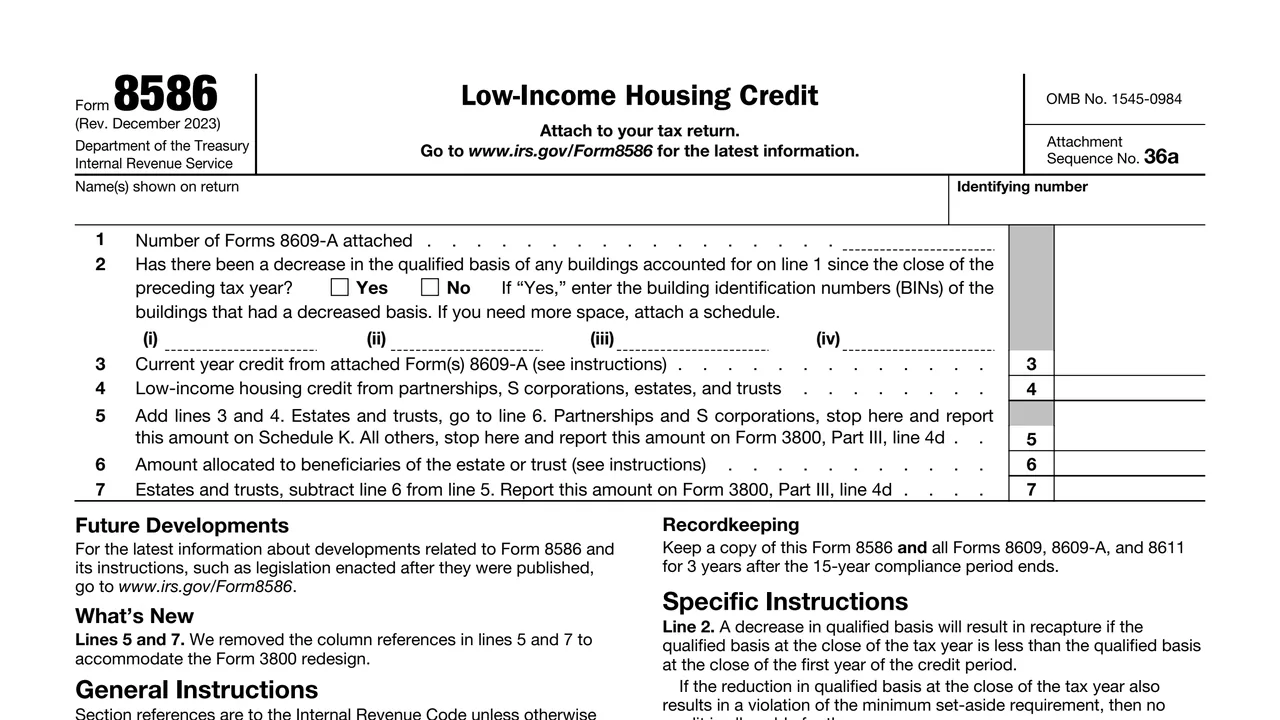
The number of Forms 8609-A attached to Form 8586.
A Yes or No question on whether the qualified basis of any building on line 1 decreased since the close of the preceding tax year, with spaces (i) to (iv) for the building identification numbers (BINs).
The current year credit from the attached Form(s) 8609-A.
Low-income housing credit from partnerships, S corporations, estates and trusts.
Lines 3 and 4 added together. The line says where each type of filer reports the amount next.
The amount allocated to beneficiaries, and the estate's or trust's own share, which goes to Form 3800, Part III, line 4d.
Enter the name(s) shown on the return and the identifying number at the top of the form.
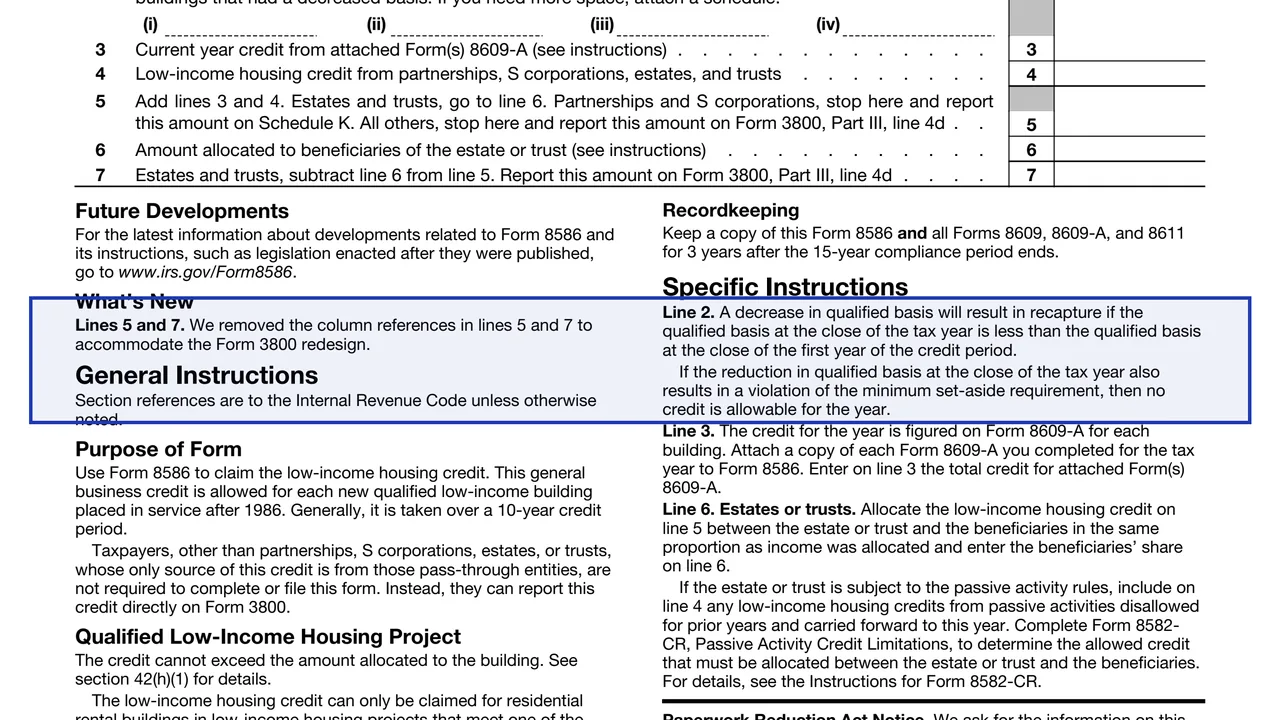
Enter the number of Forms 8609-A attached. On line 2, check Yes or No, and if Yes, enter the BINs of the buildings with a decreased basis, attaching a schedule if more space is needed. The instructions say a decrease can result in recapture when the qualified basis at the close of the tax year is less than at the close of the first year of the credit period.
The instructions say the credit for the year is figured on Form 8609-A for each building. Attach a copy of each Form 8609-A completed for the tax year and enter their total credit on line 3.
Enter low-income housing credit from partnerships, S corporations, estates and trusts. The instructions say an estate or trust subject to the passive activity rules includes disallowed prior-year passive credits carried forward, and completes Form 8582-CR.
Add lines 3 and 4. The form says estates and trusts go to line 6, partnerships and S corporations report the amount on Schedule K, and all others report it on Form 3800, Part III, line 4d.
Estates and trusts enter the beneficiaries' share on line 6, subtract line 6 from line 5 on line 7, and report the line 7 amount on Form 3800, Part III, line 4d.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return. It prints Attachment Sequence No. 36a.
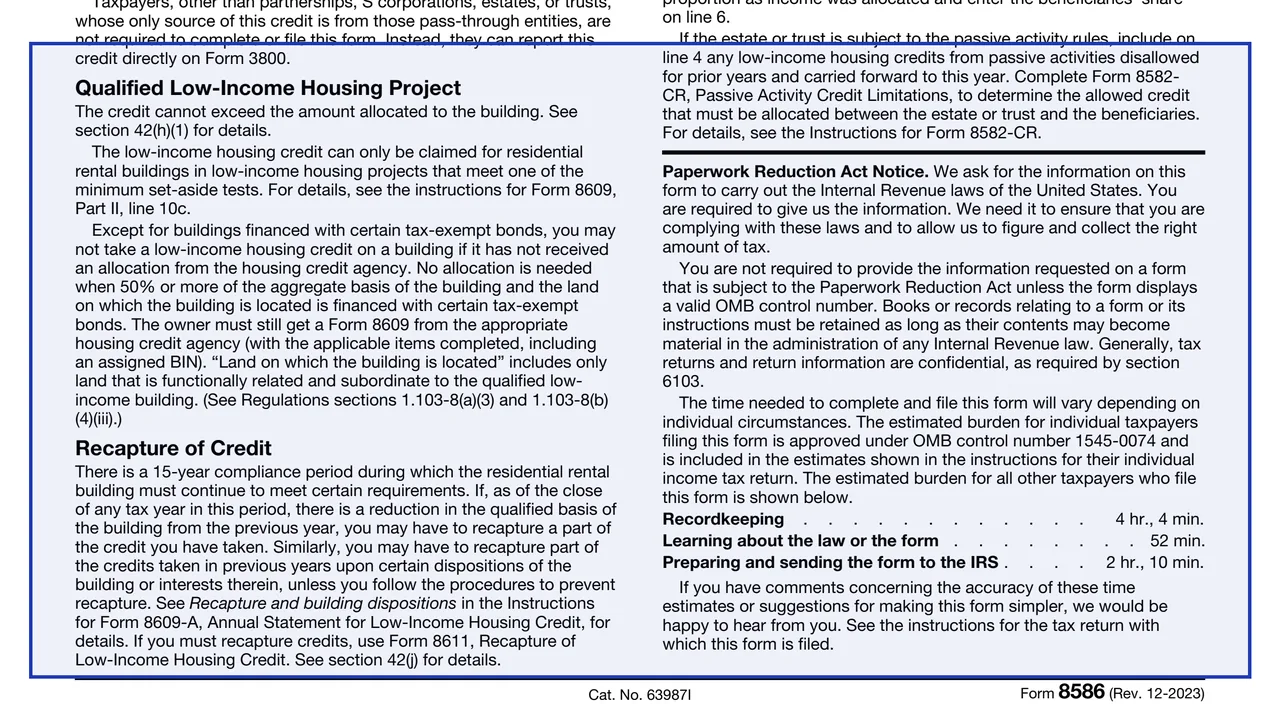
The form says that, except for buildings financed with certain tax-exempt bonds, no credit may be taken on a building that has not received an allocation from the housing credit agency. No allocation is needed when 50% or more of the aggregate basis of the building and its land is financed with certain tax-exempt bonds, but the owner still gets a Form 8609 with an assigned BIN.
The form describes a 15-year compliance period. A reduction in qualified basis, or certain dispositions of the building or interests in it, can lead to recapture of part of the credit, which is figured on Form 8611.
The form says to keep a copy of Form 8586 and all Forms 8609, 8609-A and 8611 for 3 years after the 15-year compliance period ends.
The form says the IRS removed the column references in lines 5 and 7 to accommodate the Form 3800 redesign.
For filers other than individuals, the form estimates 4 hr., 4 min. for recordkeeping, 52 min. for learning about the law or the form, and 2 hr., 10 min. for preparing and sending it.
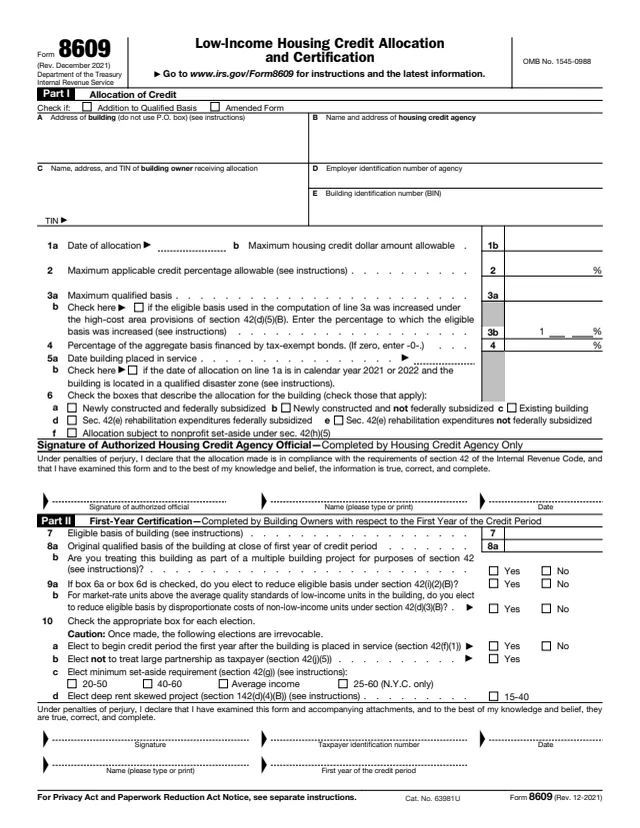
8609
44 fields, 1 page
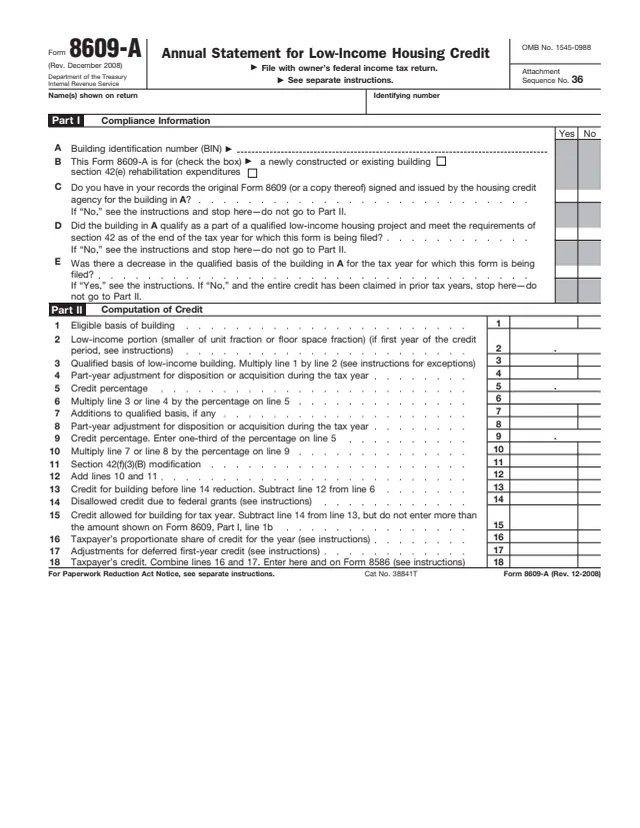
8609-A
43 fields, 1 page
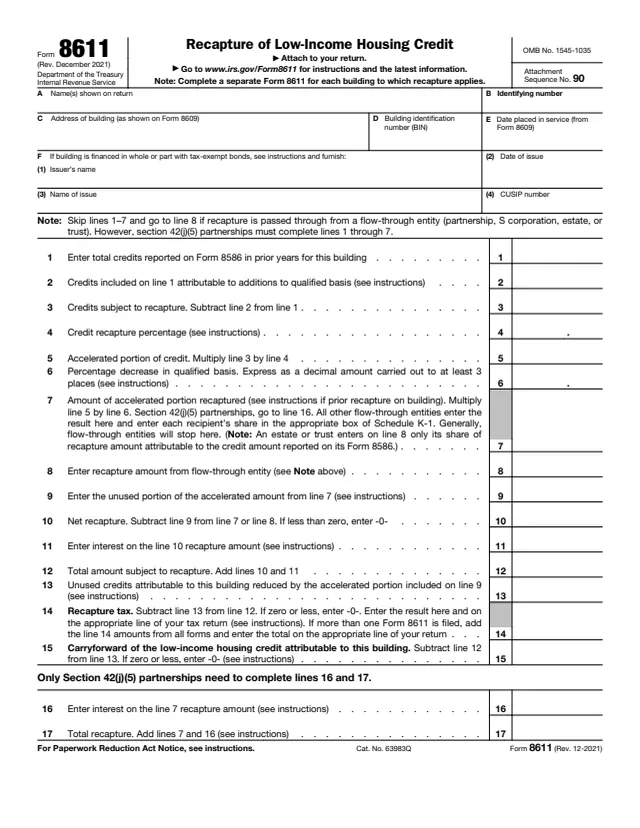
8611
37 fields, 3 pages

3800
1,921 fields, 9 pages
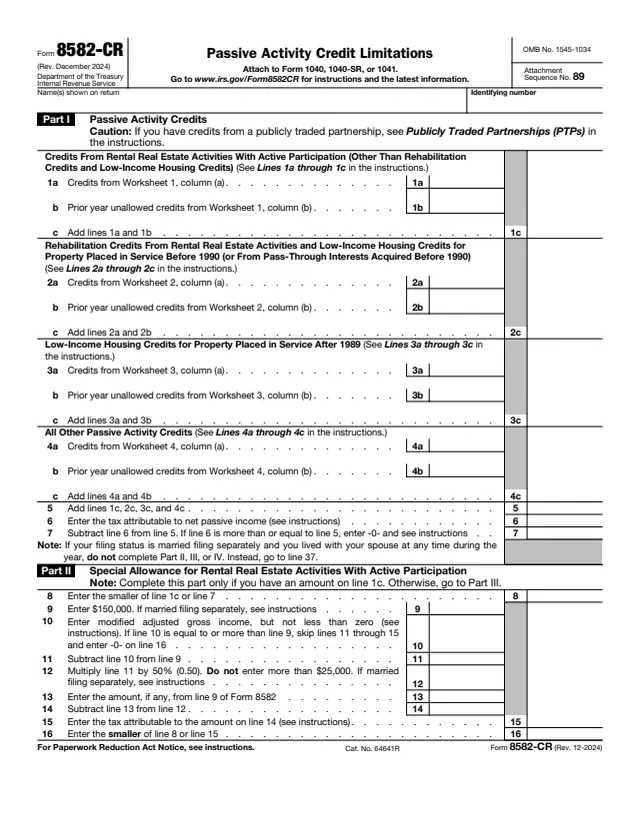
8582-CR
52 fields, 2 pages
The About page says owners of qualified residential rental buildings in low-income housing projects use the form. The form itself says which filers stop at which line, and who does not need to file it at all.
No tool matches that search.
The IRS About page says owners of qualified residential rental buildings in low-income housing projects use it to figure their low-income housing credit, a component of the general business credit.
The form says taxpayers, other than partnerships, S corporations, estates or trusts, whose only source of this credit is those pass-through entities are not required to complete or file it. They can report the credit directly on Form 3800.
On Form 8609-A. The instructions say to attach a copy of each Form 8609-A completed for the tax year and enter the total credit on line 3.
The form says the credit is generally taken over a 10-year credit period. It separately describes a 15-year compliance period during which the building continues to meet certain requirements.
The form says a reduction in qualified basis during the compliance period can require recapture of part of the credit, using Form 8611, Recapture of Low-Income Housing Credit.
They are printed on the form itself, under General Instructions and Specific Instructions, with line instructions for lines 2, 3 and 6.