7218

Clean Fuel Production Credit

Agency
IRS
Revision
December 2024
Fillable fields
219
Pages
2
Official source
IRS form page
Checked
October 21, 2026
Fill 7218 online
Page 1 of form 7218

Form 7218: Clean Fuel Production Credit

Form 7218 is used to claim the section 45Z credit for the production of qualified clean fuel produced and sold after 2024, as the IRS About page and the instructions put it. The instructions say the credit is figured by multiplying the applicable amount by each gallon (or gallon equivalent) of fuel produced and sold by the emissions factor of the fuel, and that the amount is adjusted annually for inflation.

The filer is the taxpayer that produced the fuel at a qualified facility and sold it, a pass-through entity passing the credit on, or a tax-exempt or governmental entity making an elective payment election. The instructions say to file a separate Form 7218 for each qualified facility. The form says to attach it to the tax return, and the credit then goes to Form 3800, General Business Credit, or to Schedule K for partnerships and S corporations.

This page hosts the December 2024 edition of the form. The instructions linked here were revised 12/2025. You can fill out the PDF free in your browser on this page and download it without an account.

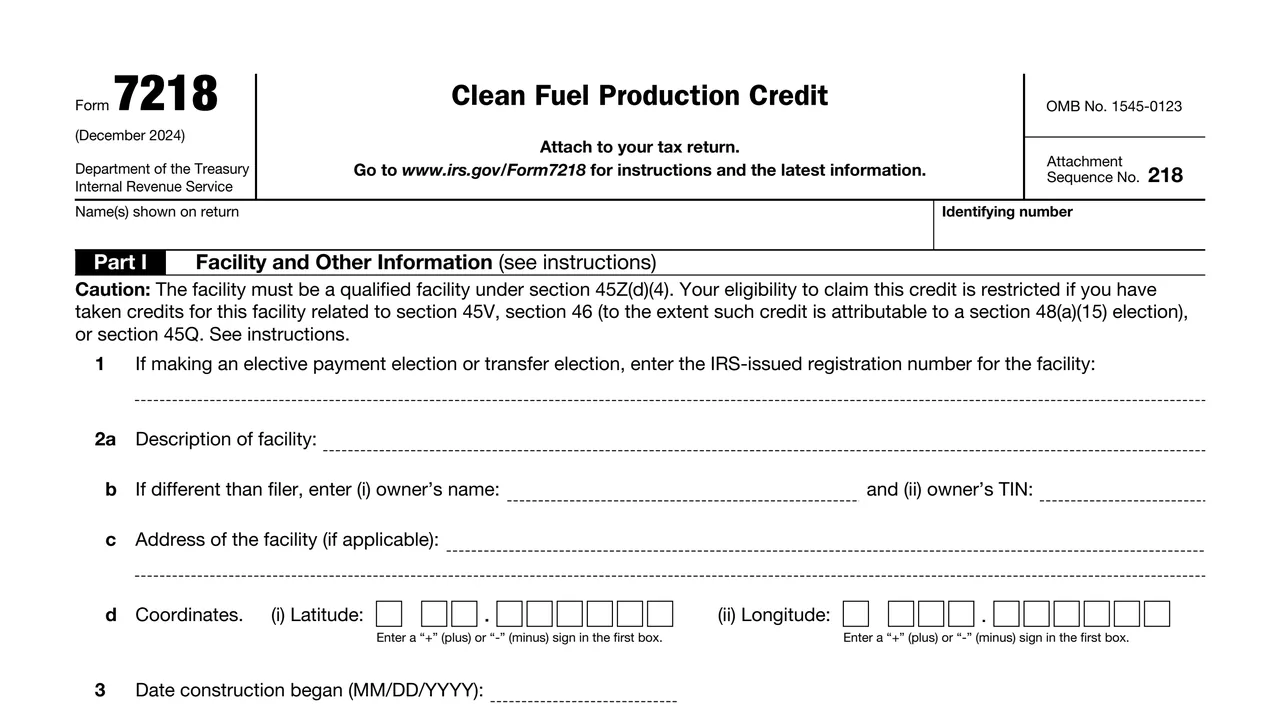
Top of page 1 of Form 7218: Clean Fuel Production Credit, as printed by IRS

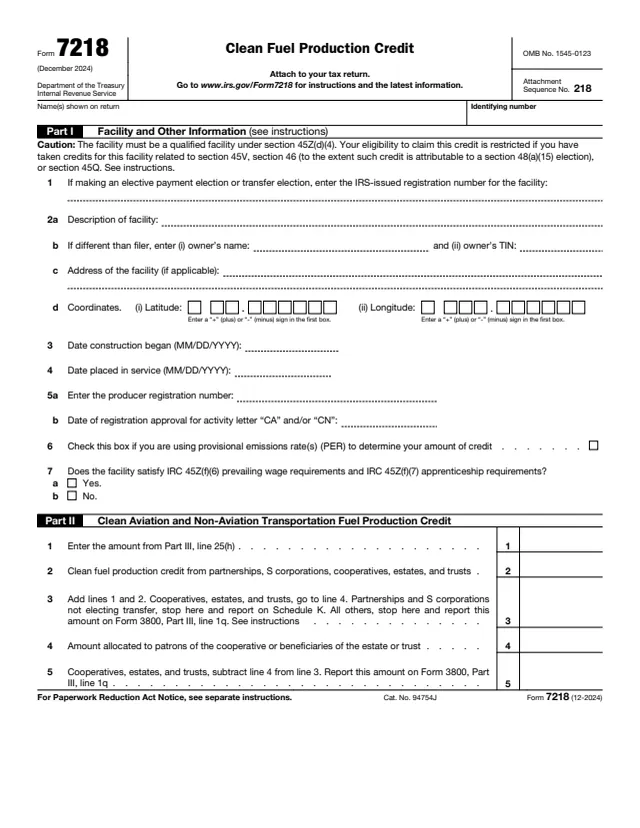
What's on Form 7218

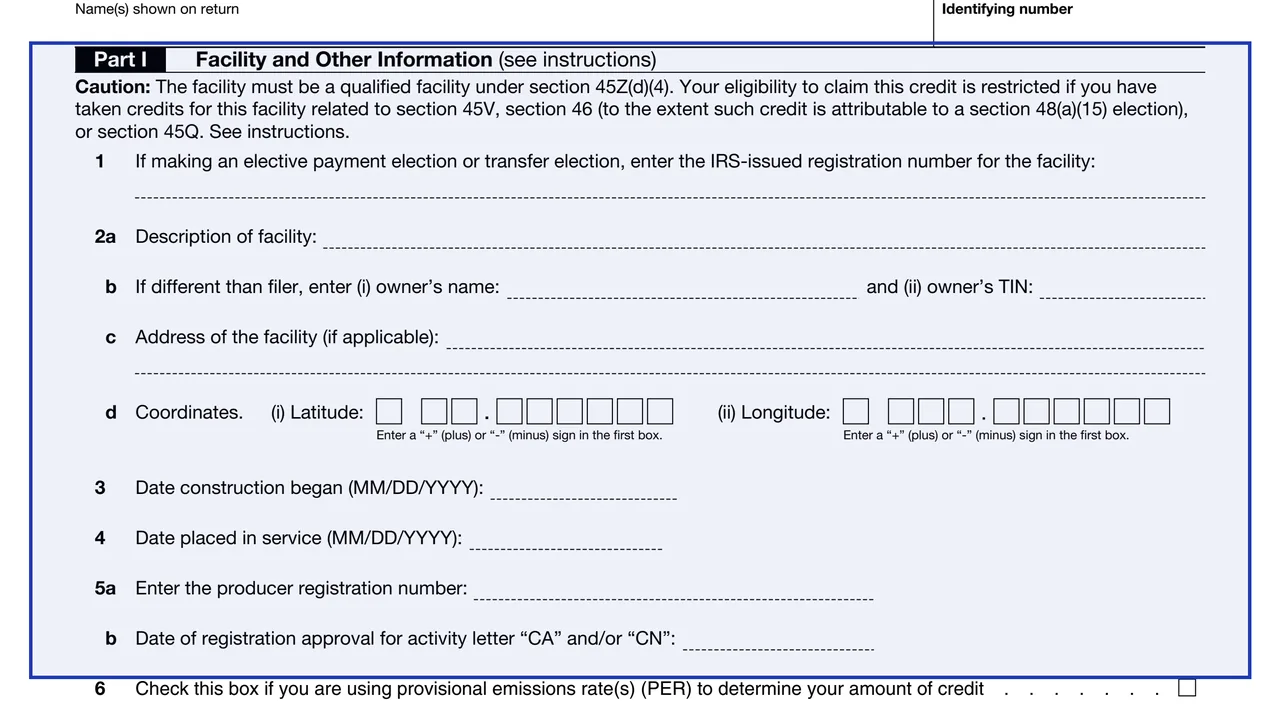
Part I, lines 1 and 2: the facility

The IRS-issued registration number for an elective payment or transfer election, a description of the facility, the owner's name and TIN if different from the filer, the facility address and its latitude and longitude.
Lines 3 to 5b: dates and registration

The date construction began and the date placed in service, both as MM/DD/YYYY, the producer registration number, and the date of registration approval for activity letter CA and/or CN.

Lines 6 and 7: PER and wage rules

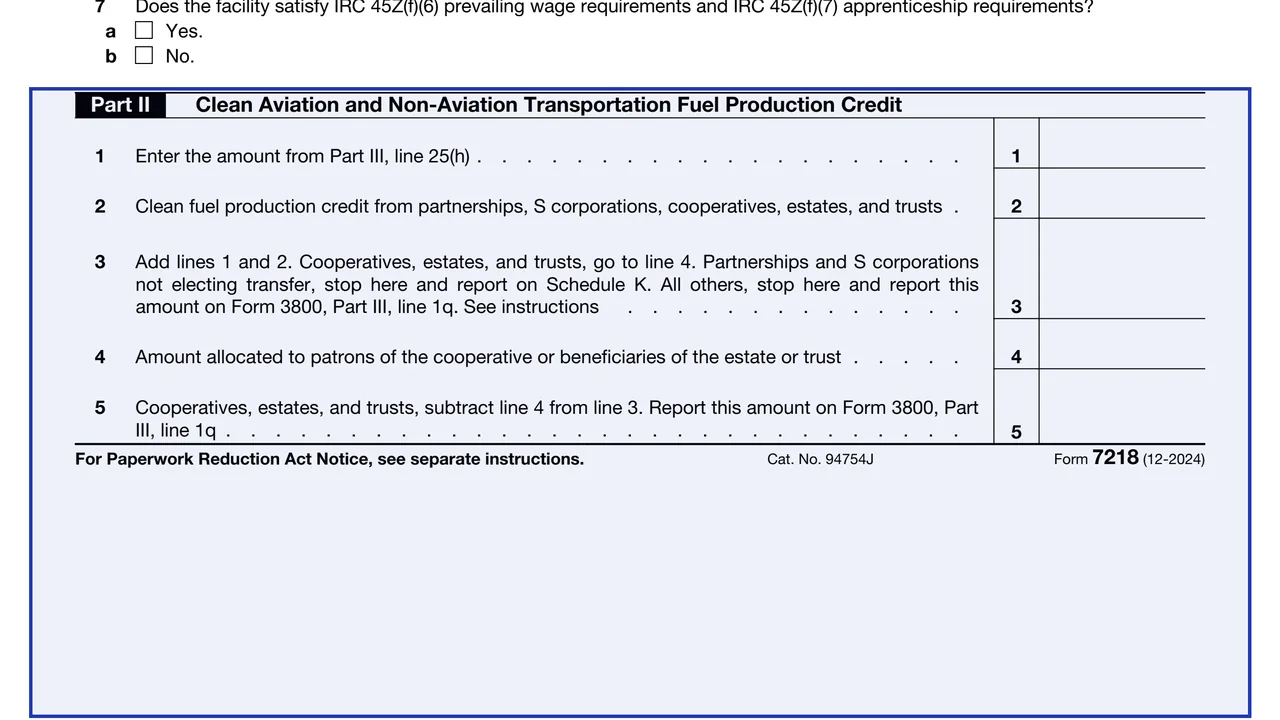
A box for using provisional emissions rate(s) (PER), and Yes or No on whether the facility satisfies the section 45Z(f)(6) prevailing wage and section 45Z(f)(7) apprenticeship requirements.

Part II: the credit

Line 1 carries the Part III total, line 2 adds credits from partnerships, S corporations, cooperatives, estates and trusts, and lines 3 to 5 route the result to Schedule K or to Form 3800, Part III, line 1q.

Part III: fuel produced and sold after 2024

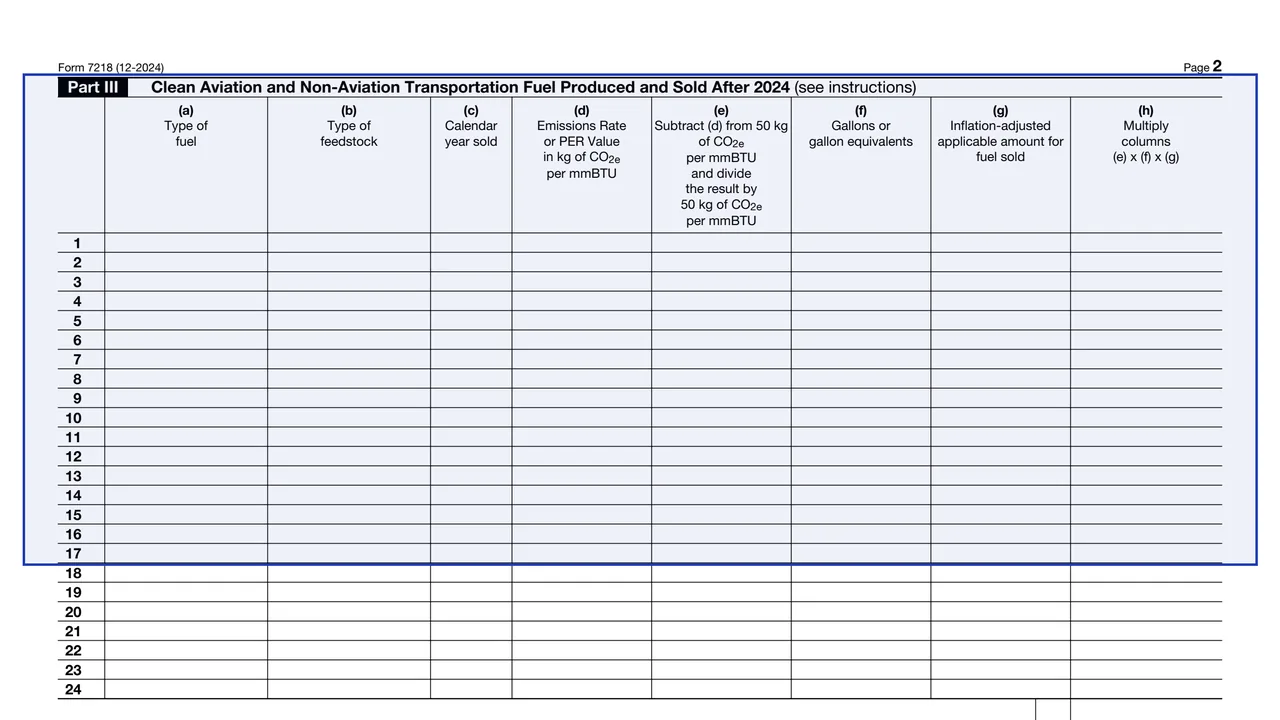
24 lines with columns (a) to (h): type of fuel, type of feedstock, calendar year sold, emissions rate or PER value, the emissions factor, gallons or gallon equivalents, the inflation-adjusted applicable amount, and (e) x (f) x (g). Line 25 totals column (h).

How to fill out Form 7218

  1. 1

    Part I, lines 1 to 2d

    Enter the registration number on line 1 only when making an elective payment or transfer election. Describe the facility, add the owner's name and TIN if different from the filer, and enter the address and coordinates. The form says to enter a plus or minus sign in the first box of each coordinate.

  2. 2

    Lines 3 to 5b

    Enter the date construction began and the date the facility was originally placed in service. The instructions say line 4 is needed to determine the credit amount based on PWA requirements. Enter the producer registration number and the date of the CN (non-SAF) or CA (SAF) registration letter.

  3. 3

    Lines 6 and 7

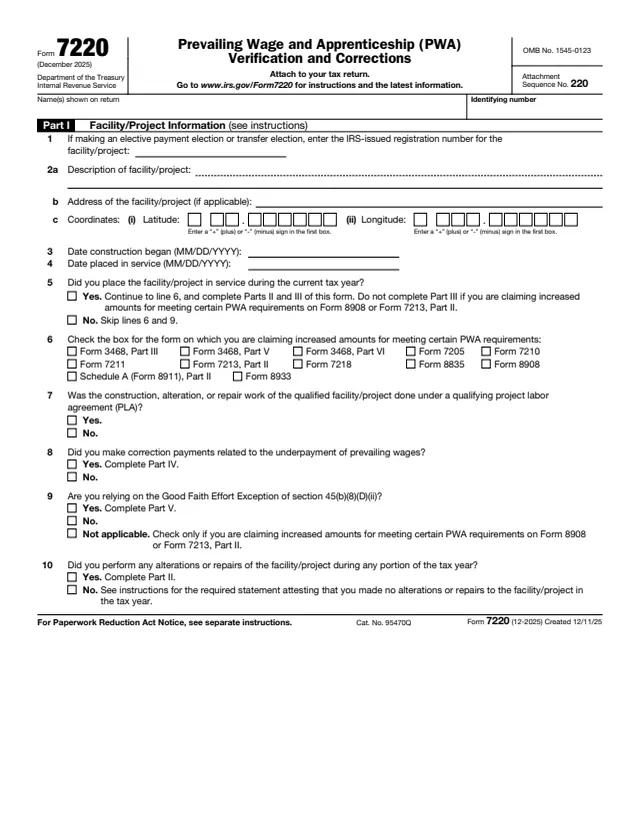
    Check line 6 if using a PER. Check Yes on line 7 if the prevailing wage and apprenticeship requirements are satisfied. The instructions say a filer using an increased applicable amount also files Form 7220 for each qualified facility.

  4. 4

    Part III, columns (a) to (d)

    Enter the type of fuel and whether it is non-SAF or SAF, the type of feedstock, the four-digit calendar year sold, and the emissions rate or PER value in kilograms of CO2e per mmBTU.

  5. 5

    Part III, columns (e) to (h)

    Subtract the rate from 50 kg of CO2e, divide by 50 kg of CO2e and round to the nearest multiple of 0.1. Enter the gallons or gallon equivalents sold and the inflation-adjusted applicable amount, multiply (e) x (f) x (g), and add column (h) on line 25.

  6. 6

    Part II

    Enter the line 25 total on line 1, add any passed-through credits on line 2 and total them on line 3. Cooperatives, estates and trusts continue to lines 4 and 5. Other filers follow the line 3 directions to Schedule K or Form 3800, Part III, line 1q.

Why fill Form 7218 on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

How it is filed and what goes with it

Attach to the return

The form says to attach it to the tax return. The instructions say to file a separate Form 7218 for each qualified facility for which the section 45Z credit is claimed.

Where the credit goes

Line 3, or line 5 for cooperatives, estates and trusts, is reported on Form 3800, Part III, line 1q. Partnerships and S corporations not electing transfer report on Schedule K.

Pre-filing registration

The instructions say a pre-filing registration is completed for each qualified facility before the return is filed when an elective payment election or transfer election is made on Form 3800.

Form 7220 for increased amounts

A filer claiming the increased credit amount for meeting the prevailing wage and apprenticeship requirements files a separate Form 7220 for each qualified facility, according to the instructions.

Applicable amounts

For fuel produced and sold in 2025, the instructions give base amounts from $0.20 to $1.75 per gallon before inflation and inflation-adjusted amounts from $0.21 to $1.86. For fuel produced after 2025, the base amount is $0.20 or $1.00.

Termination date

The instructions say Public Law 119-21 changed the termination date for the section 45Z credit from December 31, 2027 to December 31, 2029.

Who files Form 7218?

  • Registered clean fuel producers

    The instructions say the taxpayer is registered as a producer of clean fuel under section 4101 at the time of production. Line 5a holds the producer registration number.

  • Partnerships and S corporations

    They enter passed-through credits on line 2. Line 3 says partnerships and S corporations not electing transfer stop there and report on Schedule K instead of Form 3800.

  • Cooperatives, estates and trusts

    Line 4 holds the amount allocated to patrons of the cooperative or beneficiaries of the estate or trust. Line 5 is the amount kept, reported on Form 3800, Part III, line 1q.

  • Tax-exempt and governmental entities

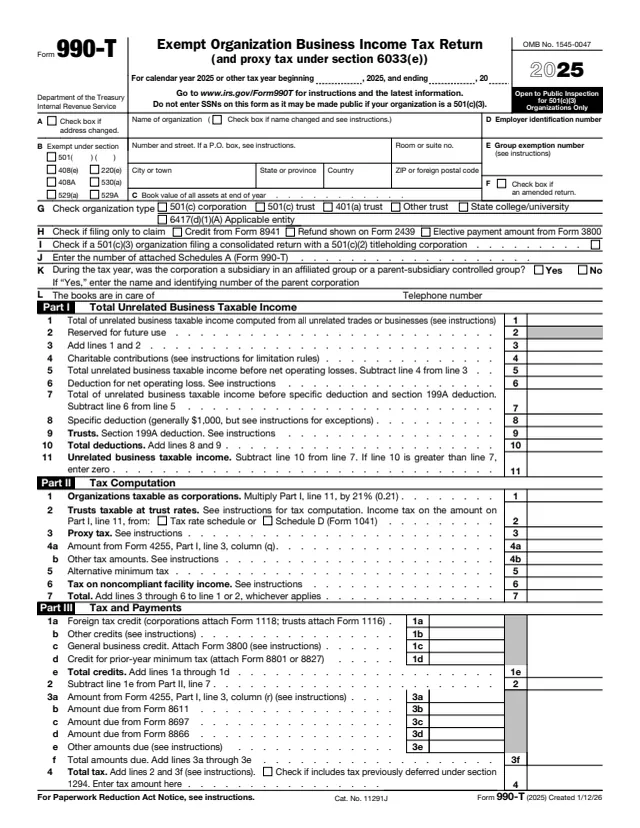
    Applicable entities can elect to treat the credit as a payment of income tax. The instructions say they file Form 7218, Form 3800, and Form 990-T or another applicable income tax return.

  • Partners and shareholders with passed-through credits

    Credits from Schedules K-1 and Form 1099-PATR go on a separate Form 7218 with "Credits from Pass-Through Entities" on line 2a. A filer whose only credit is passed through can report it directly on Form 3800.

  • Specified foreign and foreign-influenced entities

    The instructions say specified foreign entities can't claim this credit for tax years beginning after July 4, 2025, and foreign-influenced entities can't claim it for tax years beginning after July 4, 2027.

The instructions say the clean fuel must be transportation fuel produced in the United States (including U.S. territories) by the taxpayer at a qualified facility after 2024, and sold by the taxpayer to an unrelated person during the tax year.

Official sources and the blank

Do it all with indox

View all 99 tools

Questions about Form 7218

Does each facility need its own Form 7218?

Yes. The instructions say to file a separate Form 7218 for each qualified facility for which the section 45Z credit is claimed, with Part I for that facility.

How is the emissions factor figured?

The instructions say to subtract the emissions rate or PER from 50 kilograms of CO2e per mmBTU, divide the result by 50 kilograms of CO2e, and round to the nearest multiple of 0.1 for column (e).

What is a PER?

A provisional emissions rate. The instructions say a producer of a fuel with no established emissions rate may request an emissions value from the Department of Energy and use it to petition the Secretary of the Treasury for a PER.

Can the credit be transferred?

The instructions say eligible taxpayers can elect under section 6418 to transfer all or part of the credit to an unrelated third party in exchange for cash. Applicable entities are not eligible taxpayers for this.

What about fuel produced before registration?

The instructions say no credit can be claimed for fuel produced and sold before the date of the registration letter, even if all other section 45Z requirements were met before that date.

Are there feedstock limits?

The instructions say all fuel produced after 2025 must be exclusively derived from a feedstock produced or grown in the United States, Mexico, or Canada.