Taxpayer details
An In reply refer to box, a Taxpayer ID number box, the taxpayer names and the address with street, city, state and ZIP code.
907
Agreement to Extend the Time to Bring Suit
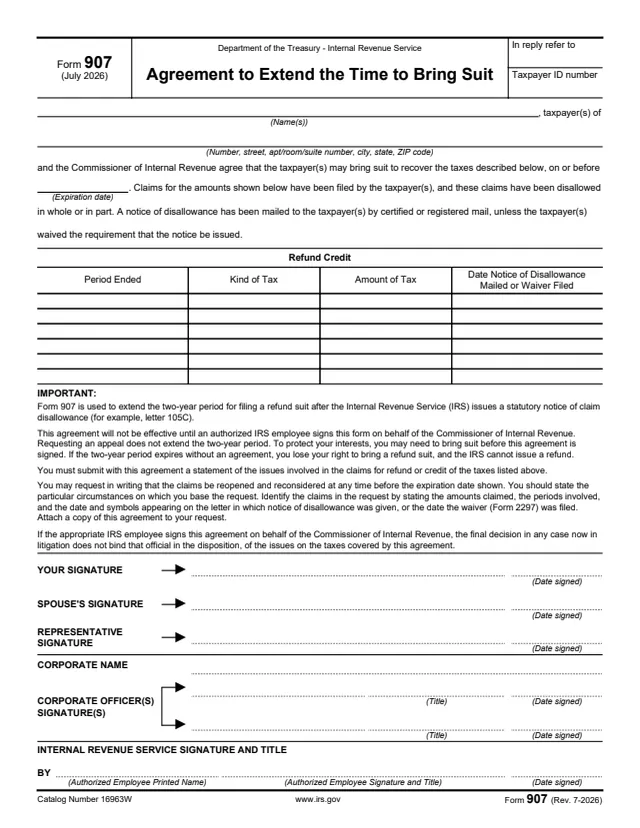
Form 907, Agreement to Extend the Time to Bring Suit, is an agreement between taxpayers and the Commissioner of Internal Revenue. The form says the taxpayers may bring suit to recover the taxes it lists on or before an expiration date written on the form.
The form says it is used to extend the two-year period for filing a refund suit after the IRS issues a statutory notice of claim disallowance, for example letter 105C. The claims it lists have already been filed and disallowed in whole or in part. The form also says the agreement is not effective until an authorized IRS employee signs it on behalf of the Commissioner, and that requesting an appeal does not extend the two-year period.
The taxpayers, a spouse, a representative or corporate officers sign, and an IRS employee with delegated authority signs for the IRS. You can fill out Form 907 free in your browser on this page and download it without an account.
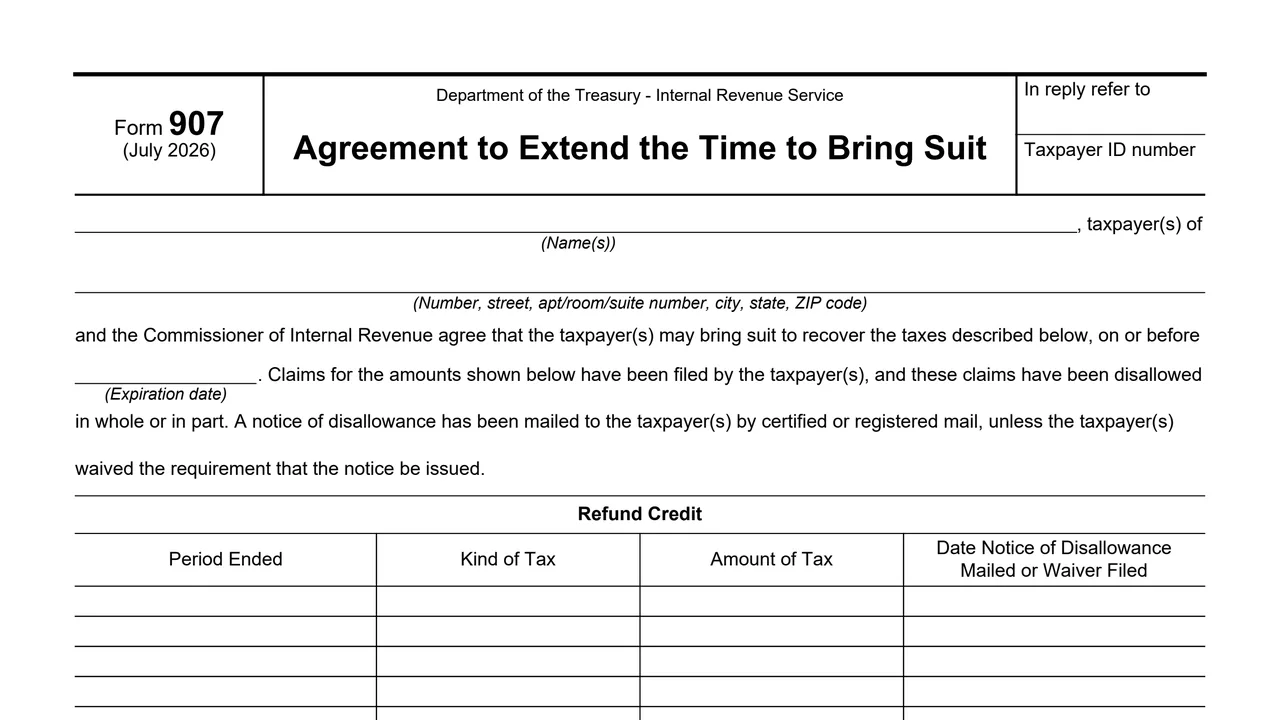
An In reply refer to box, a Taxpayer ID number box, the taxpayer names and the address with street, city, state and ZIP code.
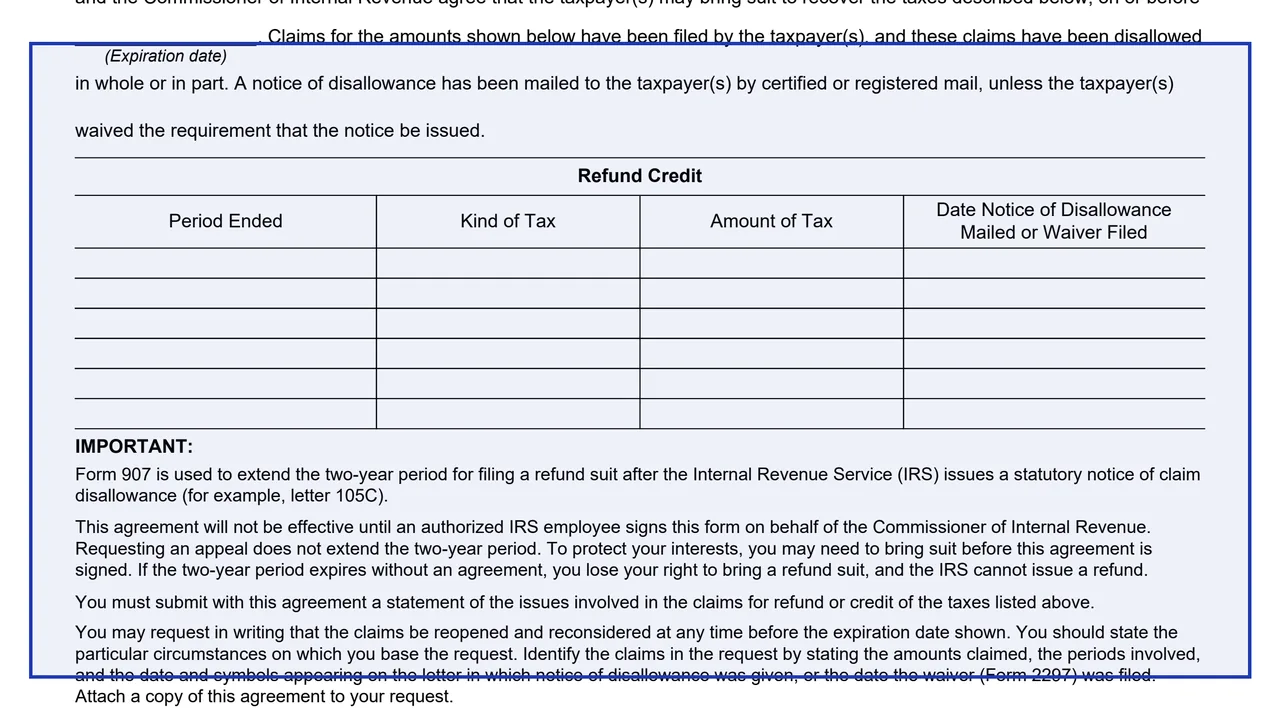
The date on or before which the taxpayers may bring suit to recover the taxes listed below it.
Columns for Period Ended, Kind of Tax, Amount of Tax for refund or credit, and Date Notice of Disallowance Mailed or Waiver Filed.
Printed notes on the two-year period, the effect of an appeal, the statement of issues, reopening the claims and cases in litigation.
Lines for your signature, your spouse's signature, a representative's signature, the corporate name and up to two corporate officers with titles, each dated.
The authorized employee's printed name, signature and title, and the date signed.
Enter the taxpayer names and address, the taxpayer ID number and any reference from the IRS letter in the In reply refer to box.
Enter the date that ends the period to bring suit under the agreement.
For each claim, enter the period ended, the kind of tax, the amount of tax as a refund or credit, and the date the notice of disallowance was mailed or the waiver was filed.
The form says a statement of the issues involved in the claims for refund or credit of the listed taxes is submitted with the agreement.
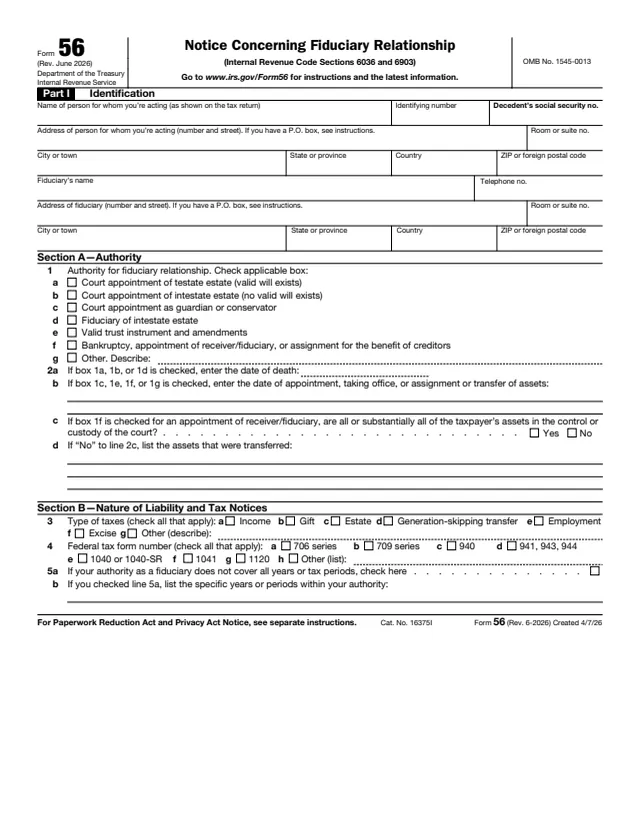
Sign and date with signatures that match the names on the form. Attach a power of attorney not previously filed, or Form 56 for a fiduciary, as the instructions describe.
An IRS employee with delegated authority completes their name and title, then signs and dates the form. The agreement takes effect only then.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says the agreement is not effective until an authorized IRS employee signs it on behalf of the Commissioner of Internal Revenue.
The form says requesting an appeal does not extend the two-year period, and that if the period expires without an agreement, the right to bring a refund suit is lost and the IRS cannot issue a refund.
The form says: "To protect your interests, you may need to bring suit before this agreement is signed."
A written request to reopen and reconsider the claims may be made any time before the expiration date. It identifies the claims by amount, period and the notice letter or Form 2297 waiver date, with a copy of this agreement attached.
The form says that once the IRS employee signs, a final decision in any case now in litigation does not bind that official on the issues for the taxes covered.
The form prints no mailing address. It carries an In reply refer to box for the reference on the IRS correspondence.
The agreement is between the taxpayers named on it and the Commissioner of Internal Revenue. The second page holds instructions for both sides.
No tool matches that search.
The form says it extends the two-year period for filing a refund suit after the IRS issues a statutory notice of claim disallowance, such as letter 105C.
Only after an authorized IRS employee signs it on behalf of the Commissioner of Internal Revenue, according to the form.
No. The form says requesting an appeal does not extend the two-year period.
The form says a statement of the issues involved in the claims is submitted with it. The instructions add a power of attorney not previously filed, and Form 56 for a fiduciary who has not filed one.
The instructions say the corporate name is entered, followed by the signature and title of the officers authorized to sign.
The form says a written request to reopen and reconsider the claims may be made any time before the expiration date, stating the circumstances and attaching a copy of the agreement.