Top of the form
The reporting period beginning and ending dates, a box for an amended report, and the number of Schedules A (Form 8975) attached.
8975
Country-by-Country Report
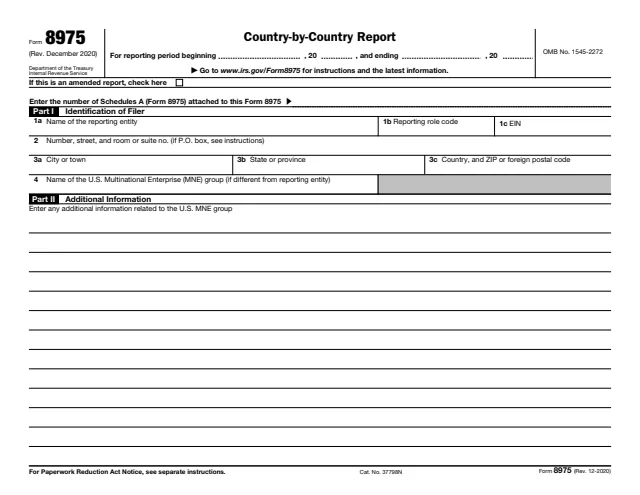
Form 8975 is the IRS country-by-country report. The instructions say Form 8975 and its Schedules A (Form 8975) are used to report certain information about a U.S. multinational enterprise (U.S. MNE) group on a country-by-country basis each year.
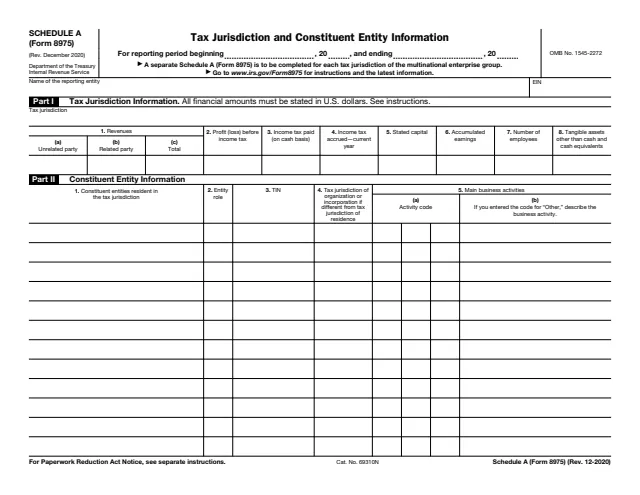
The IRS says annual country-by-country reporting is required by certain U.S. persons that are the ultimate parent entity of a U.S. MNE group with annual revenue for the preceding reporting period of $850,000,000 or more. Form 8975 itself identifies the filer and the group. The constituent entities and the financial and employee information for each tax jurisdiction go on the attached Schedules A (Form 8975).
The instructions say the form is filed with the IRS together with the ultimate parent entity's income tax return, not separately. You can fill out the form free in your browser on this page and download the result without an account.
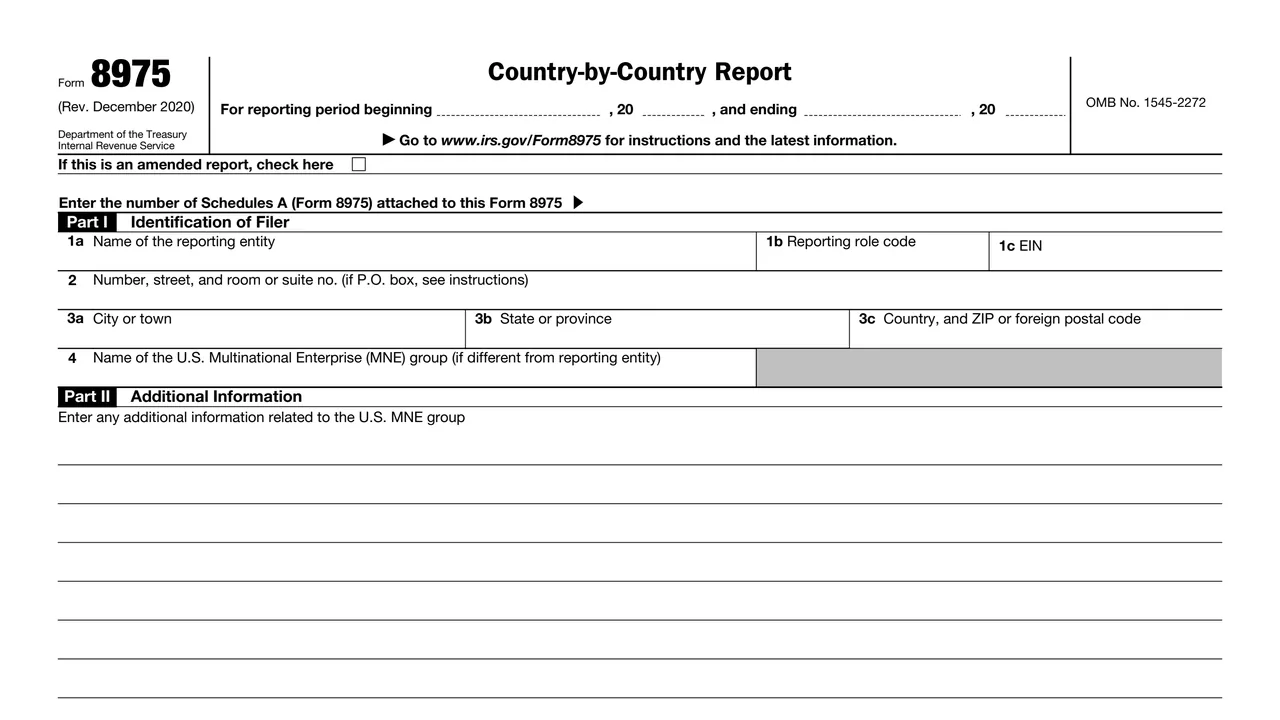
The reporting period beginning and ending dates, a box for an amended report, and the number of Schedules A (Form 8975) attached.
Line 1a is the name of the reporting entity, line 1b the reporting role code and line 1c the EIN.
The street address, city, state or province, country and ZIP or foreign postal code, and the name of the U.S. MNE group if different from the reporting entity.
Free text space on pages 1 and 2 for any additional information related to the U.S. MNE group. The instructions say completing Part II is optional.
Enter the reporting period, check the amended box if it applies, and enter the number of Schedules A attached. The instructions say at least one Schedule A is attached for each tax jurisdiction, including the United States.
Enter the reporting entity's complete legal name and its employer identification number.
The instructions say to enter ULT when filing as the ultimate parent entity, or SUR when designated by a U.S. territory ultimate parent entity.
Enter the legal address with any suite or room number. The instructions say to show a P.O. box only if the post office does not deliver to the street address, and not to abbreviate a foreign country name.
Enter the group's common name on line 4 if it is significantly different from line 1a. Part II can hold a description of the group's operations, with amounts in U.S. dollars.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say Form 8975 and its Schedules A are attached to the income tax return and filed with the IRS by the due date, including extensions, for that return.
The instructions say filers of Forms 1120, 1065, 1120-S, 990-T or 1041 electronically attach Form 8975 and Schedules A electronically in the correct format, not as a binary attachment.
The instructions say paper filers attach the form to the paper return and also mail a copy of page 1 to Internal Revenue Service, Mailstop 4950, 1973 N. Rulon White Blvd., Ogden, UT 84201.
The instructions say an amended Form 8975 and all Schedules A, including unchanged ones, are filed with an amended tax return, with the amended report box checked.
The instructions say penalties under section 6038(b) may apply for failure to report the information required on the form.
8975 Sch. A
187 fields, 2 pages

1120
481 fields, 6 pages

1065
440 fields, 6 pages

1120-S
390 fields, 5 pages
990-T
128 fields, 2 pages

1041
173 fields, 3 pages
The form is filed by a business entity at the top of a multinational group, attached to its income tax return. It is not a form individuals file.
No tool matches that search.
The instructions say a U.S. person files it if it is the ultimate parent entity of a U.S. MNE group with revenues of $850 million or more in the immediately preceding reporting period.
No. The instructions say not to file Form 8975 and its Schedules A separately from the income tax return. They are attached to that return.
The instructions say a separate Schedule A is filed for each tax jurisdiction where the group has constituent entities resident, with financial and employee information and a list of those entities.
They are the reporting role codes for line 1b. ULT is for the ultimate parent entity, and SUR is for a U.S. business entity designated by a U.S. territory ultimate parent entity.
No. The instructions say the top of the form and Part I are completed, and completing Part II is optional.
The instructions say it is generally the 12-month period of the applicable financial statement that ends with or within the tax year, or the 12 months ending on the last day of the tax year if no such statement is prepared.