Header
Name(s) shown on the return and the identifying number.
8882
Credit for Employer-Provided Childcare Facilities and Services
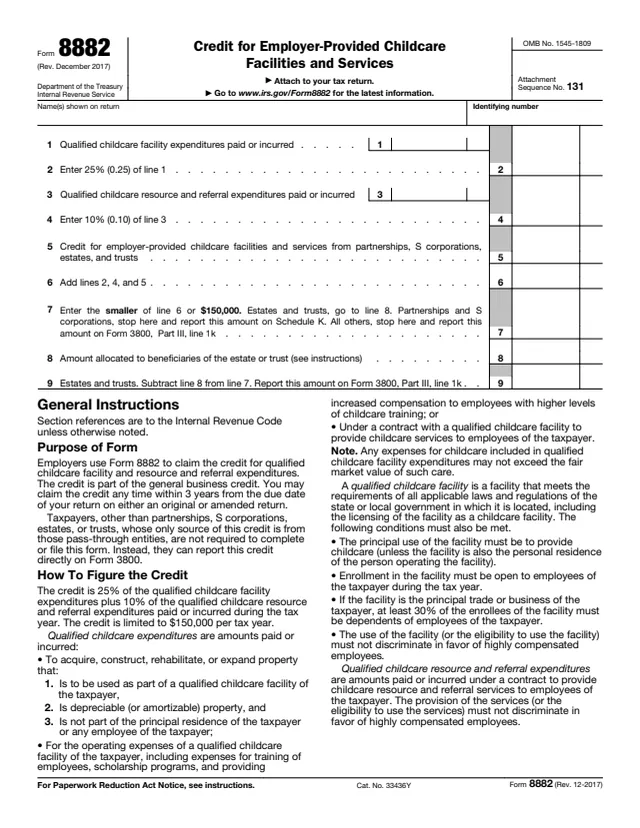
Form 8882 is the IRS form employers use to claim the credit for qualified childcare facility and resource and referral expenditures. The form says the credit is part of the general business credit, and it is attached to the employer's tax return.
The instructions on this revision say the credit is 25% of the qualified childcare facility expenditures plus 10% of the qualified childcare resource and referral expenditures paid or incurred during the tax year, limited to $150,000 per tax year. They also say the credit may be claimed any time within 3 years from the due date of the return, on either an original or amended return.
This page covers the Rev. December 2017 PDF. You can fill it out free in your browser on this page and download it without an account.
Name(s) shown on the return and the identifying number.
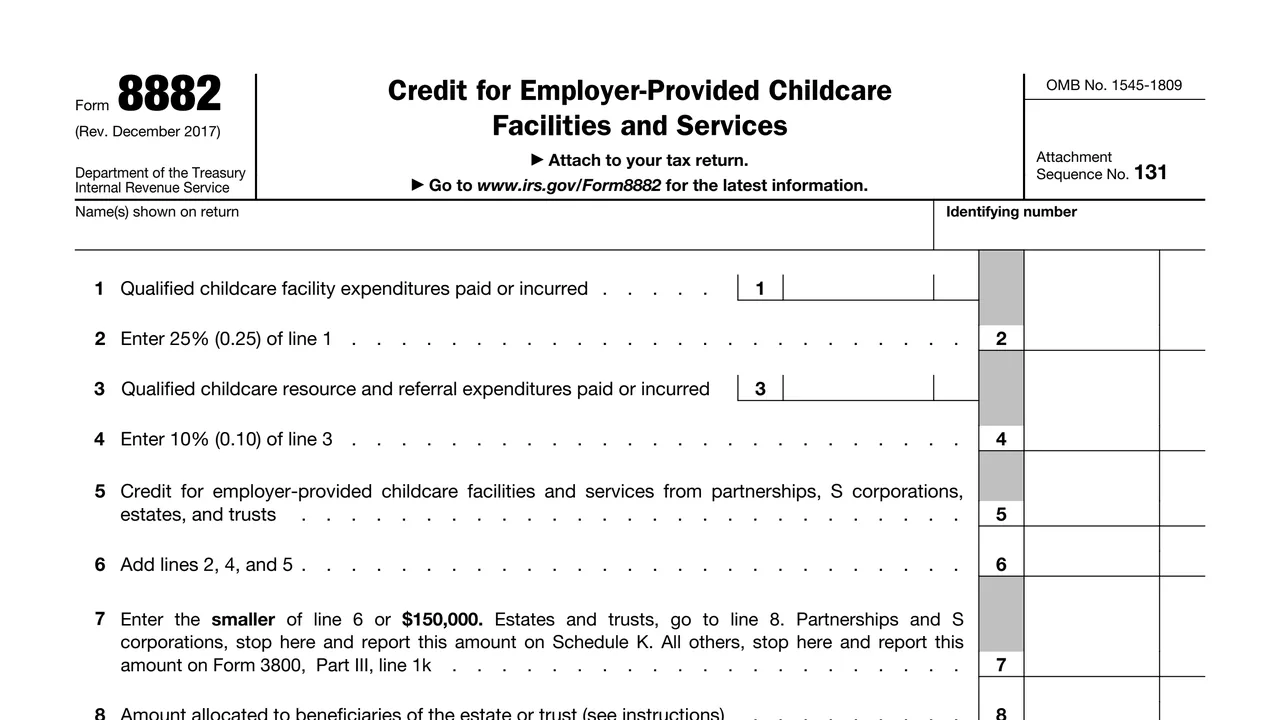
Line 1 is qualified childcare facility expenditures paid or incurred. Line 2 is 25% (0.25) of line 1.
Line 3 is qualified childcare resource and referral expenditures paid or incurred. Line 4 is 10% (0.10) of line 3.
The credit for employer-provided childcare facilities and services received from partnerships, S corporations, estates and trusts.
Line 6 adds lines 2, 4 and 5. Line 7 is the smaller of line 6 or $150,000, with routing to Schedule K or Form 3800, Part III, line 1k.
Line 8 is the amount allocated to beneficiaries. Line 9 subtracts line 8 from line 7 and goes to Form 3800, Part III, line 1k.
Enter qualified childcare facility expenditures on line 1. The instructions describe these as amounts to acquire, construct, rehabilitate or expand qualifying property, operating costs of a qualified facility, or costs under a contract with a qualified childcare facility. Enter 25% of line 1 on line 2.
Enter qualified childcare resource and referral expenditures on line 3. The instructions say these are amounts paid or incurred under a contract to provide childcare resource and referral services to employees. Enter 10% of line 3 on line 4.
The instructions say members of a controlled group or of businesses under common control are treated as a single taxpayer. Each member enters its share on lines 2 and 4, attaches a statement showing how the share was figured and writes "See Attached" next to the entry.
Enter any credit from partnerships, S corporations, estates and trusts on line 5. Add lines 2, 4 and 5 on line 6. On line 7 enter the smaller of line 6 or $150,000, then follow the routing printed on that line.
Enter the beneficiaries' share on line 8, allocated in the same proportion as income. The instructions say an estate or trust subject to the passive activity rules uses Form 8582-CR. Subtract line 8 from line 7 on line 9.
These steps follow the line labels and instructions printed on the Rev. December 2017 form.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to your tax return." The final amount goes to Form 3800, Part III, line 1k, or to Schedule K for partnerships and S corporations.
The instructions say the credit may be claimed any time within 3 years from the due date of the return, on either an original or amended return.
The instructions describe reducing the facility's basis, related deductions and expenditures used for any other credit by the amount of the credit allocable to them.
The instructions say part or all of the credit may be recaptured if, before the 10th tax year after the facility is placed in service, it stops operating as a qualified childcare facility or its ownership changes. See section 45F(d).
This PDF is the Rev. December 2017 edition. The form says to go to www.irs.gov/Form8882 for the latest information.

3800
1,921 fields, 9 pages
8582-CR
52 fields, 2 pages

1065
440 fields, 6 pages

1120-S
390 fields, 5 pages

1041
173 fields, 3 pages
8826
18 fields, 2 pages
The About page says employers use this form. The instructions name the pass-through entities and estates and trusts that report the credit, and say when a taxpayer can skip the form.
No tool matches that search.
The About page says employers use it to claim the credit for qualified childcare facility and resource and referral expenditures.
The Rev. December 2017 instructions say 25% of qualified childcare facility expenditures plus 10% of qualified resource and referral expenditures, limited to $150,000 per tax year.
The form says taxpayers whose only source of this credit is a partnership, S corporation, estate or trust are not required to complete or file it. They can report the credit directly on Form 3800.
No. The form says to attach it to your tax return, and the credit is part of the general business credit on Form 3800.
The instructions say it meets all applicable state or local laws and regulations, including licensing, and list further conditions on principal use, enrollment open to employees and nondiscrimination.
The instructions say part or all of it may be recaptured if, before the 10th tax year after the facility is placed in service, it stops operating as a qualified facility or ownership changes.