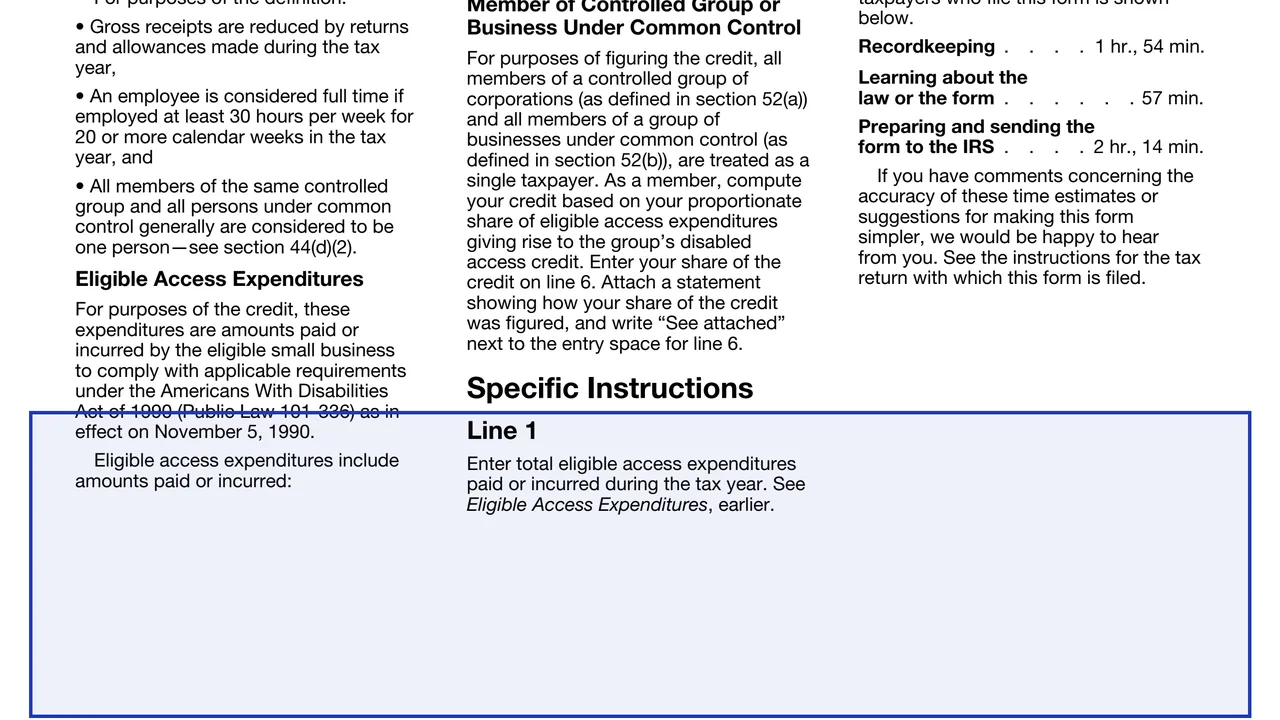
Line 1: total eligible access expenditures
Amounts paid or incurred during the tax year that meet the form's definition of eligible access expenditures.
8826
Disabled Access Credit
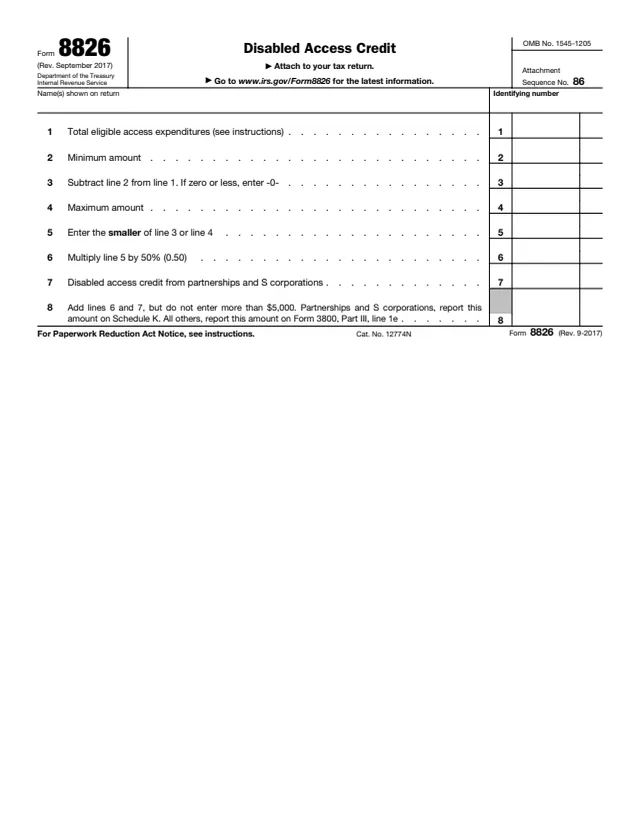
Form 8826, Disabled Access Credit, is used by eligible small businesses to claim the disabled access credit. The IRS says this credit is part of the general business credit.
The form works from total eligible access expenditures. It subtracts a $250 minimum, caps the result at a $10,000 maximum, multiplies it by 50% (0.50), and adds any credit from partnerships and S corporations, with line 8 limited to $5,000. The form says "Attach to your tax return." Its instructions are on page 2 of the same PDF.
This page has the September 2017 revision. You can fill it out free in your browser on this page and download the result without an account.
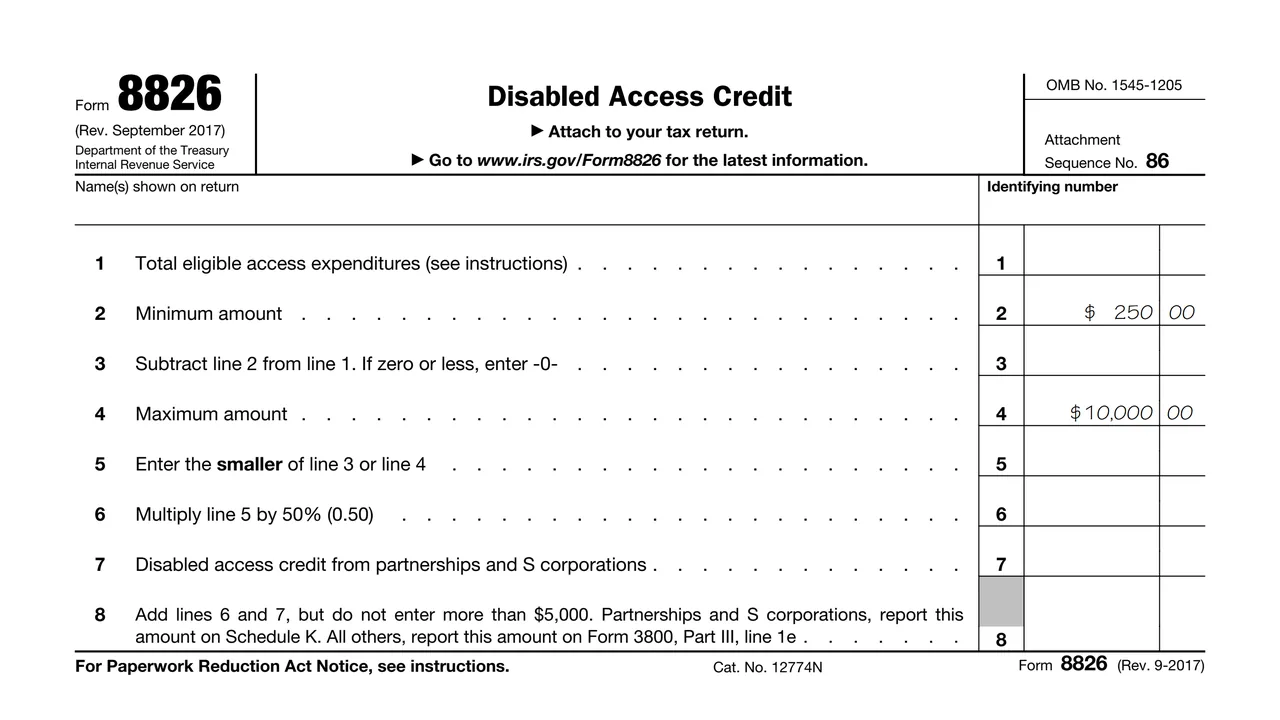
Amounts paid or incurred during the tax year that meet the form's definition of eligible access expenditures.
Line 2 is printed as $250. Line 3 subtracts it from line 1, or is -0- if zero or less.
Line 4 is printed as $10,000. Line 5 is the smaller of line 3 or line 4, and line 6 multiplies line 5 by 50% (0.50).
Line 7 is the disabled access credit from partnerships and S corporations. Line 8 adds lines 6 and 7, but is not more than $5,000.
Page 2 defines an eligible small business, eligible access expenditures and disability. It says expenditures are amounts paid to comply with the Americans With Disabilities Act of 1990 as in effect on November 5, 1990.
Enter total eligible access expenditures paid or incurred during the tax year. The form lists removing barriers, interpreters, readers and taped texts, and acquiring or modifying equipment for individuals with disabilities.
Subtract the $250 on line 2, enter the smaller of line 3 or $10,000 on line 5, and multiply by 50% on line 6.
A member of a controlled group enters its share of the credit on line 6, attaches a statement showing how the share was figured, and writes "See attached" next to line 6.
Enter any credit from partnerships and S corporations on line 7. Add lines 6 and 7 on line 8, up to $5,000, and carry it to Schedule K or Form 3800 as the form directs.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form is attached to the tax return. The About page lists Form 1065, Form 1120-S and Form 3800 as related.
The form says that to the extent of the credit on line 6, the eligible access expenditures may not be deducted, capitalized or used in figuring any other credit.
The form says barrier removal expenses for a facility first placed in service after November 5, 1990, are not eligible expenditures.
The form counts an employee as full time if employed at least 30 hours per week for 20 or more calendar weeks in the tax year.

3800
1,921 fields, 9 pages

1065
440 fields, 6 pages

1120-S
390 fields, 5 pages
8881
29 fields, 1 page
8941
28 fields, 1 page
The form says eligible small businesses use it, and that a business elects the credit by filing Form 8826.
No tool matches that search.
The IRS says eligible small businesses use it to claim the disabled access credit, which is part of the general business credit.
Line 8 says to add lines 6 and 7 but not enter more than $5,000.
A business or person with preceding-year gross receipts that did not exceed $1 million or with no more than 30 full-time employees, that elects the credit by filing Form 8826.
The form says partnerships and S corporations report the line 8 amount on Schedule K, and all others on Form 3800, Part III, line 1e.
The form says that to the extent of the line 6 credit, the expenditures may not be claimed as a deduction, capitalized, or used for any other credit.