Heading
Accounting period, the organization's name, address, EIN and telephone number, a box for a pending exemption application, and the type of organization.
8870
Information Return for Transfers Associated With Certain Personal Benefit Contracts
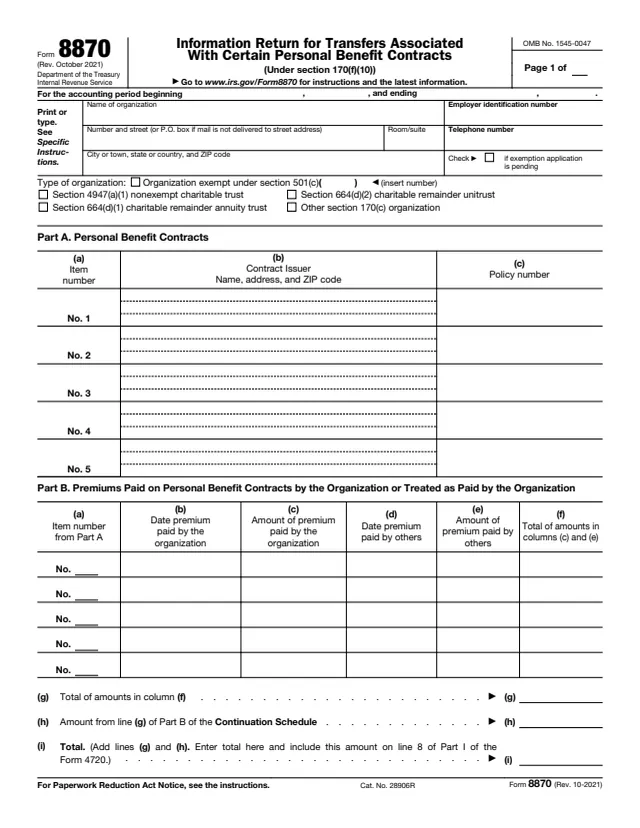
Form 8870 is an information return filed under section 170(f)(10). The IRS About page says charitable organizations described in section 170(c) and charitable remainder trusts described in section 664(d) file it to report premiums paid after February 8, 1999, on certain life insurance, annuity and endowment contracts, called personal benefit contracts.
The instructions explain that a personal benefit contract is one that benefits, directly or indirectly, the transferor, a member of the transferor's family, or another person the transferor designates. The organization lists each contract, the premiums it paid or is treated as paying, each beneficiary and each transferor. The premium total on line (i) carries to Form 4720.
This is an organization's return, not an individual's: an officer or authorized trustee signs it. The form's instructions are printed in the same PDF. You can fill out Form 8870 free in your browser on this page and download it without an account.
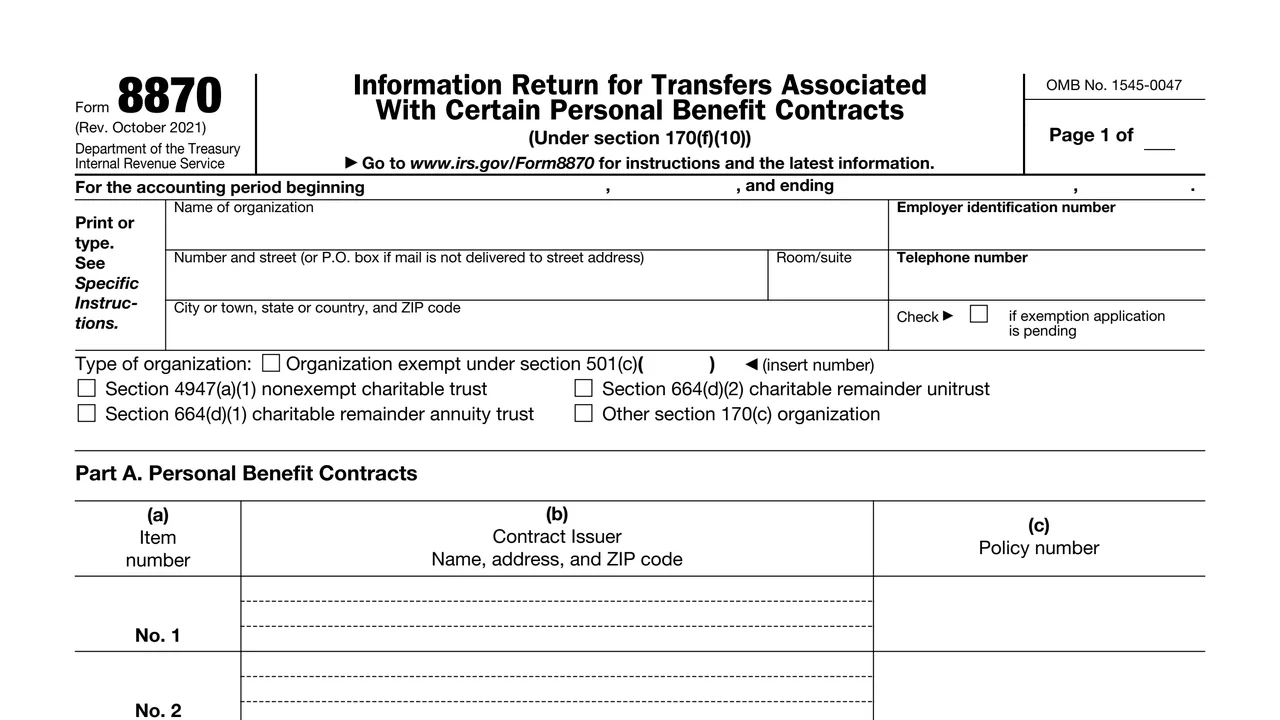
Accounting period, the organization's name, address, EIN and telephone number, a box for a pending exemption application, and the type of organization.
Item number, the contract issuer's name, address and ZIP code, and the policy number for up to five contracts.
Dates and amounts of premiums paid by the organization and by others, a total per contract in column (f), and lines (g) to (i) for the grand total.
For each contract, the beneficiary's name, address and ZIP code and the beneficiary's SSN or EIN.
For each contract, the transferor's name, address and ZIP code, the date the organization received the transfer and the amount.
The officer's signature, the Paid Preparer Use Only area, and a page 3 Continuation Schedule that repeats Parts A to D for more contracts.
Enter the accounting period, which the instructions say should match the Form 990, 990-EZ, 990-PF or 5227. For a section 501(c) organization, insert its number; the instructions say private foundations enter 3.
Number the first contract No. 1, the second No. 2, and so on. Later parts use the same numbers. The instructions say to use the Continuation Schedule for more than five contracts.
Complete Part B for all premiums paid during the tax year. Column (f) is the total of columns (c) and (e). Line (i) adds lines (g) and (h) and is carried to Form 4720, line 8, Part I.
List each beneficiary with an SSN or EIN, and each transferor of funds used as premiums, with the date received and the amount, using the Part A item numbers in order.
Duplicate it as needed. The instructions say to complete line (g) on only one Continuation Schedule, with the combined total, and carry it to Part B, line (h).
An authorized officer signs and dates the return and prints a name and title. For a trust, the authorized trustee signs. The instructions say to make an entry on all applicable lines, including a zero when appropriate.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to send the return to the Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0027.
A charitable organization files by the fifteenth day of the fifth month after the end of the tax year. A charitable remainder trust files by April 15 following the calendar year in which it paid the premiums.
The instructions say an extension can be requested on Form 8868 on or before the due date. Generally no more than 90 days is granted at a time, and never more than 6 months for a domestic organization.
The instructions say section 170(f)(10)(F)(i) imposes an excise tax equal to the premiums paid in certain cases, reported and paid on Form 4720.
A return filed after the due date includes a statement giving the reasons. An amended return gives all the information, not only the changes, with "Amended Return" written at the top.
The instructions say these returns are subject to the penalties for returns required under section 6033. For help, the instructions list 877-829-5500, Monday through Friday.
4720
666 fields, 10 pages
8868
47 fields, 2 pages
990
1,075 fields, 12 pages
990-PF
1,147 fields, 13 pages
5227
411 fields, 7 pages
990-EZ
325 fields, 4 pages
The instructions say section 170(f)(10) requires a charitable organization described in section 170(c) or a charitable remainder trust described in section 664(d) to file it if it paid premiums after February 8, 1999, on personal benefit contracts.
No tool matches that search.
The instructions say it is any life insurance, annuity or endowment contract that benefits, directly or indirectly, the transferor, a member of the transferor's family, or another person the transferor designates, other than a section 170(c) organization.
No. The form is filed by the charitable organization or charitable remainder trust that paid the premiums. Donors appear on it as transferors in Part D.
The instructions say the fifteenth day of the fifth month after the end of the tax year for a charitable organization, and April 15 after the calendar year of the premiums for a charitable remainder trust.
The instructions give the Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0027.
Use the Continuation Schedule on page 3. The instructions say it can be duplicated, with line (g) completed on only one copy.
The instructions say that if there is an understanding or expectation that another person will pay a premium, that payment is treated as made by the organization. Part B has columns for premiums paid by others.