Header
Name(s) shown on return and identifying number. The form is Attachment Sequence No. 213.
7213
Nuclear Power Production Credit
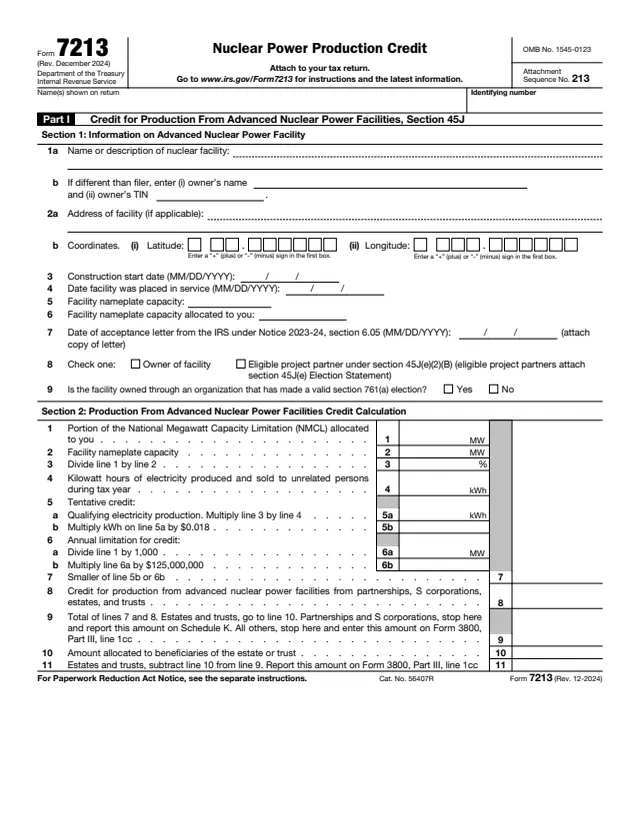
Form 7213 is used for two nuclear power production credits. The IRS About page says Part I is the credit for production from advanced nuclear facilities under section 45J, and Part II is the zero-emission nuclear power production credit under section 45U. The form says "Attach to your tax return."
The instructions say a separate Form 7213 is filed for each advanced nuclear power facility or each qualified nuclear power facility. Part I uses the facility limitation the IRS allocates under Notice 2023-24, and the instructions say a copy of the IRS acceptance letter is attached. The form says to complete Part II only if the facility was placed in service prior to August 16, 2022. Both credits flow to Form 3800, General Business Credit.
This page has the December 2024 revision of the form. The instructions are revised December 2025 and say they are for use with the December 2024 revision of Form 7213. The PDF can be filled out free in the browser on this page and downloaded without an account.
Name(s) shown on return and identifying number. The form is Attachment Sequence No. 213.
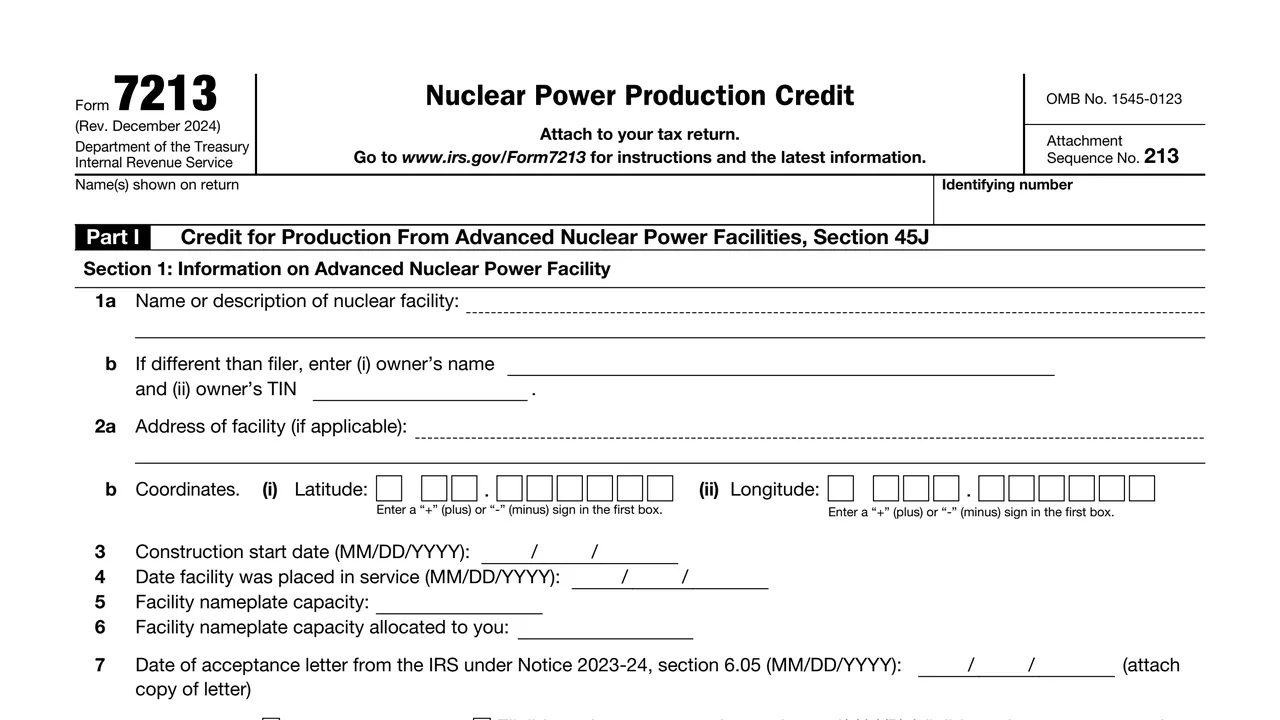
Lines 1a through 9: facility name, owner if different, address and coordinates, construction start date, placed in service date, nameplate capacity and the share allocated to the filer, the IRS acceptance letter date, and a section 761(a) election question.
Lines 1 through 11 divide the allocated National Megawatt Capacity Limitation by nameplate capacity, multiply qualifying kWh by $0.018, and limit the credit to line 1 divided by 1,000 times $125,000,000.
Lines 1 through 4: the IRS-issued registration number when making an elective payment or transfer election, facility name, address and coordinates, and the Nuclear Regulatory Commission permit or license number.
Lines 1 through 15 apply the $0.003 rate to kWh sold, subtract a reduction based on gross receipts, $0.025 per kWh and 16% (0.16), and multiply by 5.0 on line 11 when the prevailing wage requirements are met.
The instructions say to file a separate Form 7213 for each advanced nuclear power facility or qualified nuclear power facility. Enter the name and identifying number shown on the return.
Enter the facility name, or a technical description if it has none, then the address and coordinates. Line 6 is the share of nameplate capacity equal to the filer's ownership share. Line 7 is the acceptance letter date, with a copy attached.
Line 1 is the portion of the facility limitation the IRS allocated to the filer. Line 4 is kWh produced and sold to unrelated persons. Line 8 holds credits from Schedule K-1 (Form 1065), (Form 1120-S) or (Form 1041), as the instructions list.
Line 1 is the pre-filing registration number, if one applies. Enter the facility name or description, the owner if different, the address and coordinates, and on line 4 the permit or license number from the Nuclear Regulatory Commission.
Line 1 is kWh produced and sold to an unrelated person. Line 4 is gross receipts, including zero-emission credit (ZEC) program amounts, and line 5 is the ZEC portion. On line 11 the instructions say to multiply line 10 by 5.0 only if applicable and attach the required information.
Partnerships and S corporations report line 9 or line 13 on Schedule K. Others enter it on Form 3800, Part III, line 1cc for Part I or line 1u for Part II. Estates and trusts first subtract the beneficiaries' share on line 10 or 14.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to your tax return." It has no separate mailing address.
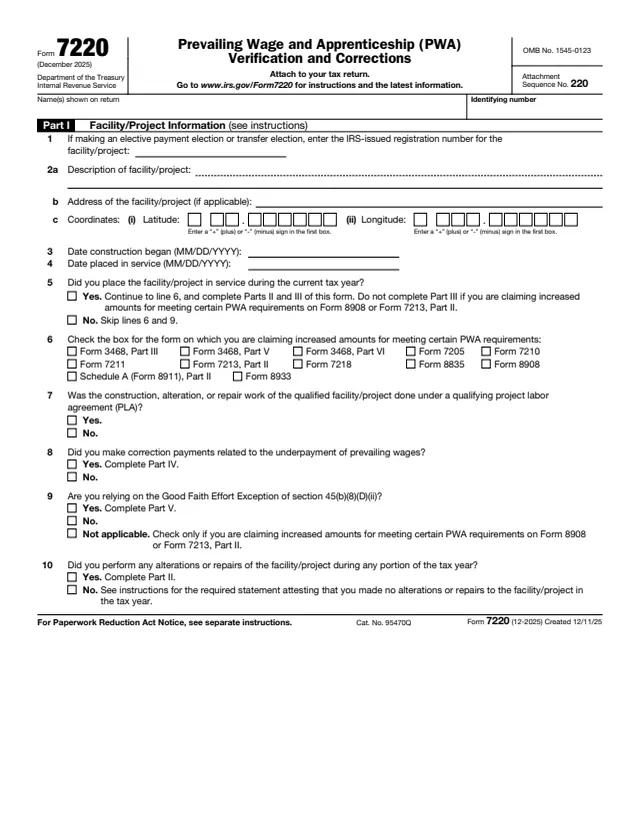
The instructions name a copy of the IRS acceptance letter for Part I, the section 45J(e) Election Statement for an eligible project partner, and Form 7220 when claiming the increased credit amount on Part II, line 11.
The instructions say applicable entities making the elective payment election file Form 7213 with any attachments, Form 3800, and Form 990-T or other applicable income tax return.
The instructions say a pre-filing registration for each facility is completed before filing the return when an elective payment or transfer election is made for the Part II credit. Pub. 5884 describes the registration tool.
The instructions say no zero-emission nuclear power production credit is allowed for tax years beginning after July 4, 2025, for a specified foreign entity, or after July 4, 2027, for a foreign-influenced entity.
The instructions say to use the December 2025 instructions for tax years beginning in 2025 or later, and prior revisions for earlier tax years.

3800
1,921 fields, 9 pages
7220
653 fields, 5 pages
8582-CR
52 fields, 2 pages
990-T
128 fields, 2 pages

1065
440 fields, 6 pages

1120-S
390 fields, 5 pages
The filer is the taxpayer claiming the credit for a facility. The form goes to the IRS attached to the filer's tax return.
No tool matches that search.
Two. Part I is the credit for production from advanced nuclear power facilities under section 45J. Part II is the zero-emission nuclear power production credit under section 45U.
The instructions say a filer whose share comes on a Schedule K-1 does not need to file this form and reports it on Form 3800. An estate or trust that allocates the credit to beneficiaries does file it.
The form says to complete Part II only if the facility was placed in service prior to August 16, 2022. The instructions add that an advanced nuclear power facility under section 45J is not a qualified nuclear power facility under section 45U.
The form says to multiply line 10 by 5.0 if the prevailing wage requirements are met, otherwise enter line 10. The instructions say Forms 7213 and 7220 are both attached to the timely filed return, including extensions.
The About page lists a recent development dated 23-SEP-2026: the section 45U reduction amount rate has been updated by the inflation adjustment. The form itself prints $0.025 on Part II, line 7.
The instructions say eligible taxpayers, partnerships and S corporations can elect to transfer all or part of the Part II credit to an unrelated third party for cash, and a qualified public entity can transfer a section 45J credit to an eligible project partner.