Part I: partnership and tax period
The election statement, then the partnership name, taxpayer identification number, and the tax period beginning and ending dates.
7036
Election under Section 1101(g)(4) of the Bipartisan Budget Act of 2015
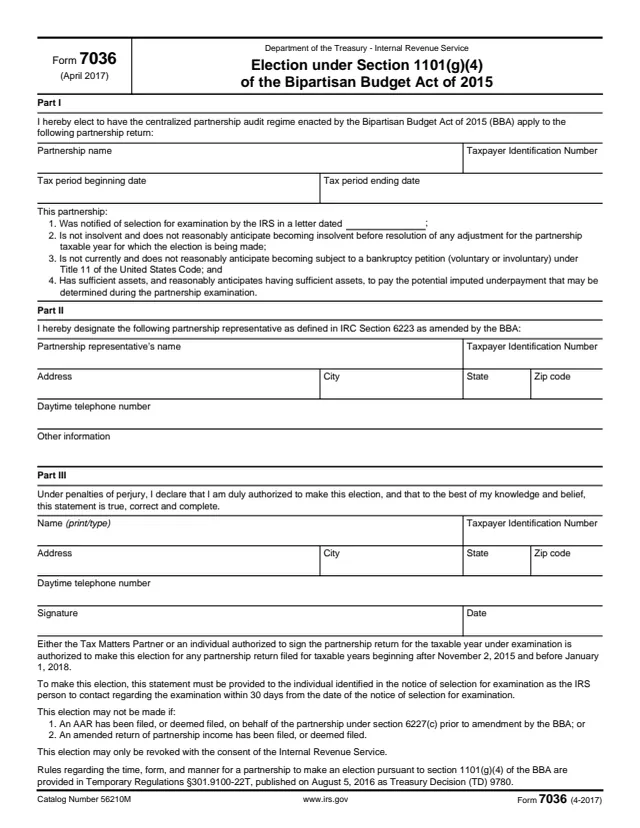
Form 7036 is the statement a partnership uses to elect to have the centralized partnership audit regime enacted by the Bipartisan Budget Act of 2015 (BBA) apply to a partnership return. The form says the election can be made for any partnership return filed for taxable years beginning after November 2, 2015 and before January 1, 2018, by either the Tax Matters Partner or an individual authorized to sign the partnership return for the taxable year under examination.
The one-page form has three parts. Part I identifies the partnership and the tax period and lists four statements about the partnership, starting with the date of the IRS letter selecting it for examination. Part II designates a partnership representative as defined in IRC Section 6223 as amended by the BBA. Part III is the signed declaration. The rules printed at the bottom say the rules for the time, form and manner of the election are in Temporary Regulations §301.9100-22T, published on August 5, 2016 as Treasury Decision (TD) 9780.
You can fill out Form 7036 free in your browser on this page and download it without an account.
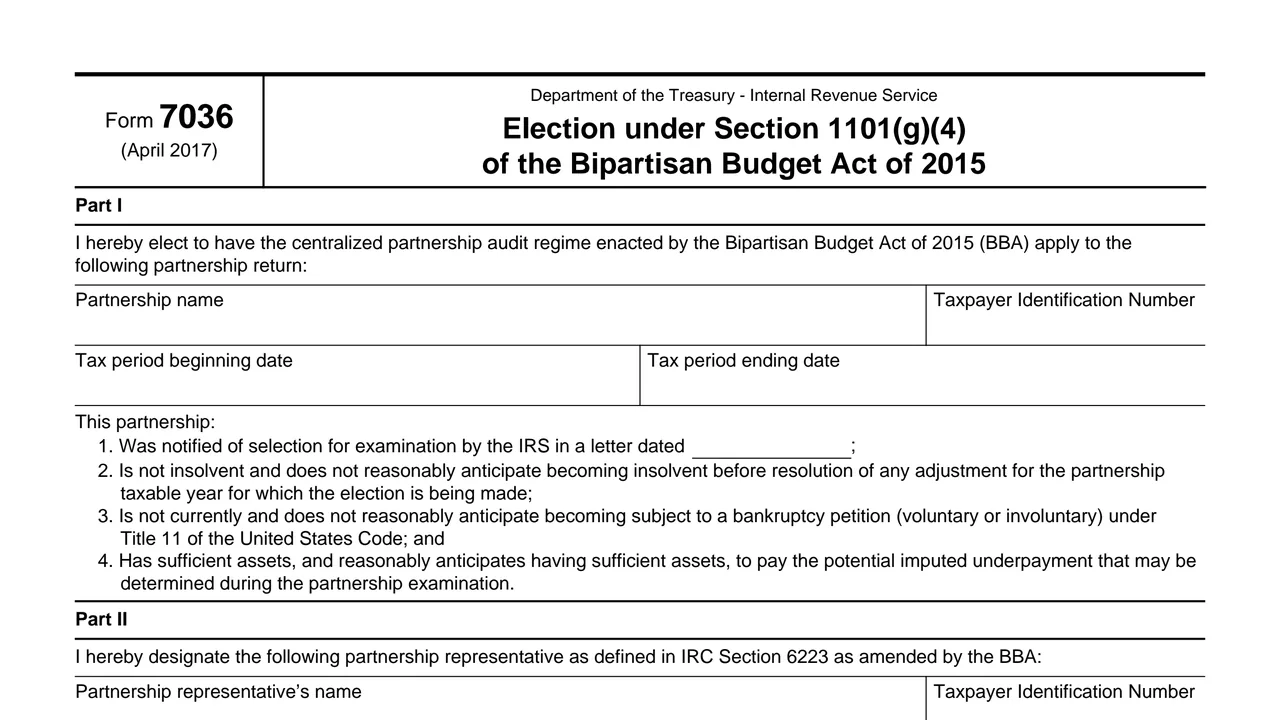
The election statement, then the partnership name, taxpayer identification number, and the tax period beginning and ending dates.
The partnership was notified of selection for examination by a dated letter, is not insolvent, is not subject to a bankruptcy petition under Title 11, and has sufficient assets to pay the potential imputed underpayment.
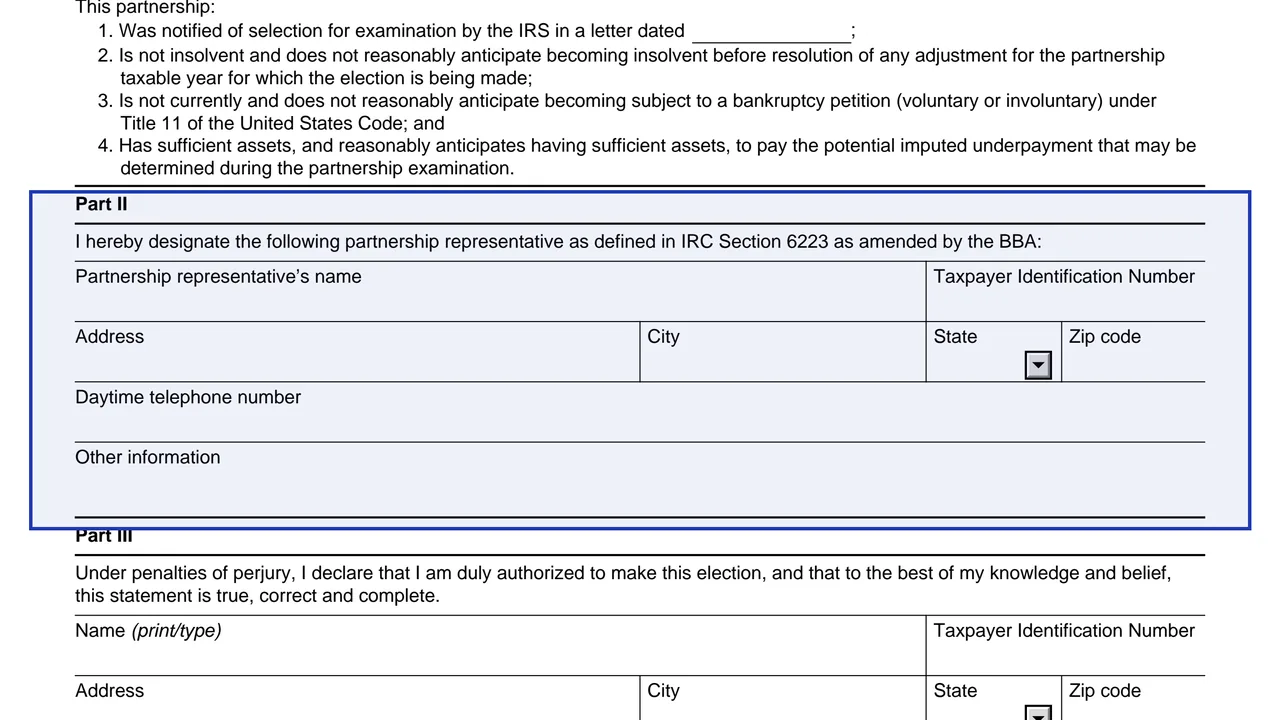
The representative's name, taxpayer identification number, address, city, state, ZIP code, daytime telephone number and other information.
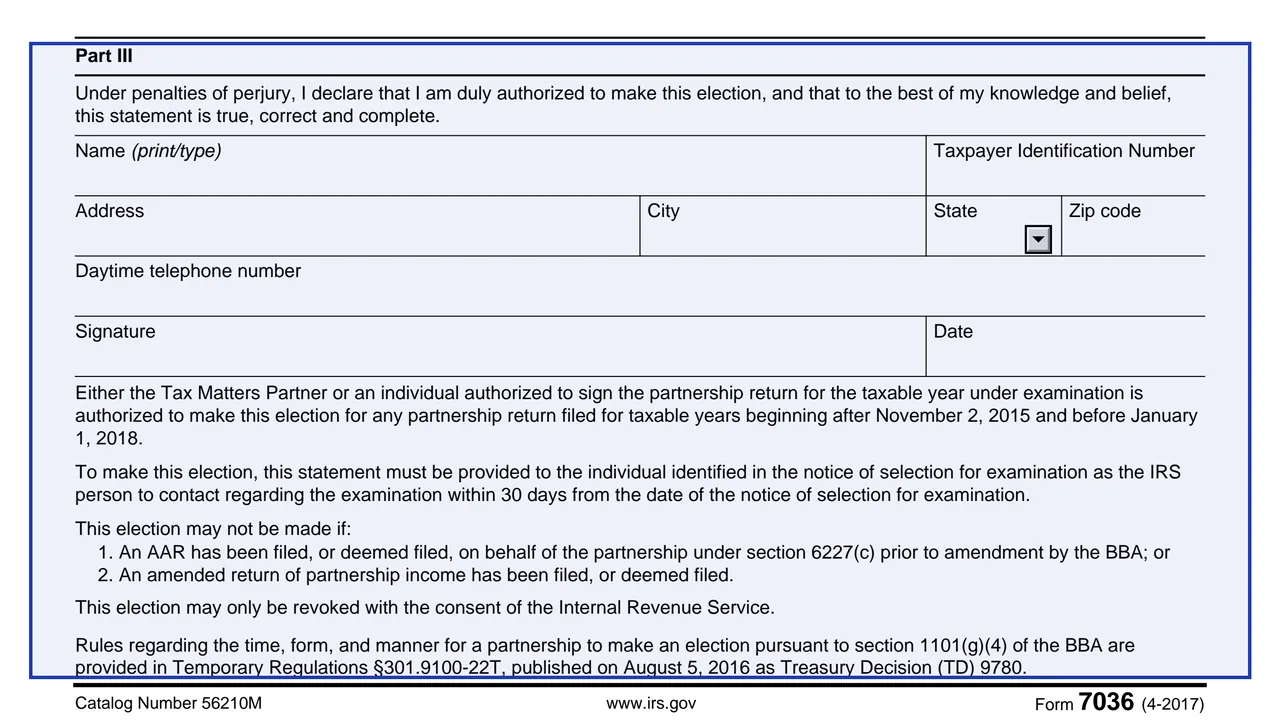
A declaration under penalties of perjury that the signer is duly authorized to make the election, with the signer's name, TIN, address, phone, signature and date.
Who may make the election, the 30-day delivery rule, when the election may not be made, revocation only with IRS consent, and the Temporary Regulations reference.
Enter the partnership name, its taxpayer identification number, and the tax period beginning and ending dates of the return the election covers.
In item 1, enter the date of the IRS letter that notified the partnership of its selection for examination.
Items 2 to 4 state that the partnership is not insolvent, is not and does not expect to be subject to a bankruptcy petition, and has sufficient assets for the potential imputed underpayment.
In Part II, enter the partnership representative's name, taxpayer identification number, address and daytime telephone number, plus any other information.
The Tax Matters Partner or authorized individual enters their name, TIN, address and phone, then signs and dates under penalties of perjury.
The form says to provide the statement to the IRS contact named in the notice of selection for examination within 30 days from the date of that notice.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The individual identified in the notice of selection for examination as the IRS person to contact regarding the examination.
The form says within 30 days from the date of the notice of selection for examination.
Partnership returns filed for taxable years beginning after November 2, 2015 and before January 1, 2018.
The form says not after an AAR has been filed or deemed filed under section 6227(c) prior to amendment by the BBA, or after an amended return of partnership income has been filed or deemed filed.
The form says the election may only be revoked with the consent of the Internal Revenue Service.

1065
440 fields, 6 pages
1065-X
227 fields, 4 pages
8082
59 fields, 2 pages
8979
45 fields, 1 page
1065 Sch. B-2
613 fields, 5 pages
A partnership under IRS examination makes the election, and the statement goes to the IRS contact named in the notice of selection for examination.
No tool matches that search.
It elects to have the centralized partnership audit regime enacted by the Bipartisan Budget Act of 2015 apply to a partnership return that the IRS has selected for examination.
The form says returns filed for taxable years beginning after November 2, 2015 and before January 1, 2018.
The form says either the Tax Matters Partner or an individual authorized to sign the partnership return for the taxable year under examination.
The form says to provide it to the IRS contact named in the notice of selection for examination within 30 days from the date of that notice. No mailing address is printed on the form.
The form says it may only be revoked with the consent of the Internal Revenue Service.
The form points to Temporary Regulations §301.9100-22T, published on August 5, 2016 as Treasury Decision (TD) 9780.