Header
The calendar year or other tax year beginning and ending dates, the corporation's name and its employer identification number.
5735
American Samoa Economic Development Credit
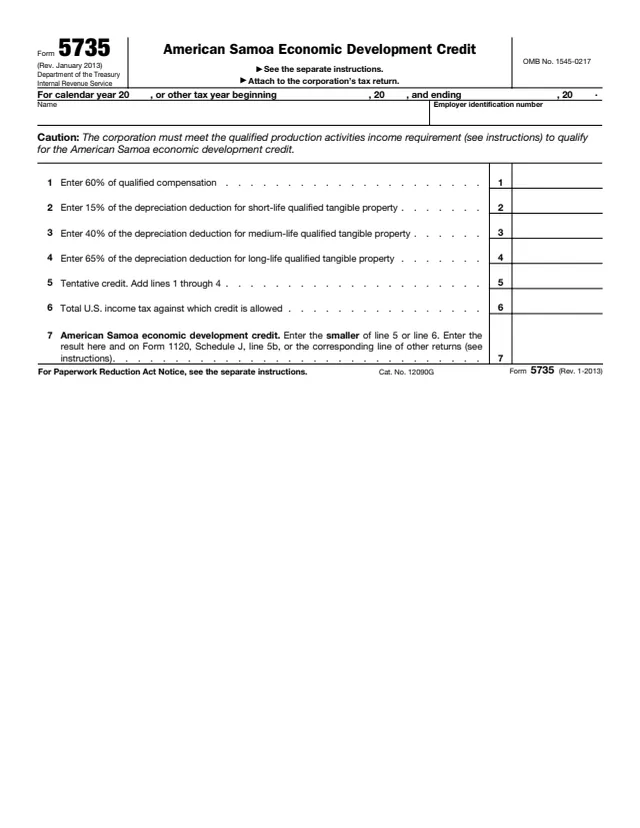
Form 5735 is a one-page corporate form. The IRS says a domestic corporation uses it to figure the American Samoa economic development credit under section 30A. The instructions say the credit is generally allowed against income tax imposed by Chapter 1, with some exceptions, and the form says to attach it to the corporation's tax return.
The form has seven lines. Line 1 takes a percentage of qualified compensation, lines 2 to 4 take percentages of the depreciation deduction for short-life, medium-life and long-life qualified tangible property, and line 7 is the smaller of the tentative credit or the U.S. income tax against which the credit is allowed.
The instructions say this January 2013 revision reflects changes made by section 330 of the American Taxpayer Relief Act of 2012 for tax years beginning after December 31, 2011. You can fill out Form 5735 free in your browser on this page and download the result without an account.
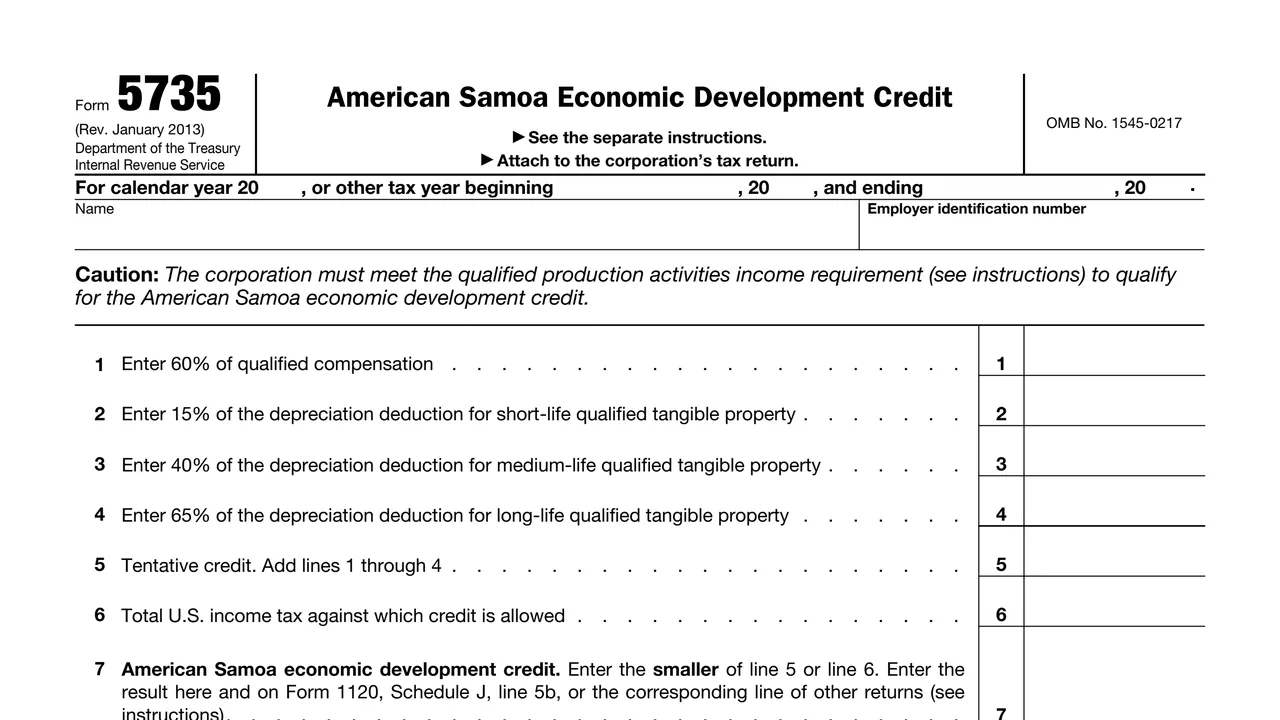
The calendar year or other tax year beginning and ending dates, the corporation's name and its employer identification number.
60% of qualified compensation.
15% of the depreciation deduction for short-life, 40% for medium-life and 65% for long-life qualified tangible property.
Line 5 is the tentative credit, the total of lines 1 through 4. Line 6 is the total U.S. income tax against which the credit is allowed.
The American Samoa economic development credit, the smaller of line 5 or line 6, carried to Form 1120, Schedule J, line 5b, or the corresponding line of other returns.
Enter the calendar year or the other tax year's beginning and ending dates, the corporation's name and its employer identification number.
The instructions say to enter 60% of the sum of qualified wages and allocable employee fringe benefit expenses. Wages per employee are limited to 85% of the OASDI contribution and benefit base, which they give as $110,100 for 2012 and $113,700 for 2013.
The instructions say allocable employee fringe benefit expenses cannot exceed 15% of the corporation's qualified wages for the tax year, and an amount treated as qualified wages may not also count as a fringe benefit expense.
Sort qualified tangible property by its section 168 class. The instructions define short-life as 3-year or 5-year property, medium-life as 7-year or 10-year property, and long-life as everything else.
Add lines 1 through 4 on line 5, enter the U.S. income tax against which the credit is allowed on line 6, and enter the smaller of the two on line 7. The instructions say to write "Form 5735" and the amount next to the entry space on the return.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Form 5735 to the corporation's income tax return and file the return with the Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409.
The instructions say the form is completed for each year the American Samoa economic development credit election is in effect.
The instructions list the accumulated earnings tax, personal holding company tax, the additional tax for recovery of foreign expropriation losses, and recapture of the investment, low-income housing and Indian employment credits.
The instructions say wages or other expenses used for this credit may not be taken into account in determining the research credit under section 41.
The instructions say QPAI is not reported on Form 5735 for tax years beginning in 2012, but corporations should calculate it and keep it for their records to show the IRS they qualify.
The instructions estimate recordkeeping at 7 hr., 53 min., learning about the law or the form at 2 hr., 17 min., and preparing and sending the form at 2 hr., 32 min.

1120
481 fields, 6 pages

3800
1,921 fields, 9 pages
4562
277 fields, 3 pages
4626
813 fields, 8 pages
6478
11 fields, 1 page
8835
97 fields, 3 pages
A corporation completes the form and attaches it to its own income tax return. It is not an individual form.
No tool matches that search.
The instructions say a domestic corporation, other than an S corporation, completes it for each year the American Samoa economic development credit election is in effect.
It is attached to the corporation's income tax return. The instructions give the filing address as Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409.
60% of qualified compensation on line 1, and 15%, 40% and 65% of the depreciation deduction for short-life, medium-life and long-life qualified tangible property on lines 2 to 4.
The form says on Form 1120, Schedule J, line 5b, or the corresponding line of other returns. The instructions add that it goes on the same line as the qualified electric vehicle credit.
The instructions say that for tax years beginning in 2012 it is not reported on Form 5735, but the corporation needs positive QPAI to qualify and should keep its calculation for its records.
The PDF is the January 2013 revision. The instructions point to the March 2007 revision for tax years beginning before January 1, 2012.