Header and parties
The audit control number and taxpayer ID number (TIN), then the name and address of the partnership and the Commissioner of Internal Revenue as the parties.
15057
Agreement to Rescind Notice of Final Partnership Adjustment
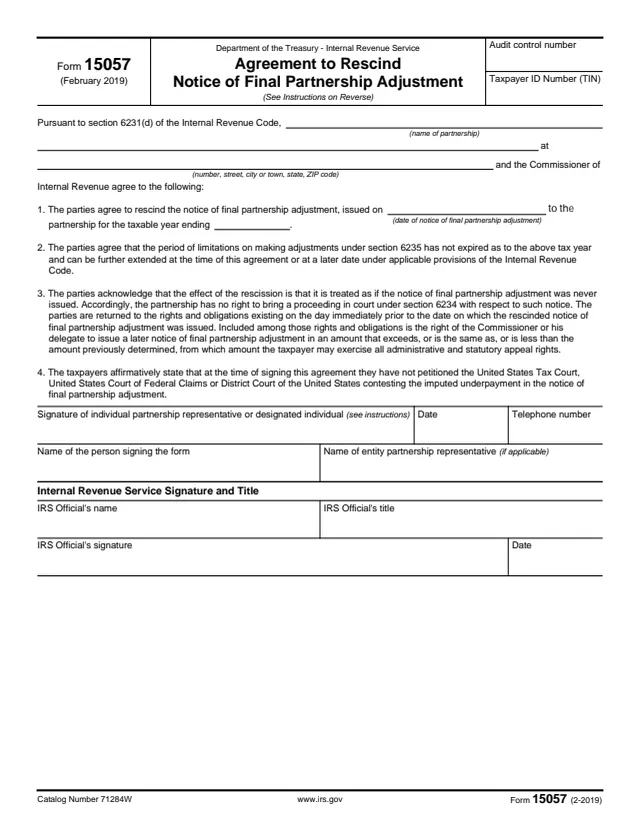
Form 15057 is an agreement between a partnership and the Commissioner of Internal Revenue to rescind a notice of final partnership adjustment. The form says it is made pursuant to section 6231(d) of the Internal Revenue Code.
The form states that the effect of the rescission is that it is treated as if the notice of final partnership adjustment was never issued, and the parties return to the rights and obligations they had the day before that notice was issued. It is signed for the partnership by its partnership representative, or by the designated individual when the representative is an entity, and then by an IRS official.
The instructions are printed on the back of the form. You can fill out the PDF free in your browser on this page and download it without an account.
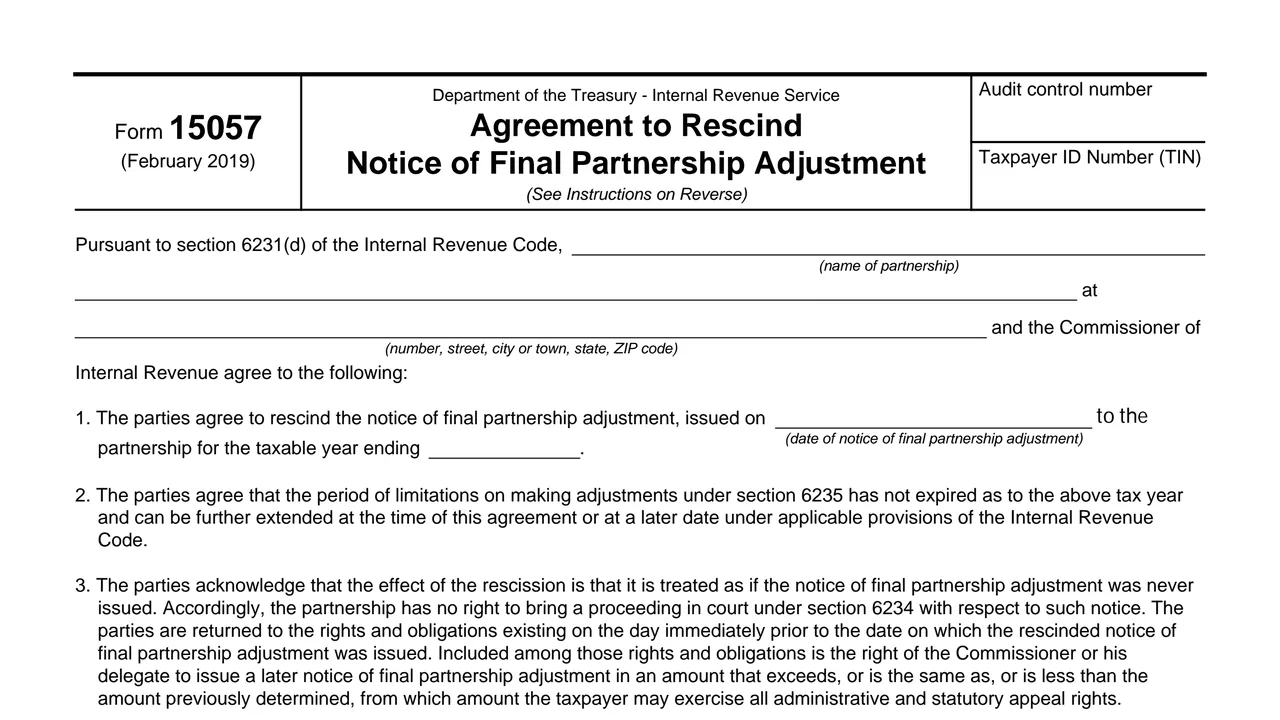
The audit control number and taxpayer ID number (TIN), then the name and address of the partnership and the Commissioner of Internal Revenue as the parties.
The parties agree to rescind the notice of final partnership adjustment issued on a stated date for the taxable year ending on a stated date.
The parties agree that the period of limitations on making adjustments under section 6235 has not expired for the tax year and can be further extended.
The notice is treated as never issued, the partnership has no right to bring a court proceeding under section 6234 for that notice, and the IRS may issue a later notice.
A statement that, at signing, no petition has been filed in the Tax Court, Court of Federal Claims or a District Court contesting the imputed underpayment in the notice.
Signature, date and telephone number of the partnership representative or designated individual, the signer's name, the entity representative's name, and the IRS official's name, title, signature and date.
Enter the audit control number and the partnership's taxpayer ID number (TIN) in the boxes at the top right.
Enter the name and address of the partnership, the date of the notice of final partnership adjustment and the end of the taxable year it covers.
The instructions say an individual partnership representative signs the form and enters their name, the date and a telephone number.
A designated individual signs and enters their name, date and telephone number, plus the name of the entity partnership representative.
The instructions say to submit the completed and signed form with the IRS office, to the attention of the contact person named on the notice of final partnership adjustment.
These steps follow the form and the instructions printed on its reverse.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to submit the signed form with the IRS office, to the attention of the contact person named on the notice of final partnership adjustment.
The instructions say the effective date of the agreement is the date on which the Commissioner or his delegate signs the form.
The form says the Commissioner keeps the right to issue a later notice of final partnership adjustment in an amount that exceeds, is the same as, or is less than the amount previously determined.
The IRS publishes this form as a PDF only, with its instructions on the reverse. No separate instructions document is linked.
8979
45 fields, 1 page

1065
440 fields, 6 pages
8082
59 fields, 2 pages
1065-X
227 fields, 4 pages
The form is an agreement between two parties: the partnership and the Commissioner of Internal Revenue. It is signed for the partnership by its partnership representative and by an IRS official.
No tool matches that search.
It is an agreement between a partnership and the Commissioner of Internal Revenue to rescind a notice of final partnership adjustment, made under section 6231(d).
The partnership representative. If the representative is an entity, the instructions say the designated individual signs and also enters the entity representative's name.
The instructions say on the date the Commissioner or his delegate signs the form.
The form says it is treated as if it was never issued, and the partnership has no right to bring a court proceeding under section 6234 with respect to that notice.
To the IRS office, to the attention of the contact person named on the notice of final partnership adjustment.