Sections 1 to 5: the parties
Taxpayer, applicant, purchaser or new owner, attorney or representative, and lender, finance or settlement company, each with contact details.
14135
Application for Certificate of Discharge of Property from Federal Tax Lien
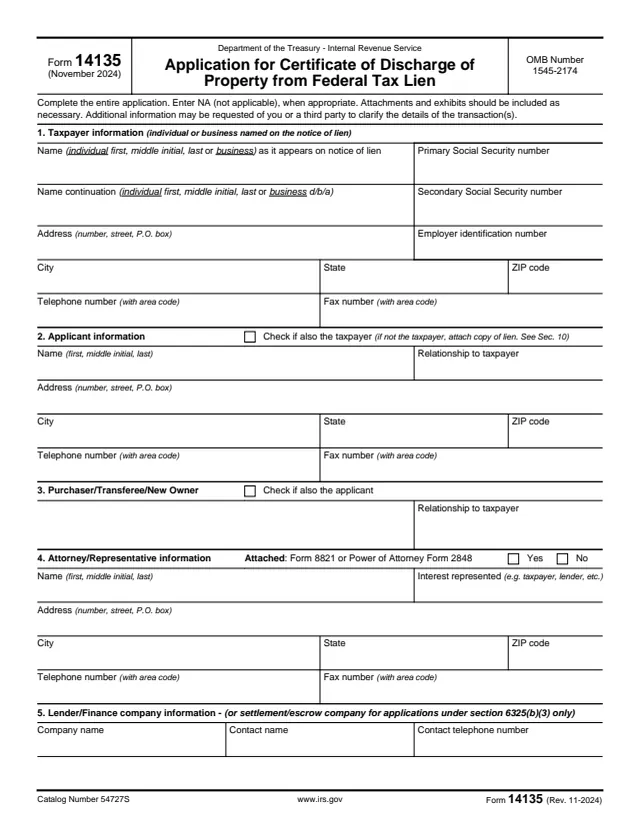
Form 14135, Application for Certificate of Discharge of Property from Federal Tax Lien, is a three-page IRS application about a specific property covered by a notice of federal tax lien. It names the taxpayer on the lien, the applicant, the purchaser, transferee or new owner, any attorney or representative, and the lender, finance company or settlement company, along with the proposed sales price and the proceeds expected to be paid to the United States.
The applicant checks the one basis for discharge that best fits, under Internal Revenue Code section 6325(b)(1), 6325(b)(2)(A), 6325(b)(2)(B), 6325(b)(3) or 6325(b)(4). The form says Publication 783 has additional descriptions of these sections.
The form says to complete the entire application and enter NA (not applicable) when appropriate. It has no separate instructions and prints no mailing address or deadline. You can fill out Form 14135 free in your browser on this page and download it without an account.
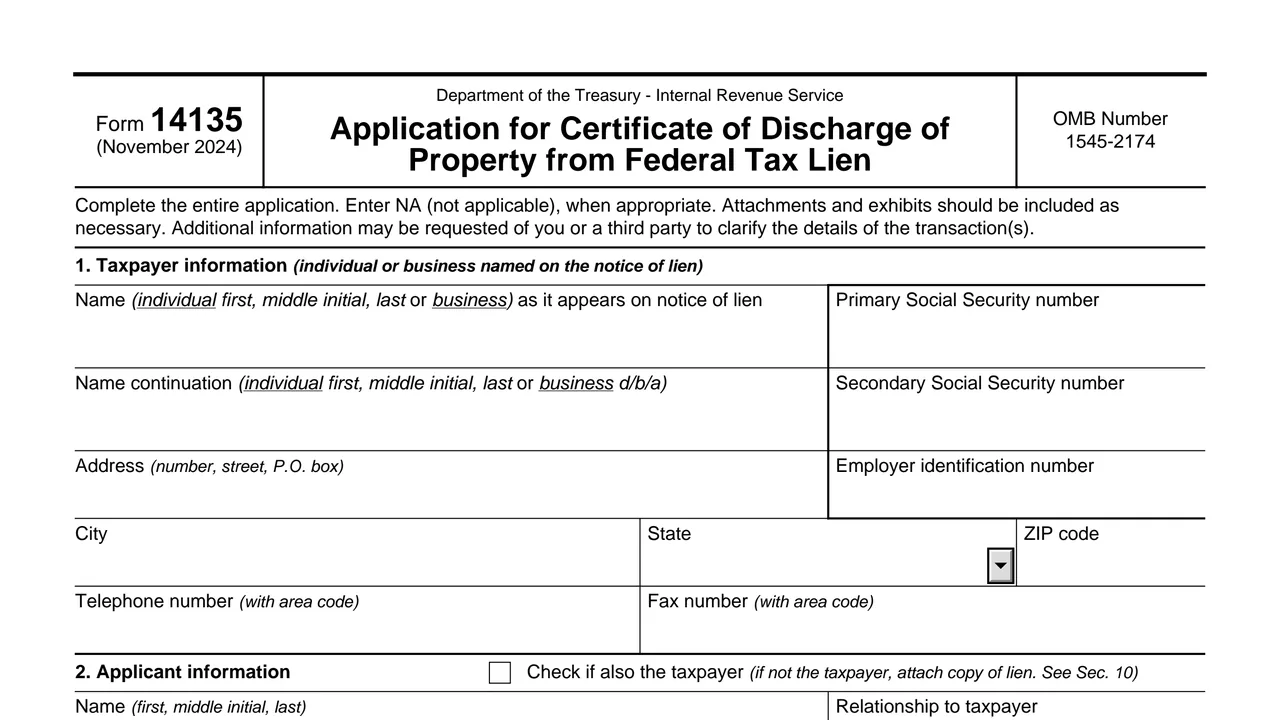
Taxpayer, applicant, purchaser or new owner, attorney or representative, and lender, finance or settlement company, each with contact details.
The proposed sales price and the proceeds expected to be paid to the United States in exchange for the certificate of discharge.
Five checkboxes: 6325(b)(1), 6325(b)(2)(A), 6325(b)(2)(B), 6325(b)(3) and 6325(b)(4), each with a short description printed beside it.
Description and address of the property, a copy of the deed or title, a professional appraisal and one additional valuation.
Copy of the lien or its serial numbers, the sales contract, a title report or list of senior encumbrances, the proposed closing statement, additional information and an escrow agreement.
A waive or no choice for third-party owners applying under section 6325(b)(2), then two signature lines under penalties of perjury with title and date.
Enter the taxpayer exactly as the name appears on the notice of lien, then the applicant, the purchaser or new owner, any representative and the lender. Check the boxes where the applicant is also the taxpayer or the new owner is also the applicant.
Enter the proposed sales price and the expected proceeds to the United States. The form says to enter 0.00 if no proceeds are anticipated. Check the one basis for discharge that best fits.
Describe the property and give its address. For real estate, attach a legible copy of the deed or title. Attach the professional appraisal plus one other valuation. For 6325(b)(1), add deeds and valuations for the property remaining under the lien.
If the applicant and taxpayer differ, attach the lien or list its serial numbers. Attach the sales contract or describe how the taxpayer will be divested, a title report or a list of senior encumbrances, and the proposed closing statement or an itemized list of costs.
Mark whether additional information such as pending litigation is attached. For a 6325(b)(3) application, attach the escrow agreement described in section 15.
A third-party owner applying under 6325(b)(2) checks Waive or No. Sign and date the declaration, adding a title if signing for a business.
The form says to complete the entire application, enter NA (not applicable) when appropriate, and include attachments and exhibits as necessary.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form prints no mailing address, fax number or deadline. It points to Publication 783 for more on the Code sections in section 7.
Section 9 lists a required professional appraisal completed by a disinterested third party, plus one additional valuation such as a county valuation, an informal valuation or the proposed auction selling price.
For 6325(b)(3), the form says the agreement specifies the account, depositary, payment conditions, escrow cost and parties, and is signed by all parties including the Advisory Group Manager before discharge is approved.
The form says an owner who is not the taxpayer and does not waive under section 16 has the application treated as one under 6325(b)(4), with any payment treated as a deposit.
The form says additional information may be requested of the applicant or a third party to clarify the details of the transaction.
The signer declares under penalties of perjury that the application and its schedules, exhibits, affidavits and statements are true, correct and complete to the best of their knowledge and belief.
14134
84 fields, 3 pages
8821
45 fields, 1 page

2848
92 fields, 2 pages
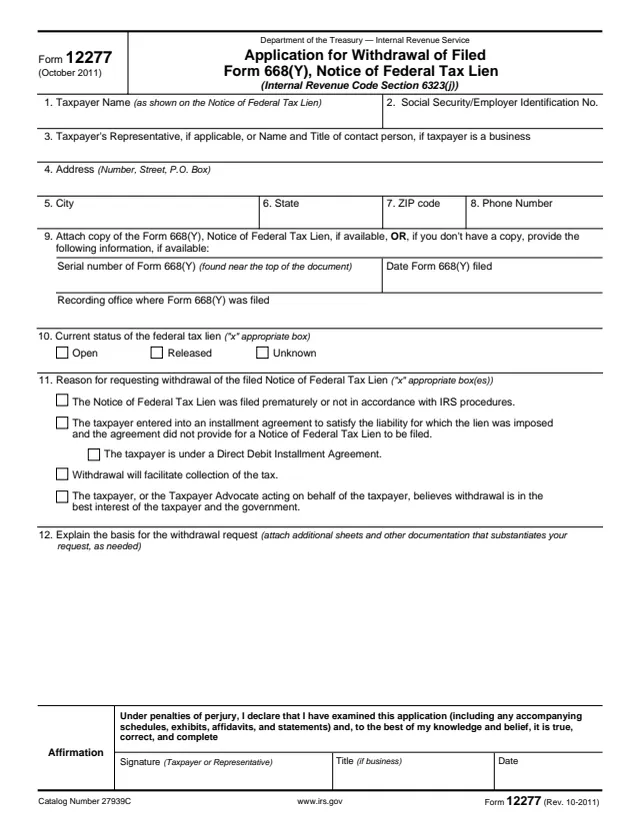
12277
22 fields, 2 pages
The applicant completes and signs the form. The applicant can be the taxpayer named on the notice of lien or someone else, and the form asks for the applicant's relationship to the taxpayer.
No tool matches that search.
A certificate of discharge of a property from a federal tax lien, with the parties, the sales price and expected proceeds, the basis under section 6325(b), and supporting documents.
The form asks for the applicant's relationship to the taxpayer and says an applicant who is not the taxpayer attaches a copy of the lien.
6325(b)(1) for remaining property worth at least double the lien plus senior encumbrances, 6325(b)(2)(A) for an amount not less than the United States' interest, 6325(b)(2)(B) where that interest has no value, 6325(b)(3) for sale proceeds held in escrow, and 6325(b)(4) for a deposit or bond.
Section 9 lists a professional appraisal by a disinterested third party as required, plus one additional valuation such as a county valuation or an informal valuation.
It is for an owner who is not the taxpayer applying under 6325(b)(2). The form says that by waiving, the payment is not treated as a deposit under 6325(b)(4) and the remedy under section 7426(a)(4) is given up.
The form itself prints no address. It refers to Publication 783 for descriptions of the Code sections it uses.