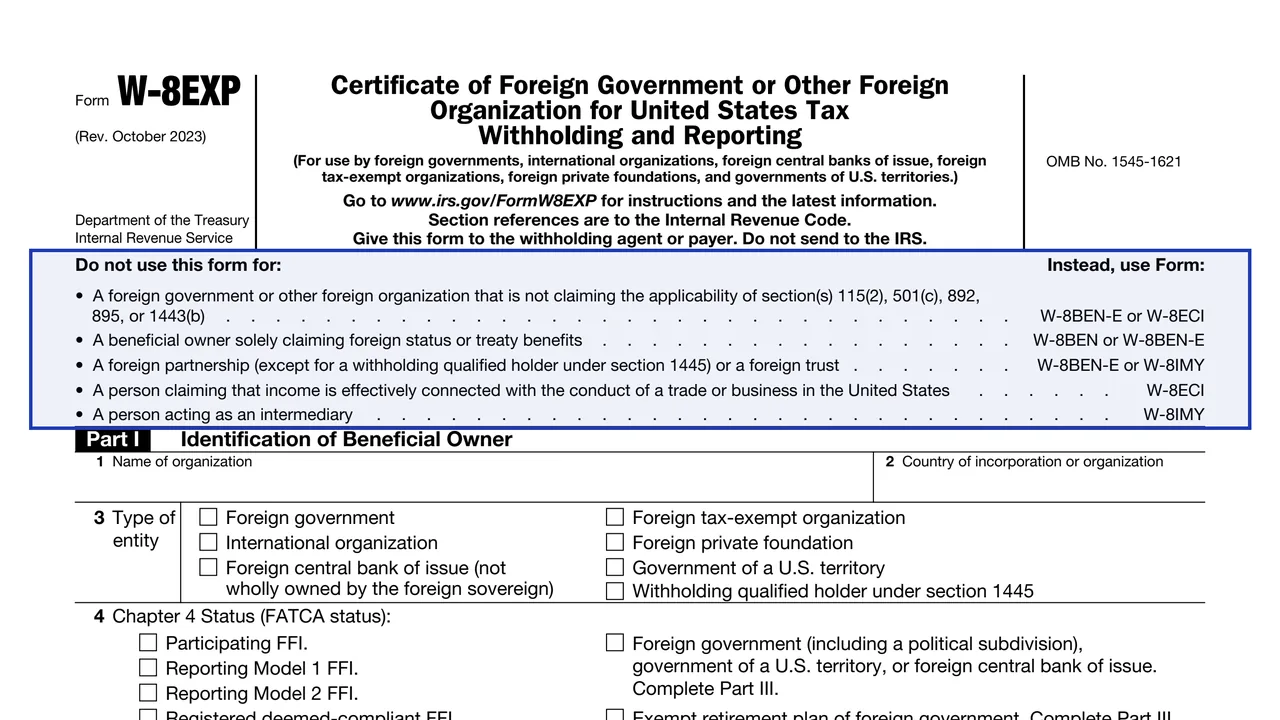
Do not use this form for
A list at the top that points other filers to Form W-8BEN, W-8BEN-E, W-8ECI or W-8IMY.
W-8EXP
Certificate of Foreign Government or Other Foreign Organization for United States Tax Withholding and Reporting
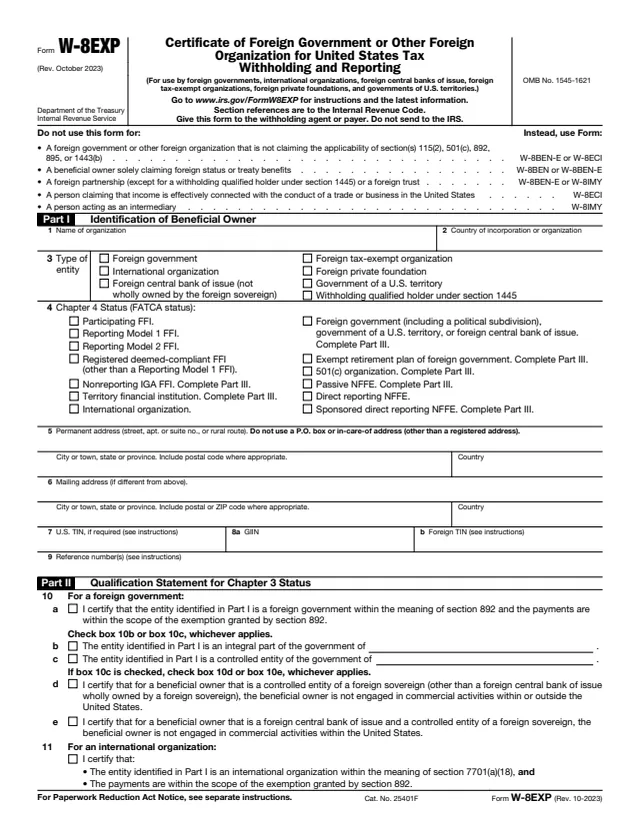
Form W-8EXP, Certificate of Foreign Government or Other Foreign Organization for United States Tax Withholding and Reporting, is for use by foreign governments, international organizations, foreign central banks of issue, foreign tax-exempt organizations, foreign private foundations and governments of U.S. territories. The IRS says the form is used to establish that the organization is not a U.S. person, to claim that it is the beneficial owner of the income, and to claim a reduced rate of, or exemption from, withholding.
The instructions add that a withholding qualified holder under section 1445 may also use it, and that a withholding agent may request it to establish the organization's chapter 4 (FATCA) status.
The form says: "Give this form to the withholding agent or payer. Do not send to the IRS." It is signed by an authorized official of the organization. You can fill out the PDF free in your browser on this page and download it without an account.
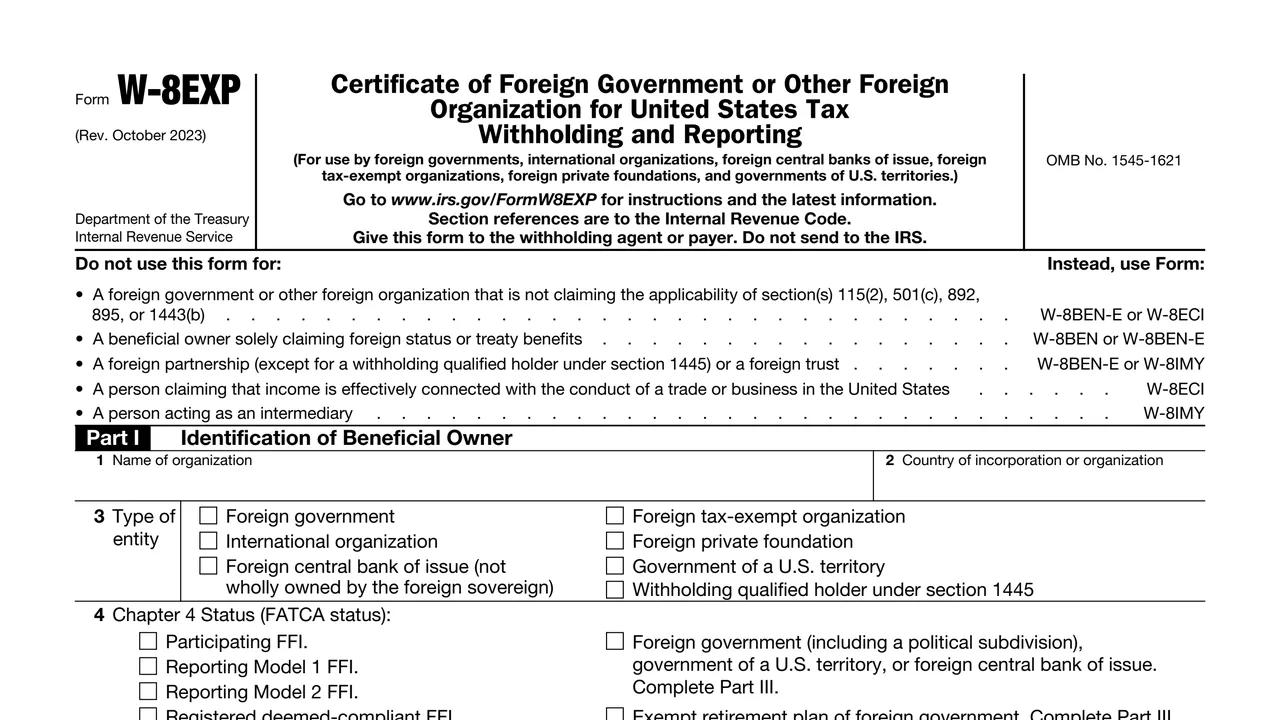
A list at the top that points other filers to Form W-8BEN, W-8BEN-E, W-8ECI or W-8IMY.
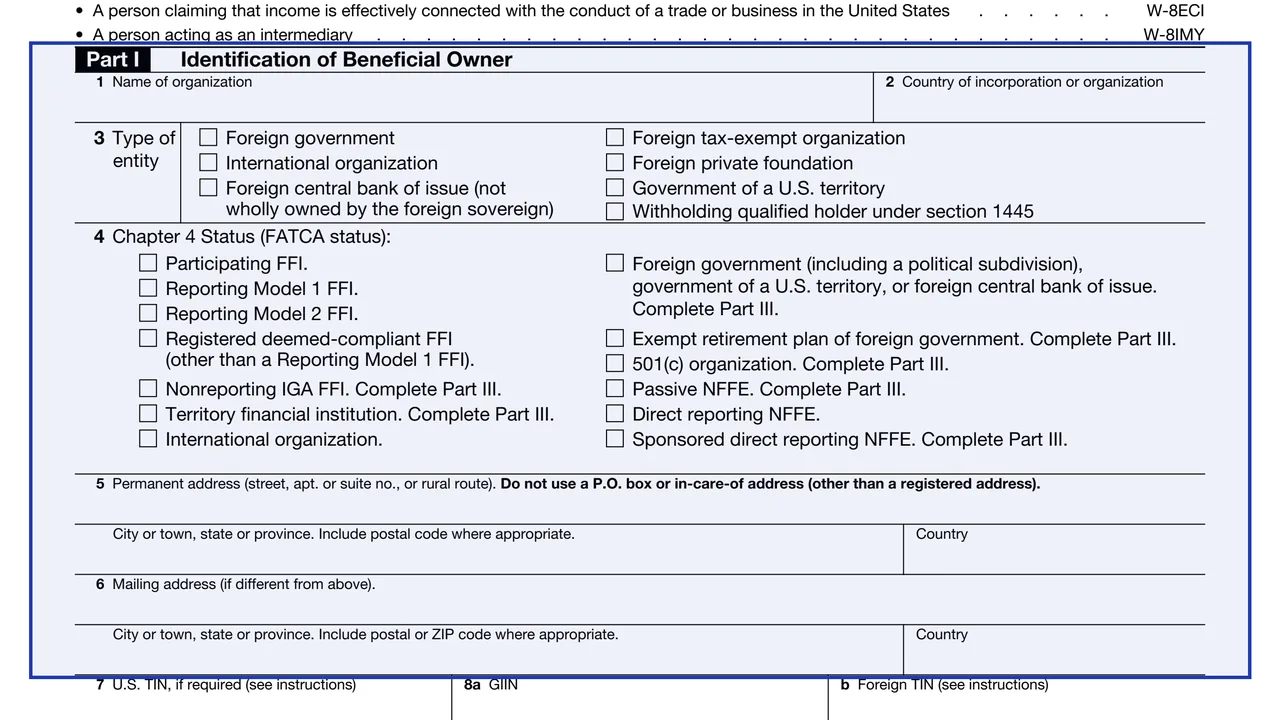
Name, country of organization, type of entity, chapter 4 (FATCA) status, permanent and mailing addresses, U.S. TIN, GIIN, foreign TIN and reference numbers.
Qualification statements for a foreign government, an international organization, a foreign central bank of issue, a foreign tax-exempt organization, a U.S. territory government and a withholding qualified holder.
Statements for a nonreporting IGA FFI, territory financial institution, foreign government, exempt retirement plan, 501(c) organization, passive NFFE and sponsored direct reporting NFFE.
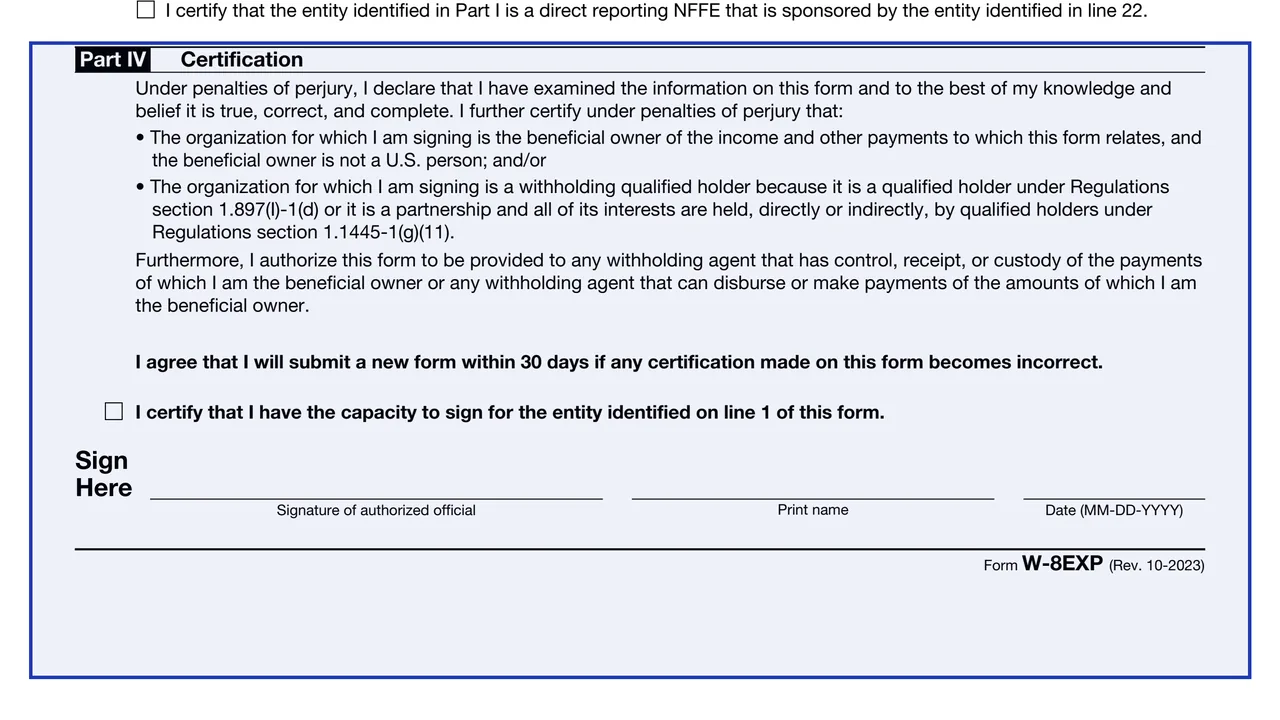
Statements made under penalties of perjury, an agreement to submit a new form within 30 days if a certification becomes incorrect, a capacity-to-sign box, and the authorized official's signature.
Before Part I, the instructions say to complete the Worksheet for Foreign Governments, International Organizations, and Foreign Central Banks of Issue, use it for line 3 and Part II, and keep it rather than give it to the withholding agent.
Enter the full name and country, then check one entity box. A foreign central bank of issue wholly owned by a foreign sovereign checks Foreign government, and a foreign private foundation checks that box rather than Foreign tax-exempt organization.
Check the one box for chapter 4 status if necessary. The instructions say a status is required for a payee of a withholdable payment or an account holder at an FFI requesting the form.
Enter the permanent address (no P.O. box or in-care-of address other than a registered address), a mailing address if different, the U.S. TIN (an EIN, obtained with Form SS-4), GIIN, foreign TIN and any reference number.
Check the statements that apply. Foreign governments claiming section 892 check box 10a plus 10b or 10c. A tax-exempt organization attaches a statement of any section 512 income and checks 13a or 13b.
An authorized official signs, prints a name and dates the form, and checks the box certifying capacity to sign. A withholding agent may allow an electronic signature, but the instructions say typing a name is not one.
These steps summarize the Specific Instructions for Form W-8EXP.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to give it to the withholding agent or payer and not send it to the IRS. The instructions say a separate Form W-8EXP generally goes to each withholding agent.
The instructions say to give it before the payment is made, credited or allocated. Without it, the withholding agent may have to withhold tax at the highest applicable rate.
Generally it stays in effect until a change in circumstances makes information on it incorrect. In some cases it is valid only through the last day of the third succeeding calendar year after signing.
The instructions say to notify the withholding agent within 30 days of a change that makes the form incorrect and to file a new Form W-8EXP or other appropriate form.
The instructions describe a 30% tax on certain U.S. source payments to foreign persons and a 4% rate under section 1443 on gross investment income of a foreign private foundation.
W-8BEN-E
179 fields, 8 pages
W-8
23 fields, 1 page
W-8
36 fields, 1 page
W-8
148 fields, 8 pages
SS-4
89 fields, 2 pages
1042-S
300 fields, 7 pages
The form is completed by an organization, not by an individual, and is given to the withholding agent or payer that asks for it.
No tool matches that search.
No. The form says to give it to the withholding agent or payer and not to send it to the IRS.
The form is for foreign governments, international organizations, foreign central banks of issue, foreign tax-exempt organizations, foreign private foundations, governments of U.S. territories and withholding qualified holders.
The instructions give the example that a foreign tax-exempt organization claiming a benefit under an income tax treaty provides Form W-8BEN-E.
The instructions say a U.S. TIN, meaning an EIN, is generally required when the claim rests solely on section 501(c) tax-exempt status or private foundation status. Form SS-4 is used to obtain an EIN.
Generally it remains in effect until a change in circumstances makes it incorrect. The instructions list cases, such as a controlled entity of a foreign government, where it lasts through the third succeeding calendar year.
A withholding agent may allow it. The instructions say the signature must show it was electronically signed by an authorized person, and simply typing a name is not an electronic signature.