Corporation details
Name of the corporation, employer identification number, address and a box for the type of return: 1120, 1120-L, 1120-IC-DISC, 1120S or Other.
966
Corporate Dissolution or Liquidation
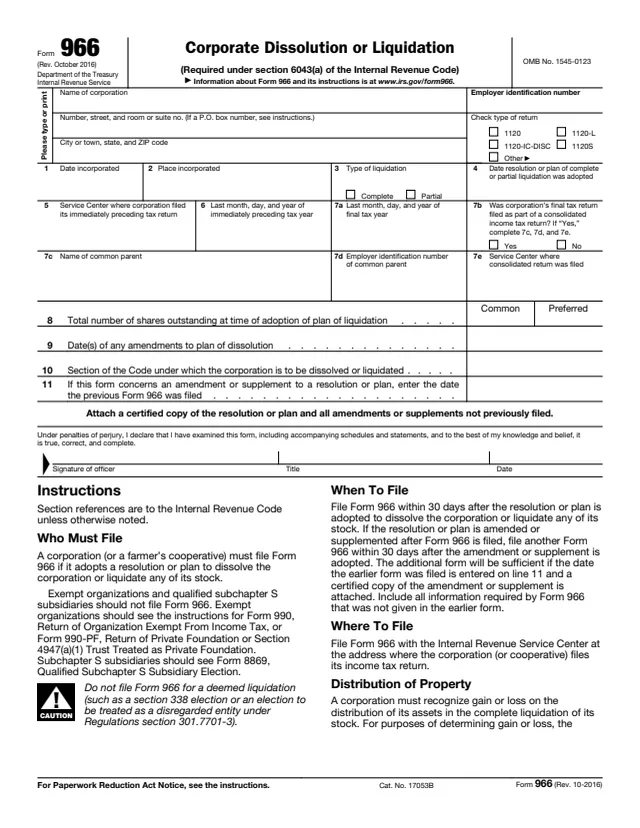
Form 966, Corporate Dissolution or Liquidation, is required under section 6043(a) of the Internal Revenue Code. The IRS says a corporation (or a farmer's cooperative) files this form if it adopts a resolution or plan to dissolve the corporation or liquidate any of its stock.
The form asks for the corporation's name, employer identification number and address, the type of return it files, the type of liquidation, key dates, the shares outstanding and the Code section the dissolution or liquidation falls under. A corporate officer signs it, and a certified copy of the resolution or plan is attached. The instructions are printed on the form itself, on pages 1 and 2.
You can fill out Form 966 free in your browser on this page and download it without an account.
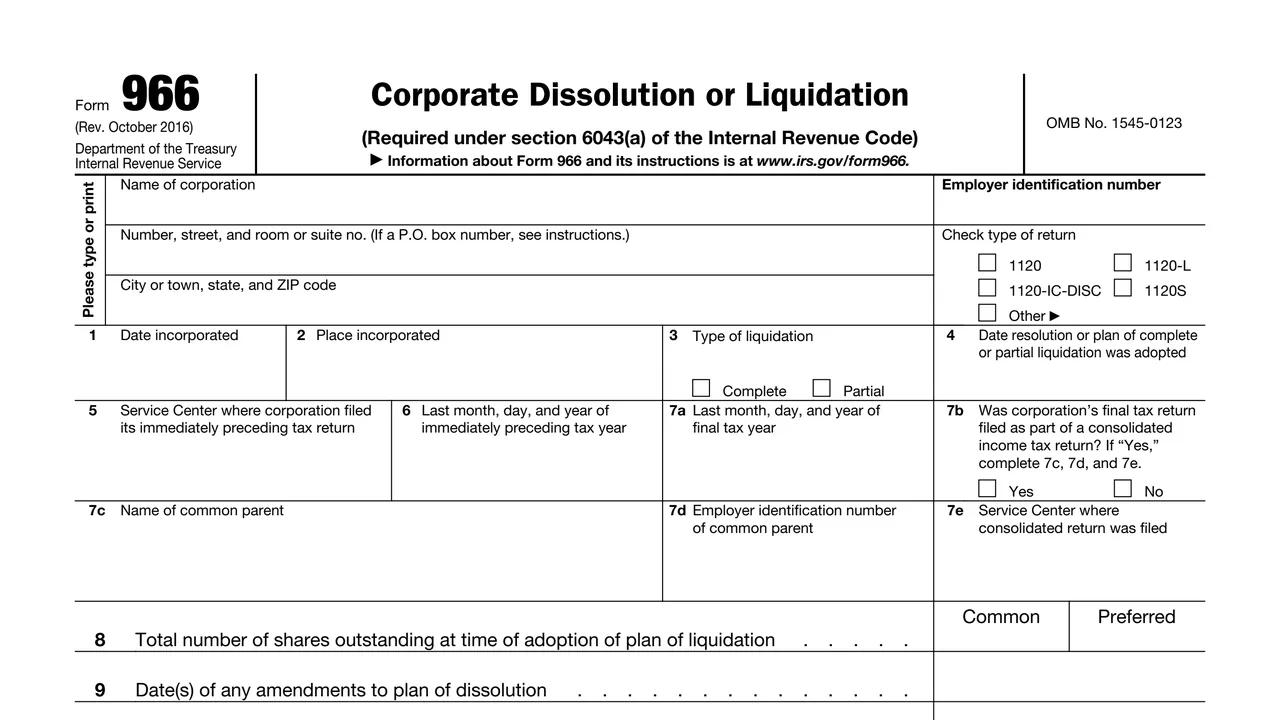
Name of the corporation, employer identification number, address and a box for the type of return: 1120, 1120-L, 1120-IC-DISC, 1120S or Other.
Date and place incorporated, the type of liquidation (complete or partial), and the date the resolution or plan of complete or partial liquidation was adopted.
The service center for the preceding tax return, the last day of the preceding and final tax years, and the common parent's name, EIN and service center if the final return was part of a consolidated return.
Common and preferred shares outstanding when the plan was adopted, dates of any amendments, the Code section for the dissolution or liquidation, and the date of any earlier Form 966.
A note to attach a certified copy of the resolution or plan and all amendments or supplements not previously filed, then a penalties of perjury declaration with the officer's signature, title and date.
Include the suite, room or other unit number after the street address. The instructions say to enter a P.O. box only if the post office does not deliver mail to the street address.
Enter the service center where the corporation filed its immediately preceding tax return. If that return was filed electronically, the instructions say to enter "e-file".
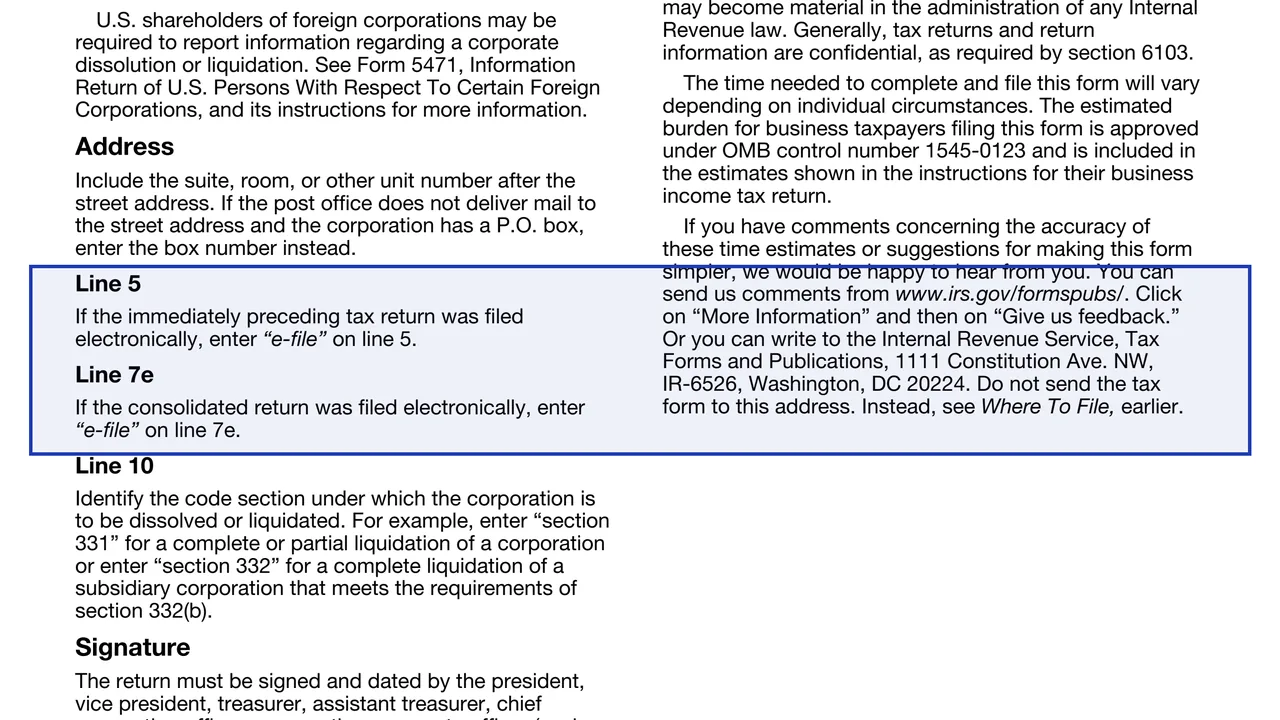
Check Yes or No for whether the final return was part of a consolidated return. If Yes, complete 7c, 7d and 7e, and enter "e-file" on line 7e if the consolidated return was filed electronically.
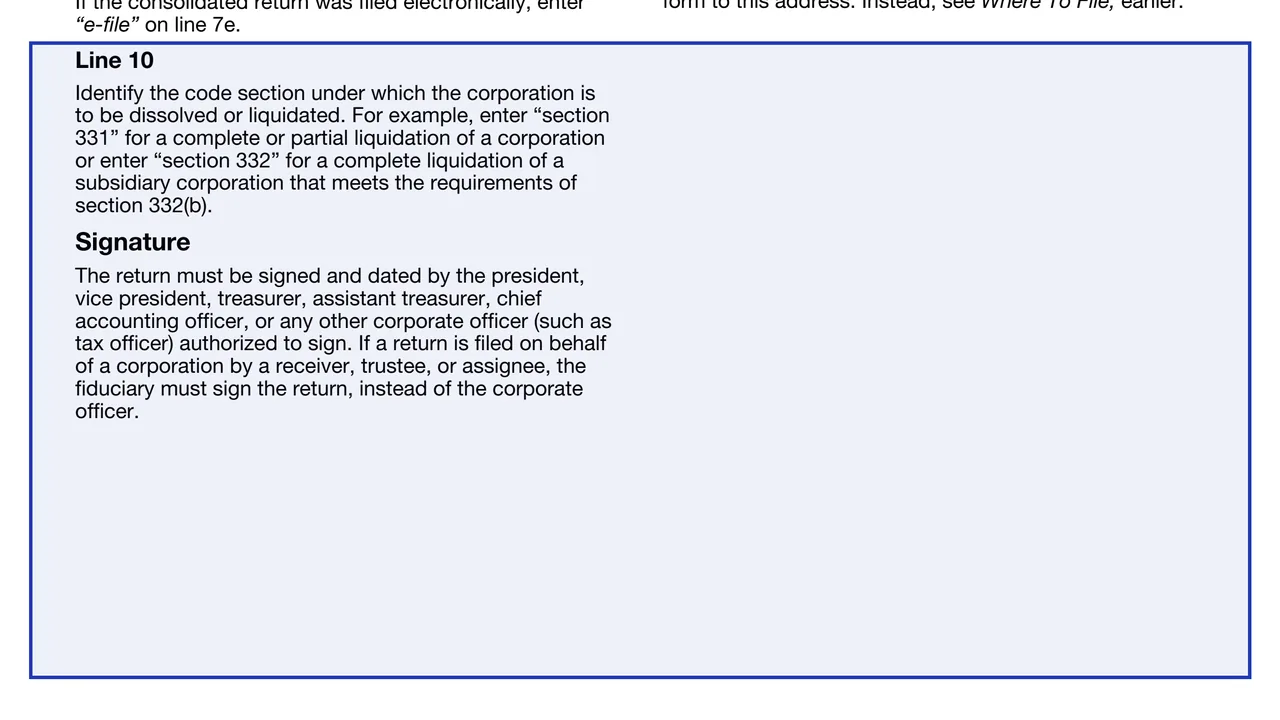
Identify the Code section. The instructions give the examples "section 331" for a complete or partial liquidation of a corporation and "section 332" for a complete liquidation of a subsidiary that meets section 332(b).
If this Form 966 concerns an amendment or supplement to the resolution or plan, enter the date the previous Form 966 was filed and attach a certified copy of the amendment or supplement.
The instructions say the president, vice president, treasurer, assistant treasurer, chief accounting officer or another authorized corporate officer signs and dates it. A receiver, trustee or assignee filing for the corporation signs instead.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file Form 966 within 30 days after the resolution or plan to dissolve the corporation or liquidate any of its stock is adopted.
If the resolution or plan is amended or supplemented after Form 966 is filed, the instructions say to file another Form 966 within 30 days after the amendment or supplement is adopted.
The instructions say to file Form 966 with the Internal Revenue Service Center at the address where the corporation (or cooperative) files its income tax return.
A certified copy of the resolution or plan and all amendments or supplements not previously filed.
The instructions say gain or loss is recognized on the distribution of assets in a complete liquidation, with assets valued at fair market value. Exceptions apply to a liquidation of a subsidiary and to a distribution under a plan of reorganization.

1120
481 fields, 6 pages

1120-S
390 fields, 5 pages
1120-F
527 fields, 9 pages
8869
31 fields, 1 page

5471
437 fields, 6 pages
990
1,075 fields, 12 pages
Form 966 is a corporate filing. It is completed by the corporation and signed by an authorized officer, not by individual shareholders.
No tool matches that search.
The instructions say within 30 days after the resolution or plan to dissolve the corporation or liquidate any of its stock is adopted.
To the Internal Revenue Service Center at the address where the corporation (or cooperative) files its income tax return.
No. The instructions say exempt organizations should not file it and should see the instructions for Form 990 or Form 990-PF.
The form says to attach a certified copy of the resolution or plan and all amendments or supplements not previously filed.
The instructions say to file another Form 966 within 30 days after the amendment or supplement is adopted, enter the earlier filing date on line 11 and attach a certified copy of the change.
No. The form cautions not to file it for a deemed liquidation, such as a section 338 election or an election to be treated as a disregarded entity.