Header
Date of receipt of the structured settlement payment rights, name, identifying number, and address with city, state or province, country and ZIP or foreign postal code.
8876
Excise Tax on Structured Settlement Factoring Transactions
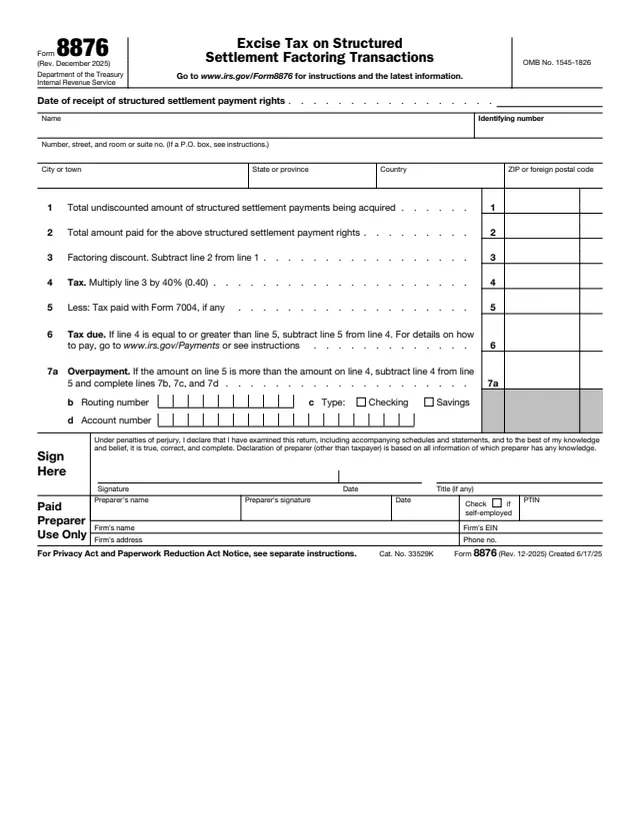
Form 8876 is the IRS return for the excise tax on structured settlement factoring transactions. The IRS page for the form says it is used to report and pay the 40% excise tax imposed under Internal Revenue Code section 5891 on the factoring discount of a structured settlement factoring transaction.
The form is short. It starts with the date of receipt of the structured settlement payment rights and the filer's name, identifying number and address. Lines 1 to 3 work out the factoring discount, line 4 figures the tax at 40%, and lines 5 to 7 compare it with any tax already paid with Form 7004 to show a balance due or an overpayment.
The IRS page says to file a separate Form 8876 for each date on which structured settlement payment rights were received in one or more structured settlement factoring transactions. You can fill out the PDF free in your browser on this page and download it without an account.
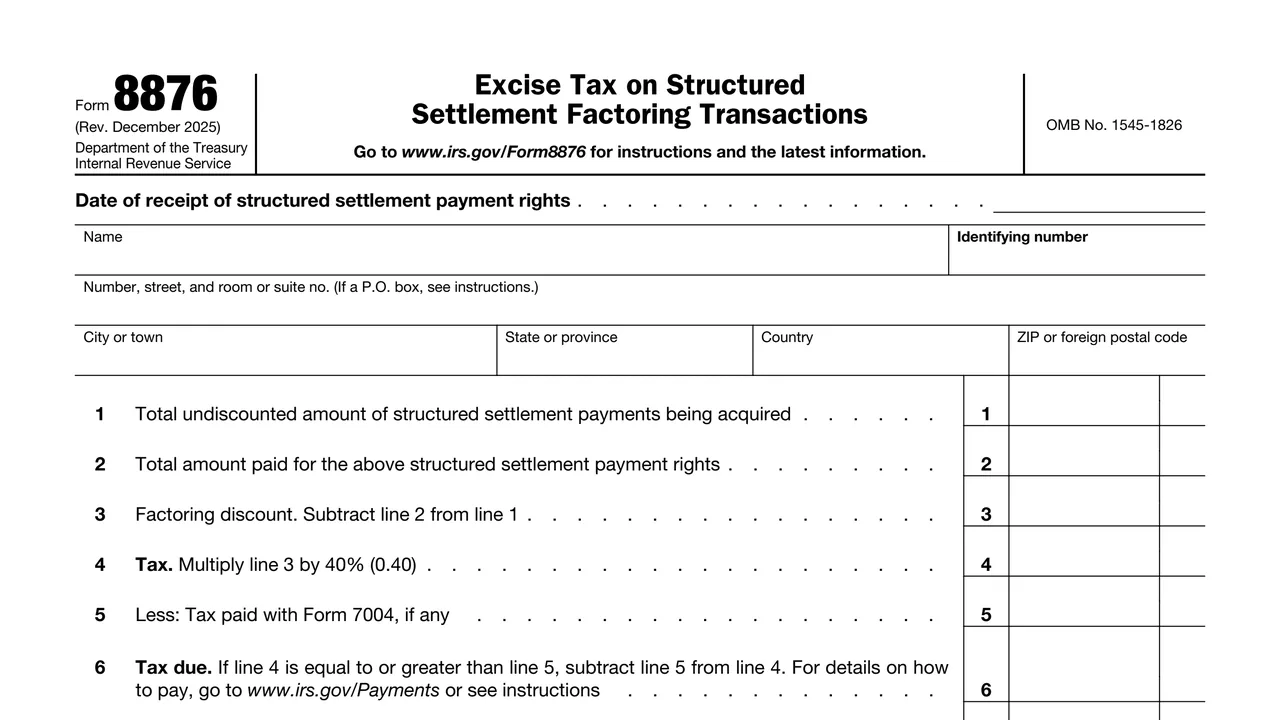
Date of receipt of the structured settlement payment rights, name, identifying number, and address with city, state or province, country and ZIP or foreign postal code.
Line 1 is the total undiscounted amount of structured settlement payments being acquired, line 2 the total amount paid for those rights, and line 3 the difference.
The form says to multiply line 3 by 40% (0.40).
Line 5 holds any tax paid with Form 7004. Line 6 shows the tax due when line 4 is equal to or greater than line 5.
An overpayment on line 7a, with a routing number, a checking or savings box and an account number for the refund.
The penalties of perjury declaration, signature, date and title, followed by the Paid Preparer Use Only block.
Enter the date of receipt of the structured settlement payment rights, then the name, identifying number and address. For a P.O. box, the form says to see the instructions.
Enter the total undiscounted amount of the structured settlement payments being acquired on line 1 and the total amount paid for those payment rights on line 2.
Subtract line 2 from line 1 to get the factoring discount on line 3. Multiply line 3 by 40% (0.40) and enter the tax on line 4.
Enter any tax paid with Form 7004 on line 5. If line 4 is equal to or greater than line 5, subtract line 5 from line 4. The form points to www.irs.gov/Payments for how to pay.
If line 5 is more than line 4, subtract line 4 from line 5 on line 7a and complete lines 7b, 7c and 7d with the routing number, account type and account number.
Sign and date the return and add a title if there is one. A paid preparer fills in the preparer block.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The IRS page says Form 8876 reports and pays the 40% excise tax imposed under section 5891 on the factoring discount of a structured settlement factoring transaction.
A separate Form 8876 for each date on which structured settlement payment rights were received, according to the IRS page.
Line 6 says that for details on how to pay, go to www.irs.gov/Payments or see the instructions.
Any tax paid with Form 7004 goes on line 5 and reduces the amount due. The IRS page lists Form 7004 among the related items.
The form does not print a filing address or due date. It says to go to www.irs.gov/Form8876 for instructions and the latest information.

7004
26 fields, 1 page
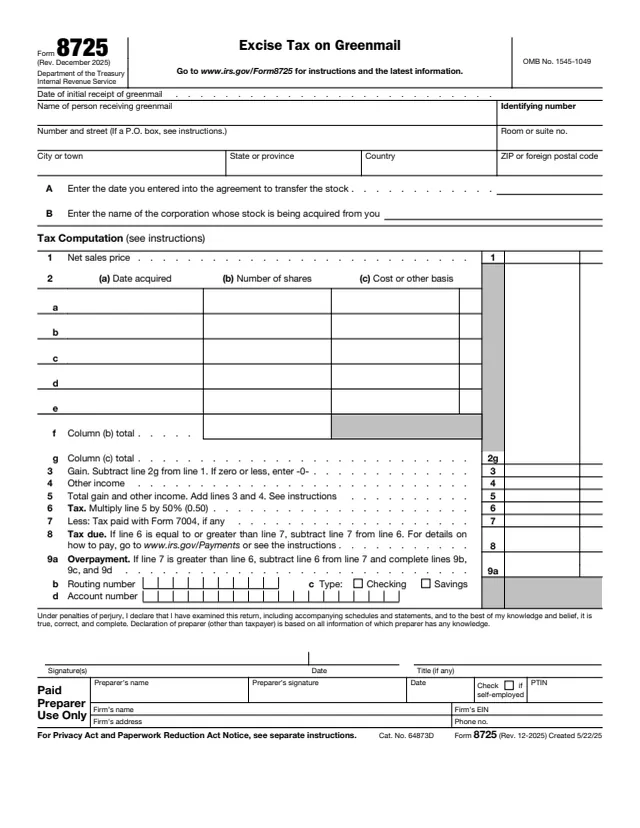
8725
62 fields, 1 page
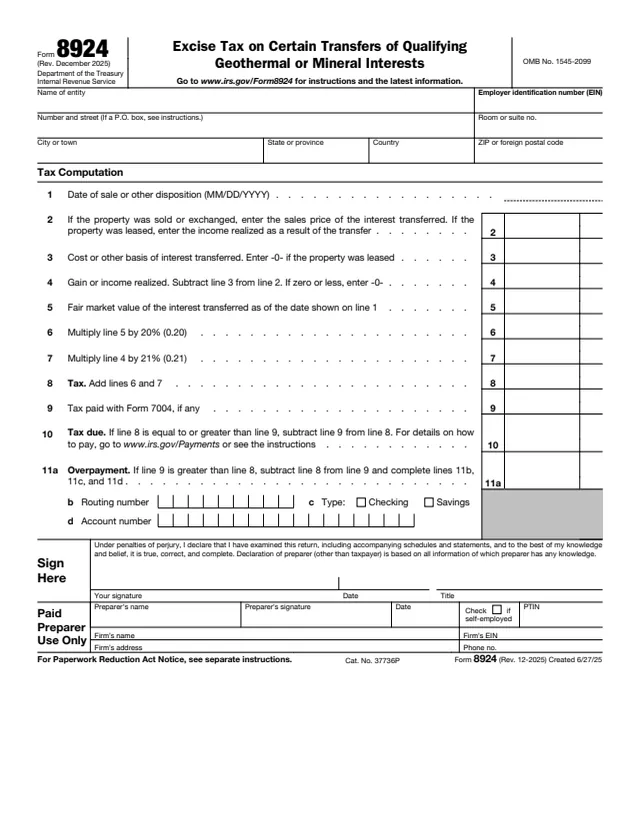
8924
41 fields, 1 page
8831
27 fields, 5 pages
The IRS page ties the form to the receipt of structured settlement payment rights. The form itself does not print a list of filers, and the separate instructions it refers to were not part of the pages reviewed here.
No tool matches that search.
Line 4 multiplies the factoring discount by 40% (0.40). The IRS page says the tax is imposed under Internal Revenue Code section 5891.
Line 3 subtracts line 2, the total amount paid for the payment rights, from line 1, the total undiscounted amount of the structured settlement payments being acquired.
The IRS page says a separate Form 8876 for each date on which structured settlement payment rights were received in one or more factoring transactions.
Line 7a shows the overpayment, and lines 7b to 7d take the routing number, account type and account number.
The form itself prints no address. It refers to separate instructions at www.irs.gov/Form8876.