Header
Name(s) shown on the return and the identifying number.
8874
New Markets Credit
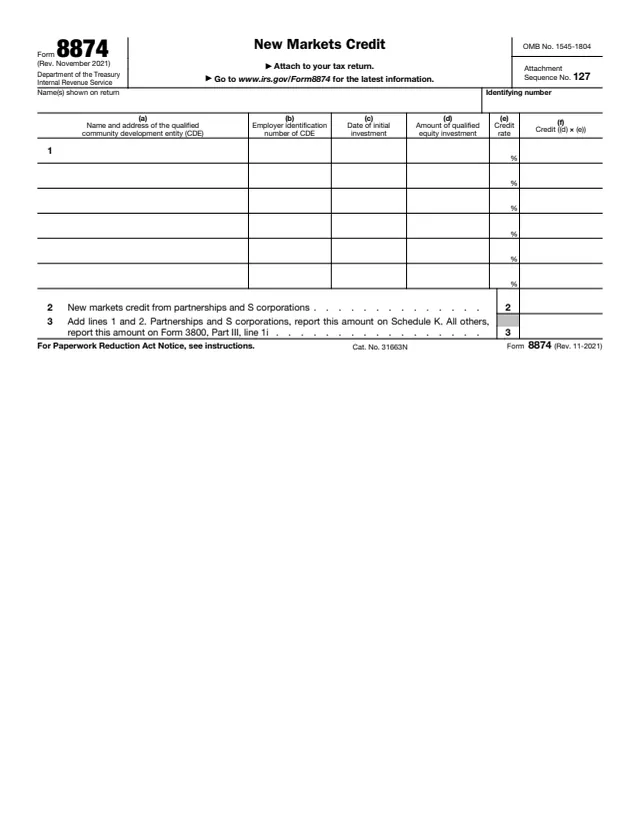
Form 8874 is used to claim the new markets credit for qualified equity investments made in qualified community development entities (CDEs). The form says this credit is part of the general business credit, and it is attached to the tax return.
The instructions say the credit is generally allowed to the holder of a qualified equity investment on each of 7 credit allowance dates: the date of the initial investment and each of the next 6 anniversary dates. Line 1 lists each investment held on a credit allowance date in the current tax year, line 2 adds credits passed through from partnerships and S corporations, and line 3 carries the total to Schedule K or to Form 3800.
The instructions are printed in the same PDF. The IRS About page also lists a recent development titled "New markets credit updated and made permanent". You can fill out Form 8874 free in your browser on this page and download it without an account.
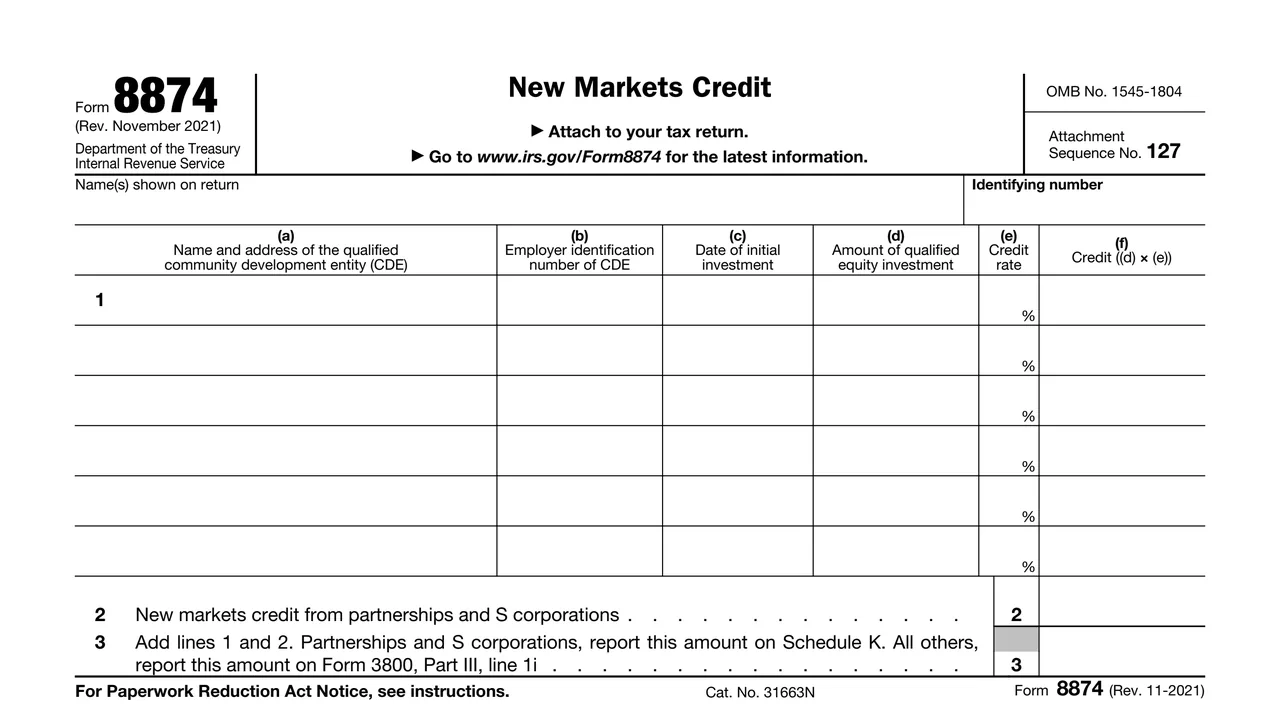
Name(s) shown on the return and the identifying number.
Name and address of the qualified CDE, the CDE's employer identification number and the date of the initial investment.
Amount of the qualified equity investment, the credit rate as a percentage, and the credit, figured as column (d) times column (e).
New markets credit from partnerships and S corporations.
The sum of lines 1 and 2, with the note on where partnerships, S corporations and all other filers report it.
Definitions of a qualified CDE and a qualified equity investment, how to figure the credit, recapture, basis reduction and the line 1 instructions.
Enter the name or names shown on the tax return and the identifying number.
The instructions say to enter the information for each qualified equity investment held directly on a credit allowance date in the current tax year: the CDE's name, address and EIN, the date of initial investment and the amount.
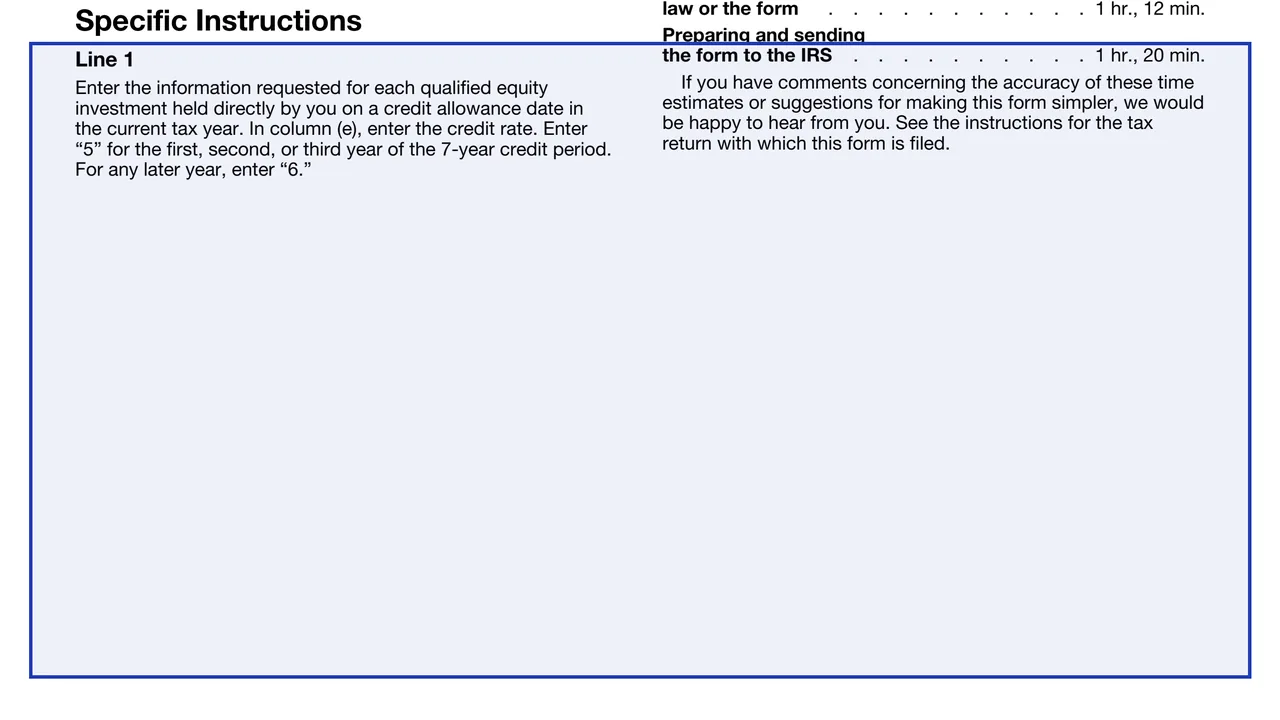
The instructions say to enter "5" for the first, second or third year of the 7-year credit period, and "6" for any later year.
Multiply column (d) by column (e). If more space is needed, the instructions say to attach a statement, write "See attached" in column (a) of the last row and enter the statement's total credit in column (f).
Enter the new markets credit received from partnerships and S corporations.
Add lines 1 and 2. The form says partnerships and S corporations report this amount on Schedule K, and all others report it on Form 3800, Part III, line 1i.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to your tax return." The form prints Attachment Sequence No. 127.
The instructions say the credit equals the qualified equity investment multiplied by 5% (6% for the fourth through seventh years), and is not allowed for a date on which the investment is not a qualified equity investment.
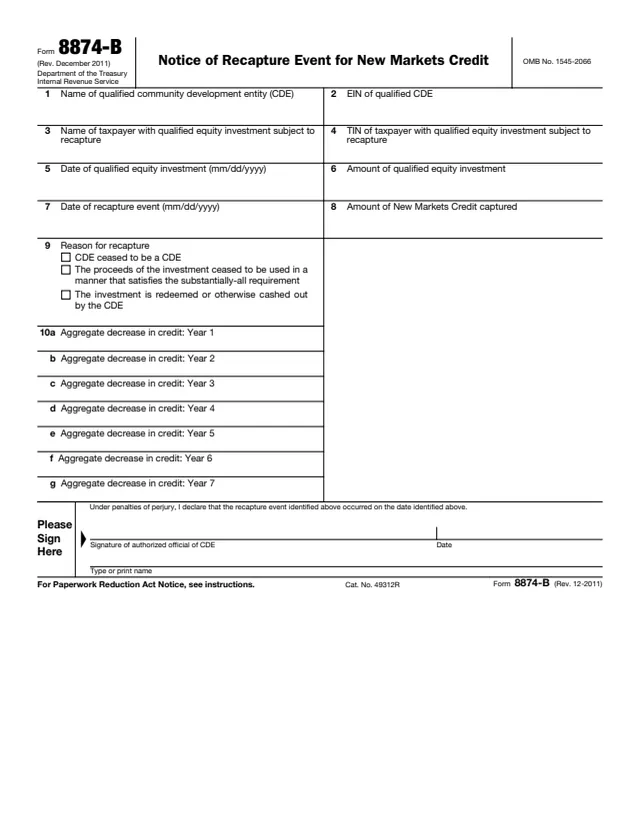
The instructions list three events within 7 years of original issuance that can bring a credit recapture amount: the entity stops being a qualified CDE, substantially all proceeds stop being used for qualified low-income community investments, or the investment is redeemed.
The instructions say a sale or other disposition alone does not cause recapture, but the credit cannot be claimed for any credit allowance date after the disposition.
The instructions say basis in the qualified equity investment is reduced by the new markets credits allowed, even if part of the credit is carried forward, with listed exceptions for figuring certain gain exclusions.
8874-A
17 fields, 2 pages
8874-B
19 fields, 2 pages

3800
1,921 fields, 9 pages

1040
199 fields, 2 pages

1065
440 fields, 6 pages

1120-S
390 fields, 5 pages
The form is attached to the tax return of the taxpayer claiming the credit. The About page lists Form 1040, Form 1065, Form 1120 and Form 1120-S among the related returns.
No tool matches that search.
The instructions describe a domestic corporation or partnership whose primary mission is serving or providing investment capital for low-income communities or persons, that stays accountable to their residents, and that is certified as a qualified CDE by the CDFI Fund.
The instructions say "5" for the first, second or third year of the 7-year credit period and "6" for any later year.
The form says taxpayers that are not partnerships or S corporations, and whose only source of the credit is those pass-through entities, are not required to file it. They can report the credit on Form 3800, Part III, line 1i.
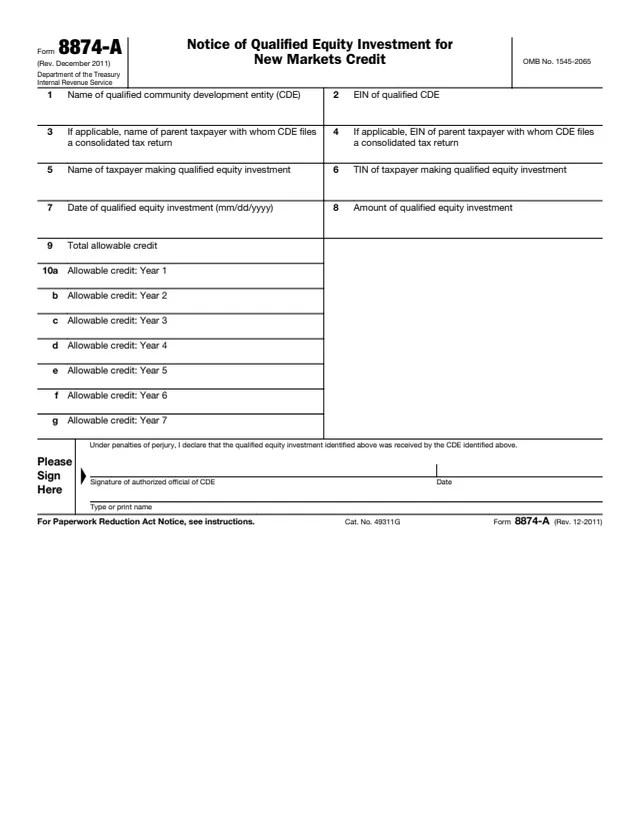
The instructions say a qualified CDE provides Form 8874-A when a qualified equity investment is acquired, and Form 8874-B when a recapture event occurs.
The instructions say not solely because of a sale or other disposition, but the credit cannot be claimed for any credit allowance date after the disposition.
The form's What's New says the allocation was extended for calendar years through 2025. The IRS About page lists a later recent development titled "New markets credit updated and made permanent", dated 29-JUN-2026.