Lines 1 to 4: the CDE
The name and EIN of the qualified CDE and, if applicable, of the parent taxpayer with whom it files a consolidated tax return.
8874-A
Notice of Qualified Equity Investment for New Markets Credit
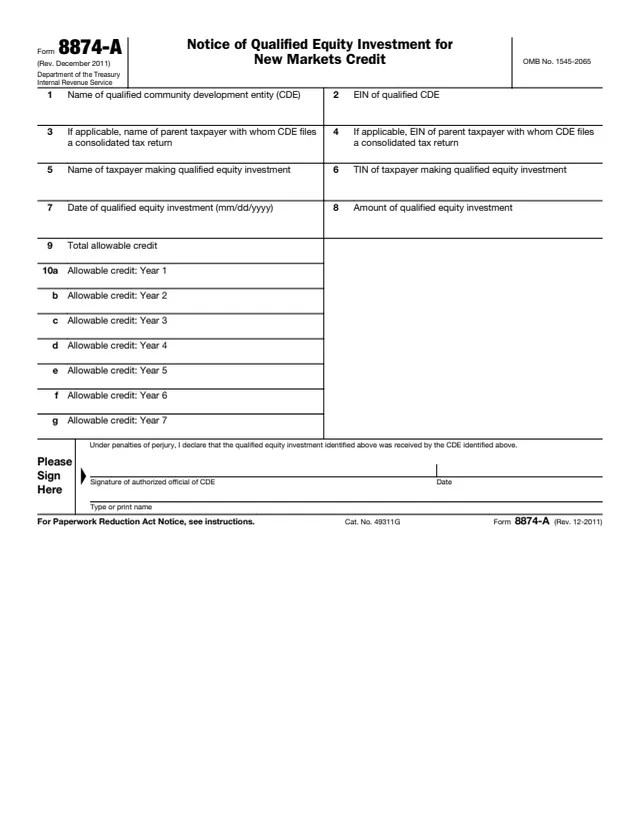
Form 8874-A, Notice of Qualified Equity Investment for New Markets Credit, is completed by a qualified community development entity (CDE). The IRS About page says CDEs use it to notify taxpayers who acquire a qualified equity investment in the CDE at its original issue that the equity investment is a qualified equity investment entitling the taxpayer to claim the new markets credit.
The instructions say the form makes the notification required under Regulations section 1.45D-1(g)(2)(i)(A). It names the CDE, any parent taxpayer it files a consolidated return with, and the investing taxpayer, then shows the date and amount of the investment, the total allowable credit and the allowable credit for each of years 1 through 7. An authorized official of the CDE signs it under penalties of perjury.
You can fill out Form 8874-A free in your browser on this page and download it without an account.
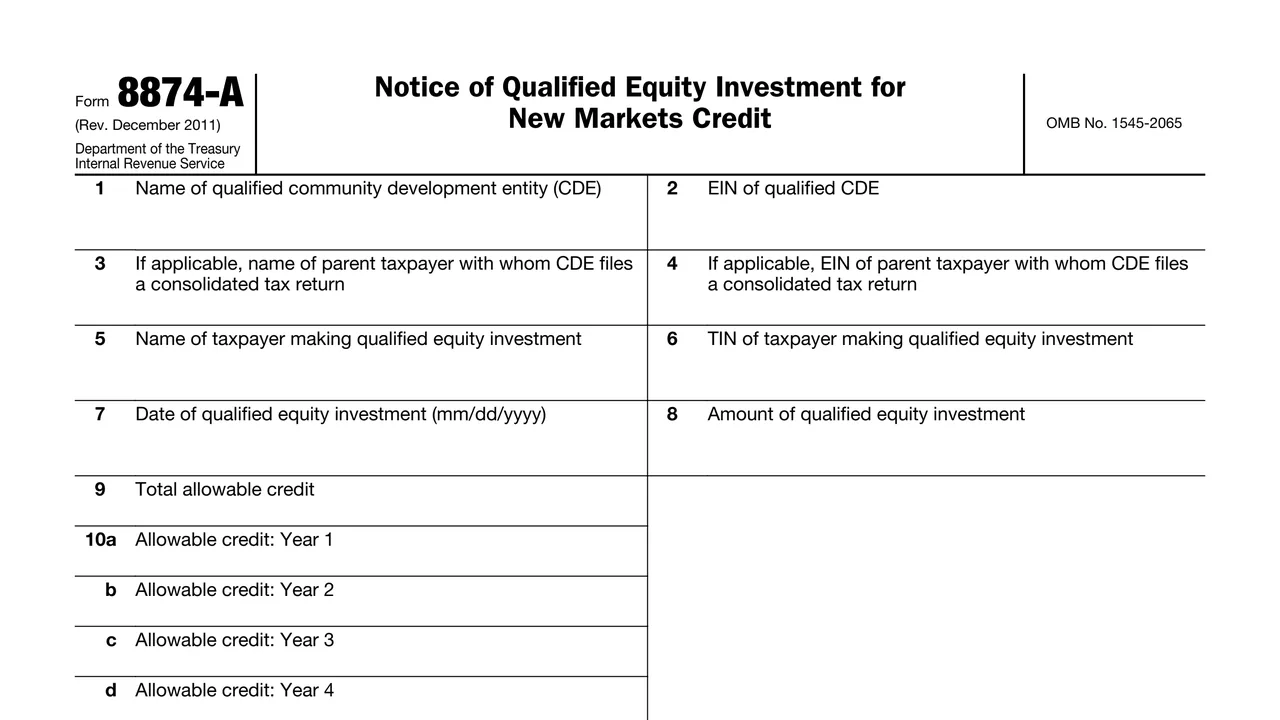
The name and EIN of the qualified CDE and, if applicable, of the parent taxpayer with whom it files a consolidated tax return.
The name and TIN of the taxpayer making the qualified equity investment.
The date of the qualified equity investment (mm/dd/yyyy) and its amount.
The total allowable credit, then the allowable credit for each of years 1 through 7.
A declaration under penalties of perjury that the CDE received the investment, signed and dated by an authorized official of the CDE, with the name typed or printed.
Enter the qualified CDE's name and EIN on lines 1 and 2. Lines 3 and 4 are completed if applicable, for a parent taxpayer the CDE files a consolidated tax return with.
Enter the name and TIN of the taxpayer making the qualified equity investment on lines 5 and 6.
Enter the date of the investment as mm/dd/yyyy on line 7 and the amount on line 8.
Enter the total allowable credit on line 9 and the allowable credit for each year on lines 10a through 10g.
An authorized official of the CDE signs and dates the declaration and types or prints their name.
The instructions say: "A separate form must be provided for each qualified equity investment."
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say the original signed form must be provided by the CDE to the taxpayer no later than 60 days after the date the taxpayer makes the investment in the CDE.
The instructions say to send a copy to Department of the Treasury, Internal Revenue Service Center, Philadelphia, PA 19255-0549.
The instructions say to keep a copy for your records.
The instructions point to Form 8874, New Markets Credit, section 45D, Regulations section 1.45D-1, and www.cdfifund.gov.
The CDE completes and signs the form. The investing taxpayer receives the original, and the IRS receives a copy.
No tool matches that search.
The qualified community development entity (CDE). An authorized official of the CDE signs it.
The taxpayer who made the qualified equity investment gets the original signed form, and a copy goes to the IRS in Philadelphia, PA.
The instructions say the CDE provides the original signed form to the taxpayer no later than 60 days after the date the taxpayer makes the investment in the CDE.
No. The instructions say a separate form must be provided for each qualified equity investment.
Lines 10a through 10g show the allowable credit for years 1 through 7, after the total allowable credit on line 9.
The instructions point to Form 8874, New Markets Credit, section 45D, Regulations section 1.45D-1, and www.cdfifund.gov.