Header
Partner's name and TIN, the distributing partnership's name and EIN, and the date property was distributed to the partner.
7217
Partner's Report of Property Distributed by a Partnership
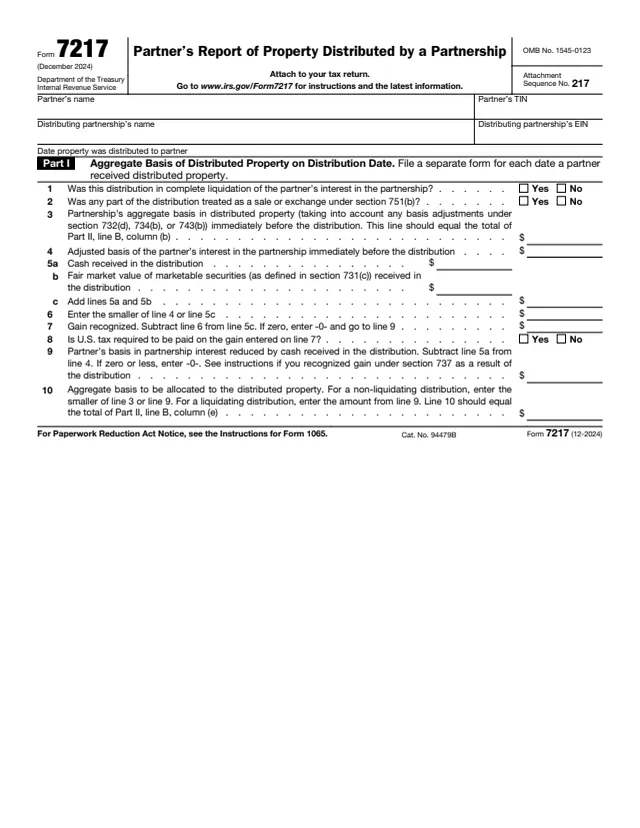
Form 7217 is the Partner's Report of Property Distributed by a Partnership. The IRS About page says it is filed by any partner receiving a distribution of property from a partnership in a non-liquidating or liquidating distribution to report the basis of the distributed property, including any basis adjustment to such property as required by section 732(a)(2) or (b).
Part I works out the aggregate basis of the distributed property on the distribution date, starting from the partnership's basis and the partner's own basis in the partnership interest. Part II allocates that basis to each distributed property, one line per item. The form says to attach it to the partner's tax return.
The instructions say to use the December 2024 version for tax years beginning in 2024 or later, until a later revision is issued. The About page lists an April 2026 update to the instructions about new reporting codes on box 19 of Schedule K-1 (Form 1065). The PDF can be filled out free in the browser on this page and downloaded without an account.
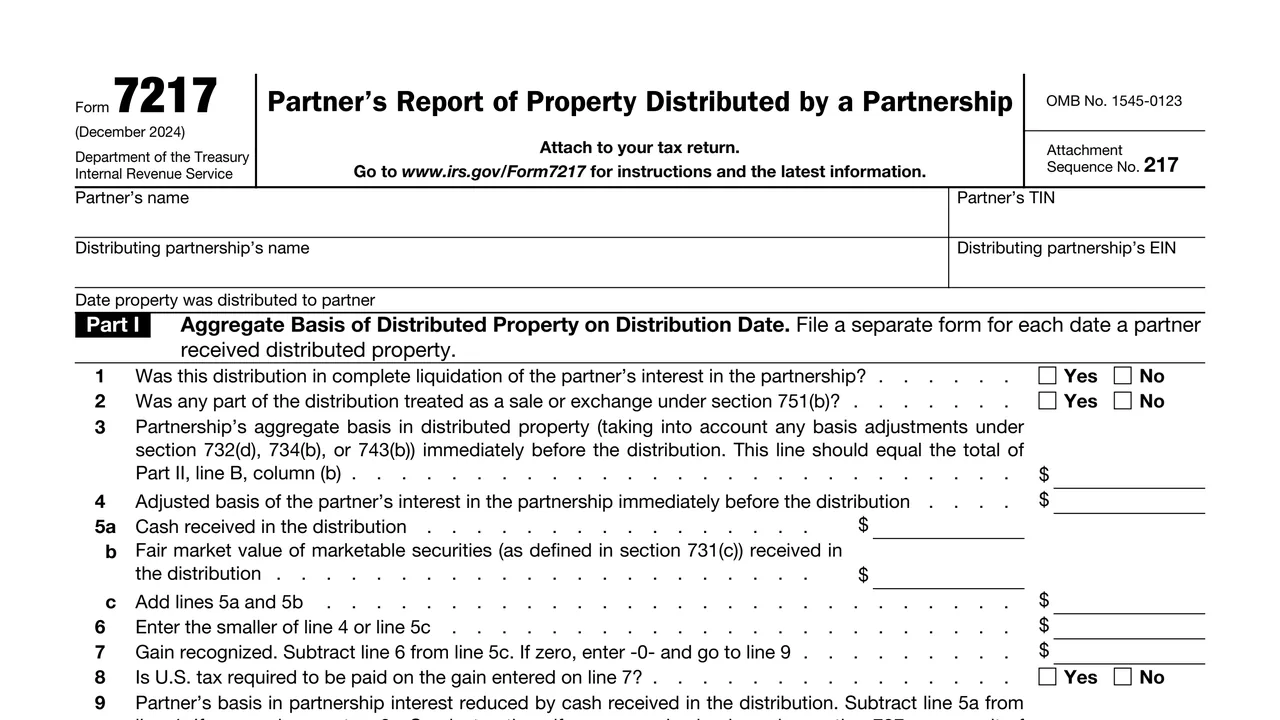
Partner's name and TIN, the distributing partnership's name and EIN, and the date property was distributed to the partner.
Yes or No questions: was the distribution in complete liquidation of the partner's interest, and was any part treated as a sale or exchange under section 751(b).
The partnership's aggregate basis in the property, the partner's adjusted basis in the partnership interest, cash and marketable securities received, gain recognized, and whether U.S. tax is required to be paid on that gain.
The partner's basis reduced by cash received, and the aggregate basis to be allocated to the distributed property.
Thirty lines with columns (a) description, (b) partnership's basis, (c) boxes for 732(d), 732(f), 734(b) and 743(b), (d) fair market value and (e) partner's basis after section 732, then totals on lines A and B.
Enter the partner's name and TIN, the partnership's name and EIN, and the date of the distribution. The instructions say a TIN can be a social security number (SSN).
Check Yes or No on lines 1 and 2. If section 751(b) applies, the instructions say to attach a statement showing the calculation. On line 3, enter the partnership's aggregate basis immediately before the distribution, which should equal Part II, line B, column (b).
Enter the adjusted basis of the partner's interest (outside basis) immediately before the distribution. The instructions say this amount is not reported on the Schedule K-1 and point to the Partner's Instructions for Schedule K-1 (Form 1065).
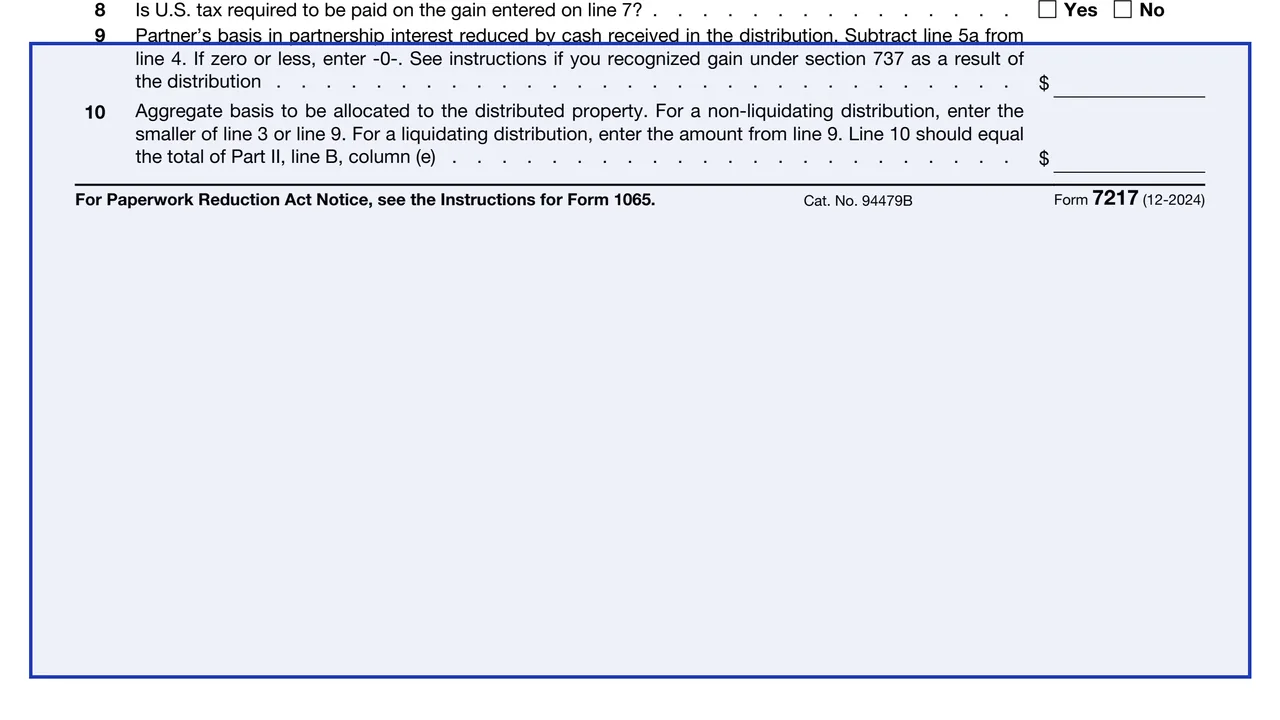
Enter cash received on line 5a and the fair market value of marketable securities on line 5b, add them on 5c, enter the smaller of line 4 or 5c on line 6, and subtract to get the gain on line 7. Answer line 8.
Subtract line 5a from line 4 on line 9, entering -0- if zero or less. On line 10, the form says to enter the smaller of line 3 or line 9 for a non-liquidating distribution, or line 9 for a liquidating one.
Describe each property, adding the asset class code from Pub. 946, Appendix B if applicable, and complete columns (b) to (e). The column (e) total on line B should equal Part I, line 10. More copies of Part II can be attached.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to your tax return." The instructions say to attach it to the tax return for the tax year in which the distributed property subject to section 732 was received.
The instructions say Form 7217 is due at the time the tax return is due, including any extensions.
The instructions say to use the December 2024 version for tax years beginning in 2024 or later, until a later revision is issued at IRS.gov/Form7217.
The About page lists an update to the Instructions for Form 7217 regarding new reporting codes on box 19, Schedule K-1 (Form 1065), dated 23-APR-2026.
The form is completed by the partner who received the distributed property, not by the partnership, and is attached to the partner's own tax return.
No tool matches that search.
The partner. The instructions say any partner receiving a distribution of property from a partnership files it with their annual tax return.
The instructions say not to file it if the distribution consisted only of money or marketable securities treated as money under section 731(c).
The instructions say to file a separate Form 7217 for each date property subject to section 732 was received, even if part of the same transaction.
The instructions say the partnership reports much of it on Schedule K-1 (Form 1065), box 19, or a section 732(d) statement. The partner's outside basis on line 4 is not on the Schedule K-1.
The instructions say it is due at the time the tax return is due, including any extensions, attached to that return.