Header
Name(s) shown on return and identifying number.
461
Limitation on Business Losses
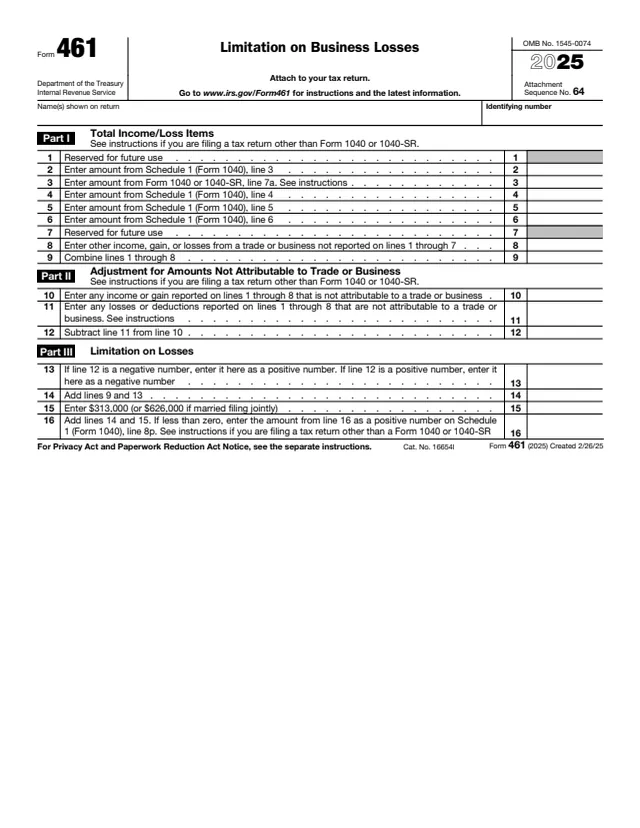
Form 461, Limitation on Business Losses, is used to figure the excess business loss reported on a noncorporate tax return. The instructions say Code section 461(l) limits the losses from trades or businesses that noncorporate taxpayers can claim each year. An excess business loss can't be deducted in the current year, but it is treated as a net operating loss (NOL) carryover for later years.
The instructions say Form 461 is filed by a noncorporate taxpayer (including a trust subject to tax under section 511) when net losses from all trades or businesses are more than $313,000 ($626,000 for a joint return), or when a loss of more than $156,500 would be reported on any one of lines 1 through 8. It is attached to the tax return, such as Form 1040, 1040-SR, 1040-NR, 1041 or 990-T.
This is the 2025 edition. You can fill out Form 461 free in your browser on this page and download it without an account.
Name(s) shown on return and identifying number.
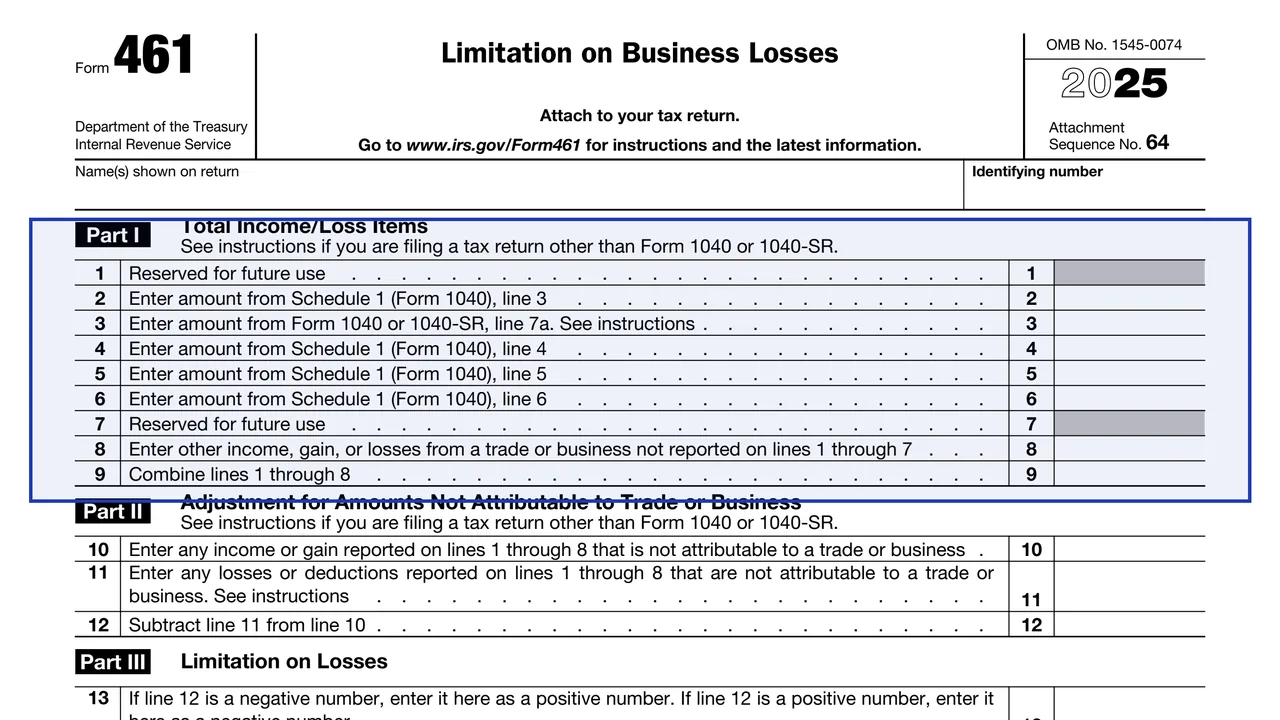
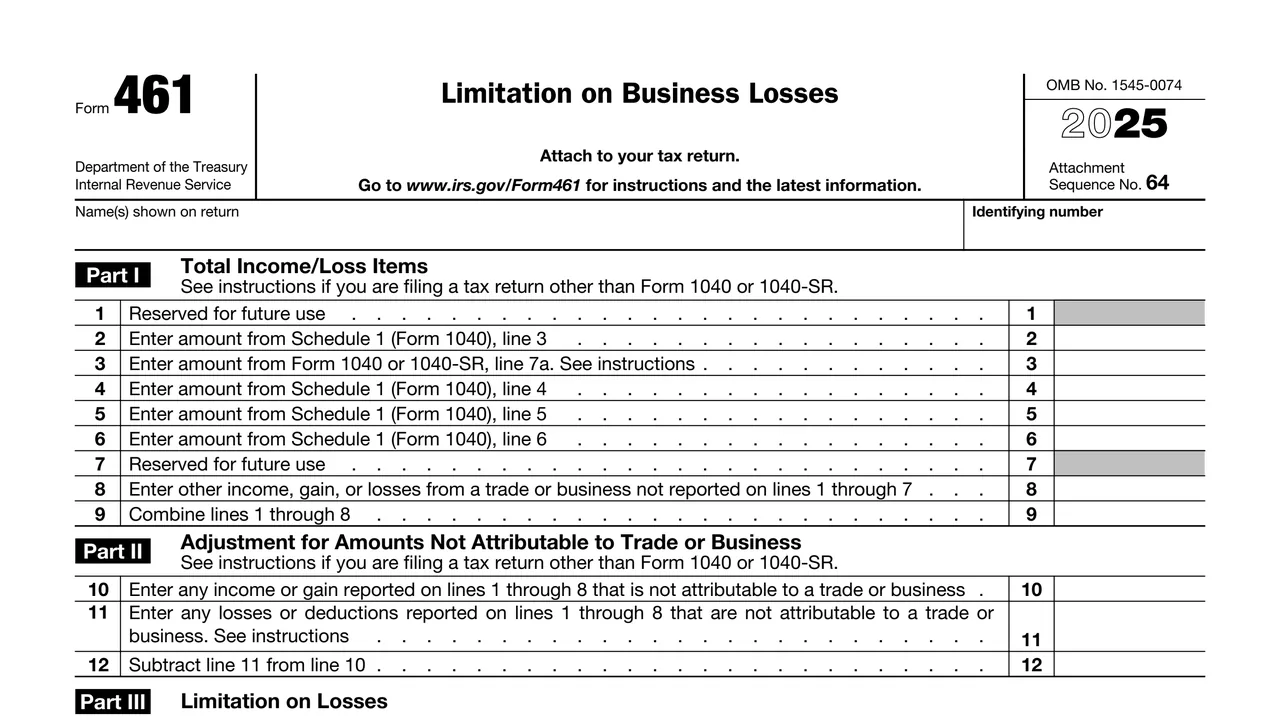
Income and loss items from the return: business income, capital gains, other gains, Schedule E income, farm income and other trade or business items, combined on line 9. Lines 1 and 7 are reserved.
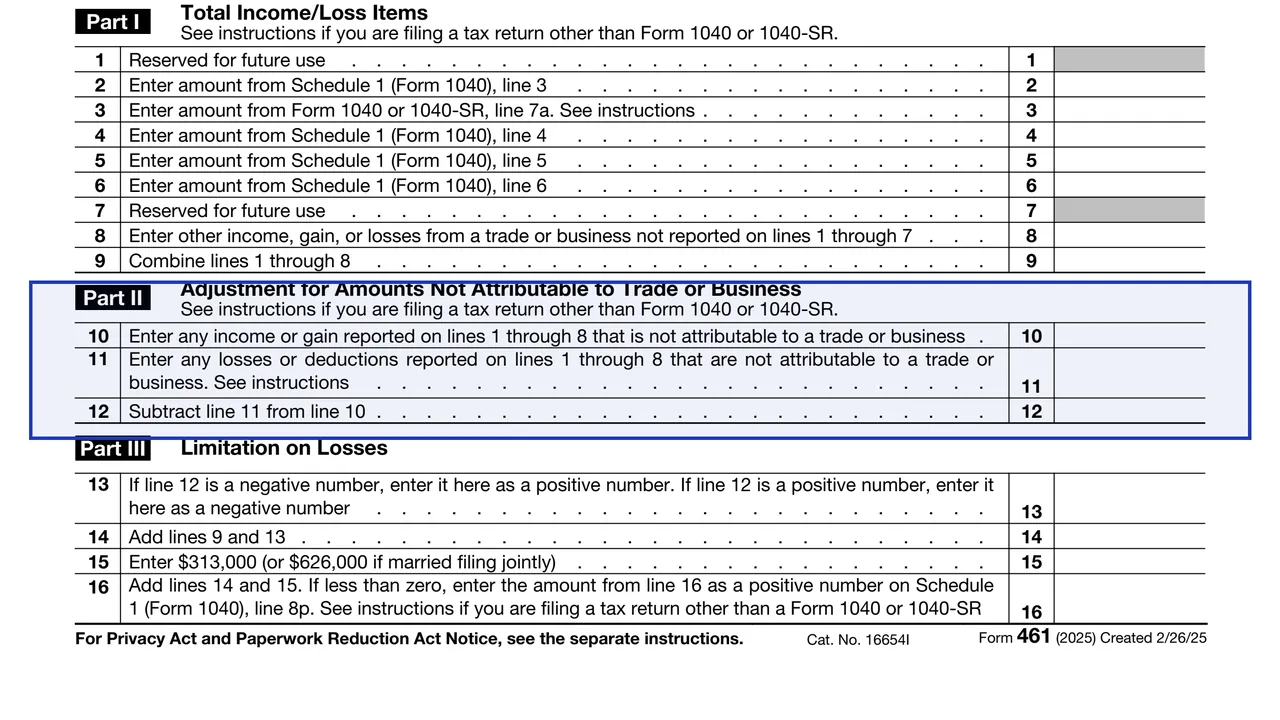
Income, gain, losses and deductions included in Part I that are not attributable to a trade or business, netted on line 12.
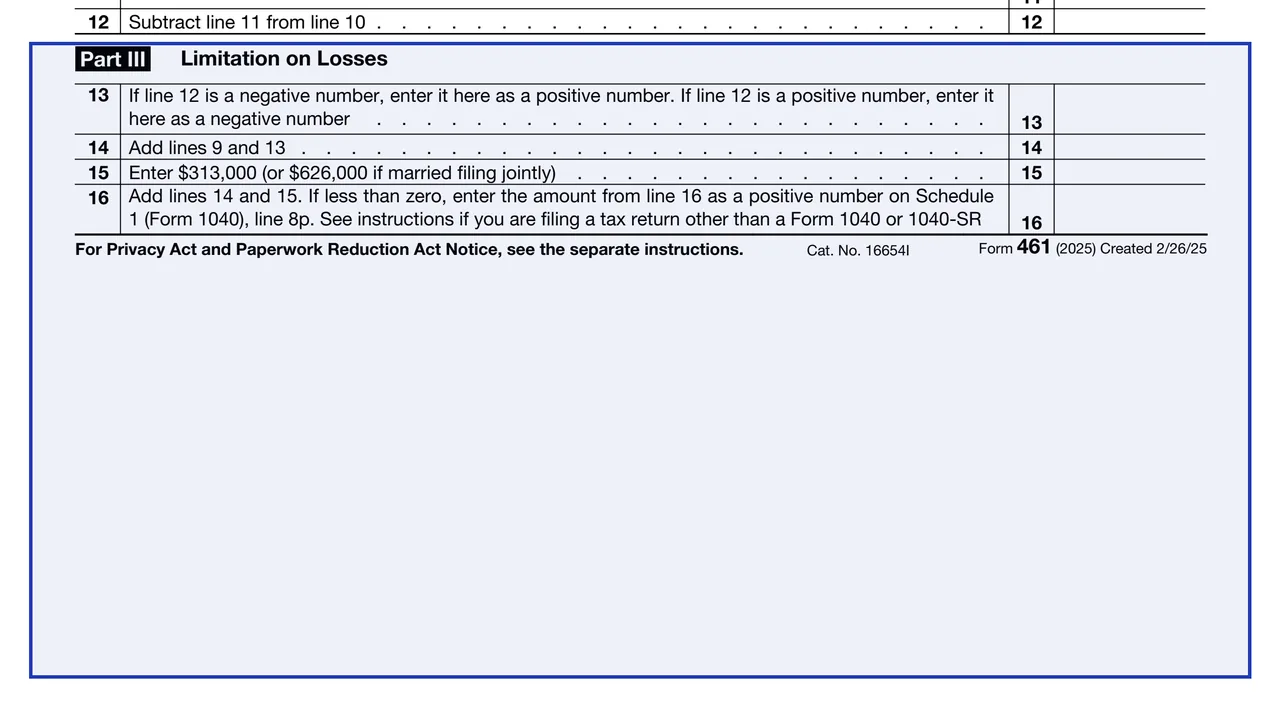
Line 12 entered with its sign reversed on line 13, then added to line 9 on line 14.
The form says "Enter $313,000 (or $626,000 if married filing jointly)."
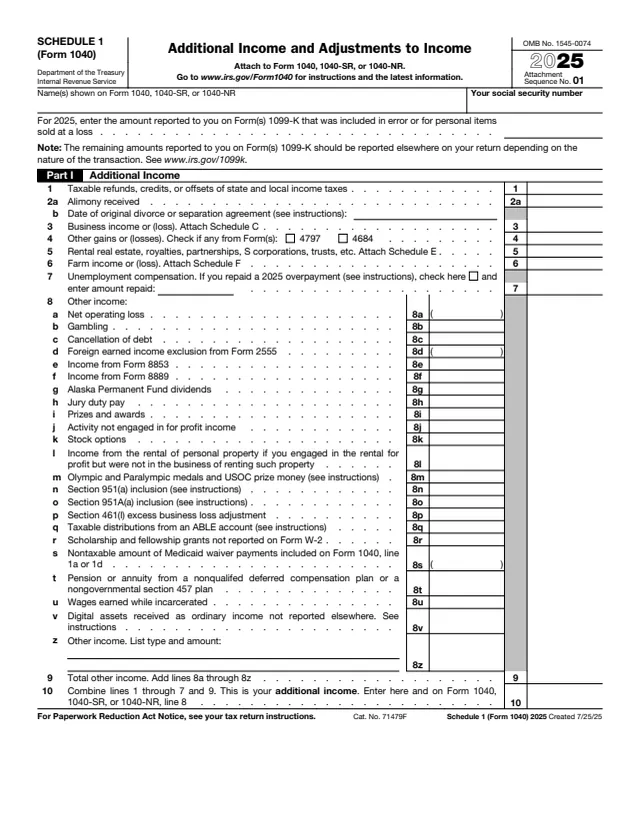
Lines 14 and 15 added. If less than zero, the amount goes as a positive number on Schedule 1 (Form 1040), line 8p.
The instructions say to leave both lines blank. The form marks them reserved for future use.
Enter amounts from Schedule 1 (Form 1040), lines 3, 4, 5 and 6, and from Form 1040 or 1040-SR, line 7a. Other returns use the equivalent lines the instructions list.
Enter other trade or business income, gain or loss not reported on lines 1 through 7, then combine lines 1 through 8. The result can be positive or negative.
Enter the income or gain, then the losses or deductions, from lines 1 through 8 that are not from a trade or business. Line 11 is a positive figure. Capital losses on line 3 are added back on line 11.
Subtract line 11 from line 10, reverse the sign on line 13, add lines 9 and 13 on line 14, and enter the threshold on line 15.
Add lines 14 and 15. The instructions say a negative result is the excess business loss, reported as a positive number on the Other income line with "ELA" on the dotted line.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to your tax return." It is Attachment Sequence No. 64.
The instructions say to attach Form 461 to any applicable amended returns.
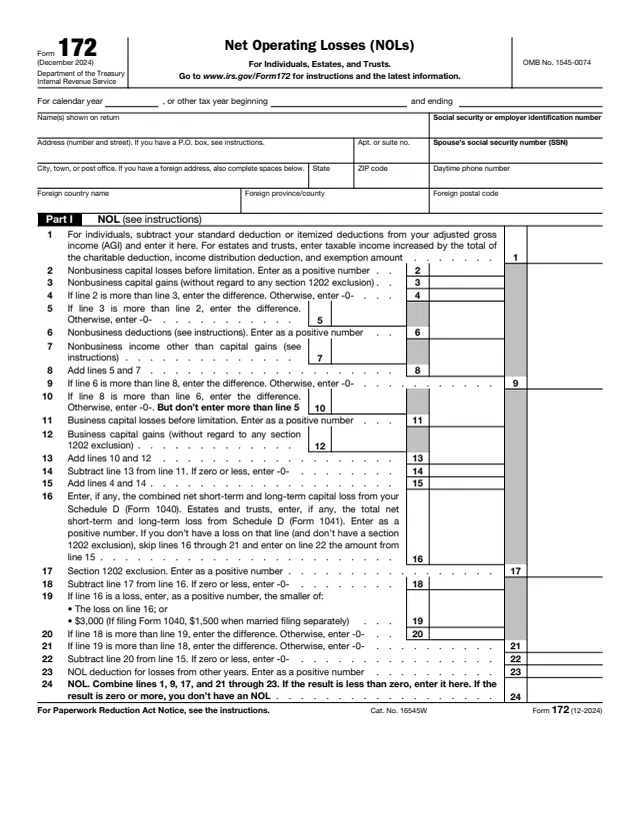
The instructions say to keep a record of each year's excess business loss because it is treated as an NOL carryover. They point to Form 172.
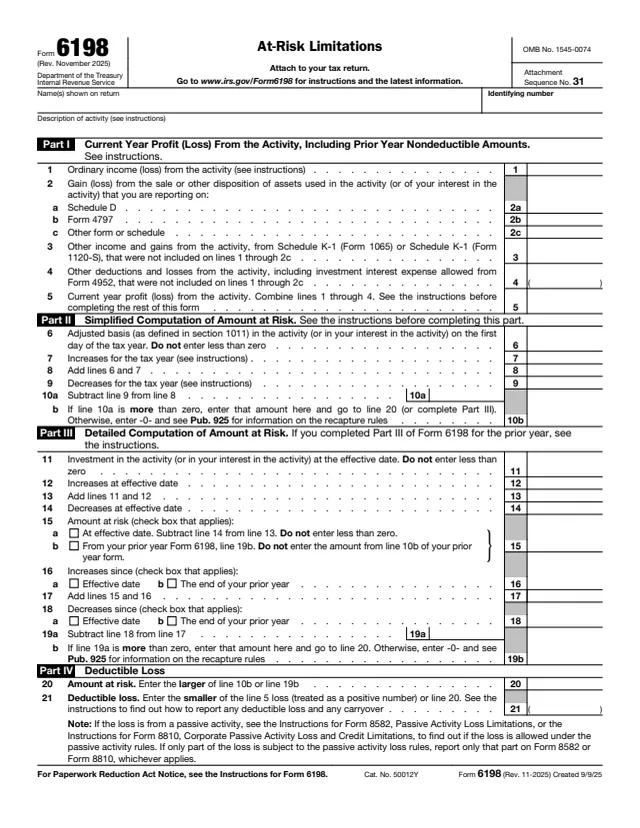
The instructions say to apply the at-risk rules first, then the passive activity loss rules, then the excess business loss rules. See Pub. 925.
The Other income line is Form 1041, line 8; Form 1041-QFT, Part II, line 4; Form 1041-N, Part II, line 4; or Schedule A (Form 990-T), Part I, line 12 for trusts.
172
109 fields, 3 pages
1040
73 fields, 2 pages

1040
199 fields, 2 pages

1041
173 fields, 3 pages
6198
34 fields, 1 page
1045
193 fields, 2 pages
Noncorporate taxpayers attach it to their own return when their business losses pass the thresholds in the instructions. The instructions say to follow their filing rules where they supersede those printed on the form.
No tool matches that search.
The instructions define it as the amount by which total deductions from your trades or businesses are more than your total gross income or gains from them, plus the threshold amount.
The instructions say $313,000, or $626,000 for taxpayers filing a joint return, citing Rev. Proc. 2024-40, Sec. 2.32.
The instructions say it can't be deducted in the current year but is treated as a net operating loss carryover for subsequent years.
As a positive number on the Other income line with "ELA" on the dotted line. On Schedule 1 (Form 1040), the instructions say line 8p.
One. The instructions say a joint return uses one Form 461 containing all the information for both spouses.
The instructions say losses from sales or exchanges of capital assets are not included in the total deductions from your trades or businesses.