Header and filing note
Name(s) shown on tax return, identifying number, and a note that generally the IRS will figure any penalty owed and send a bill.
2210-F
Underpayment of Estimated Tax by Farmers and Fishers
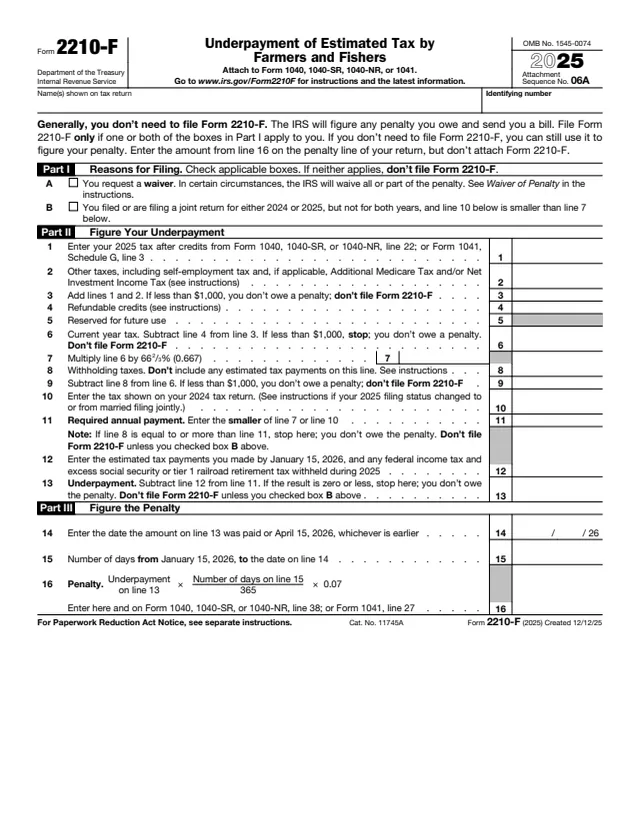
Form 2210-F is the 2025 IRS form individuals, estates and trusts with at least two-thirds of their 2024 or 2025 gross income from farming or fishing use to see if they owe a penalty for underpaying estimated tax. It attaches to Form 1040, 1040-SR, 1040-NR or 1041.
The form says that generally you don't need to file it, because the IRS will figure any penalty and send a bill. It is filed only when box A, a waiver request, or box B, a joint return for 2024 or 2025 but not both with line 10 smaller than line 7, applies. Without either box, it can still be used to figure the penalty, but it is not attached.
The form has three parts: reasons for filing, the underpayment based on payments made by January 15, 2026, and the penalty. You can fill out the PDF free in your browser on this page and download it without an account.
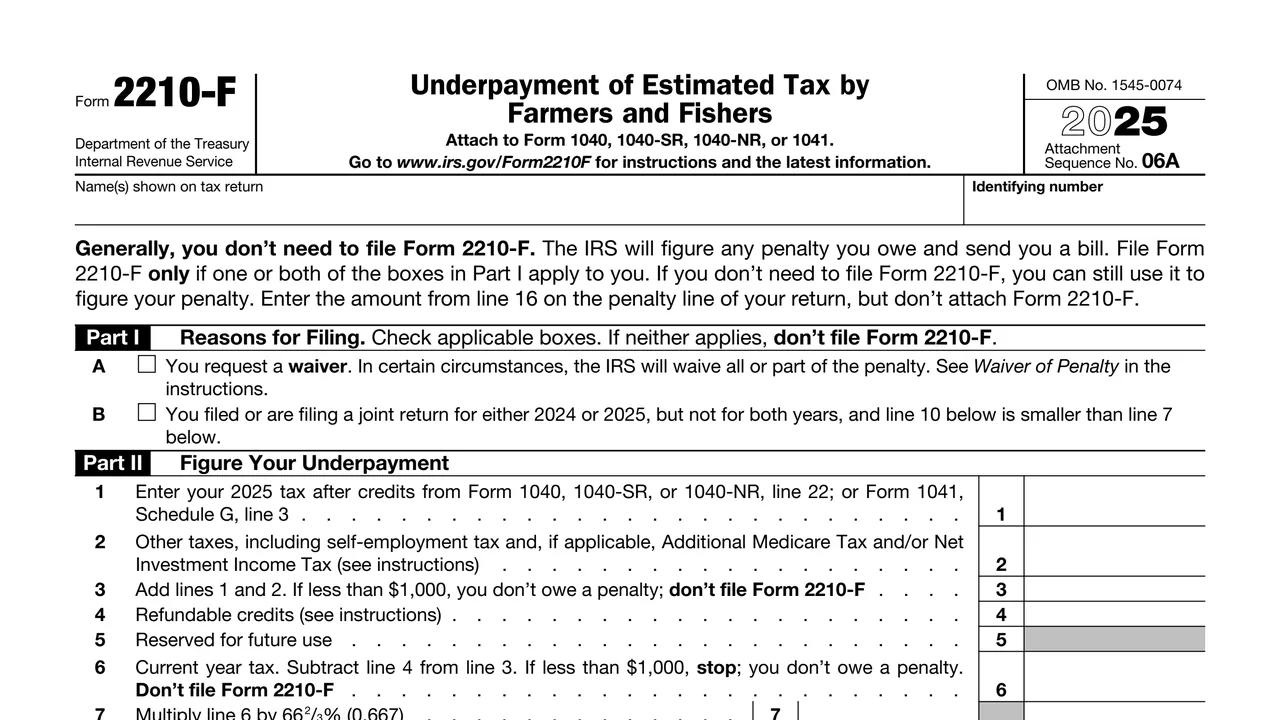
Name(s) shown on tax return, identifying number, and a note that generally the IRS will figure any penalty owed and send a bill.
Box A for a waiver request and box B for a joint return in only one of the two years. The form says that if neither applies, don't file Form 2210-F.
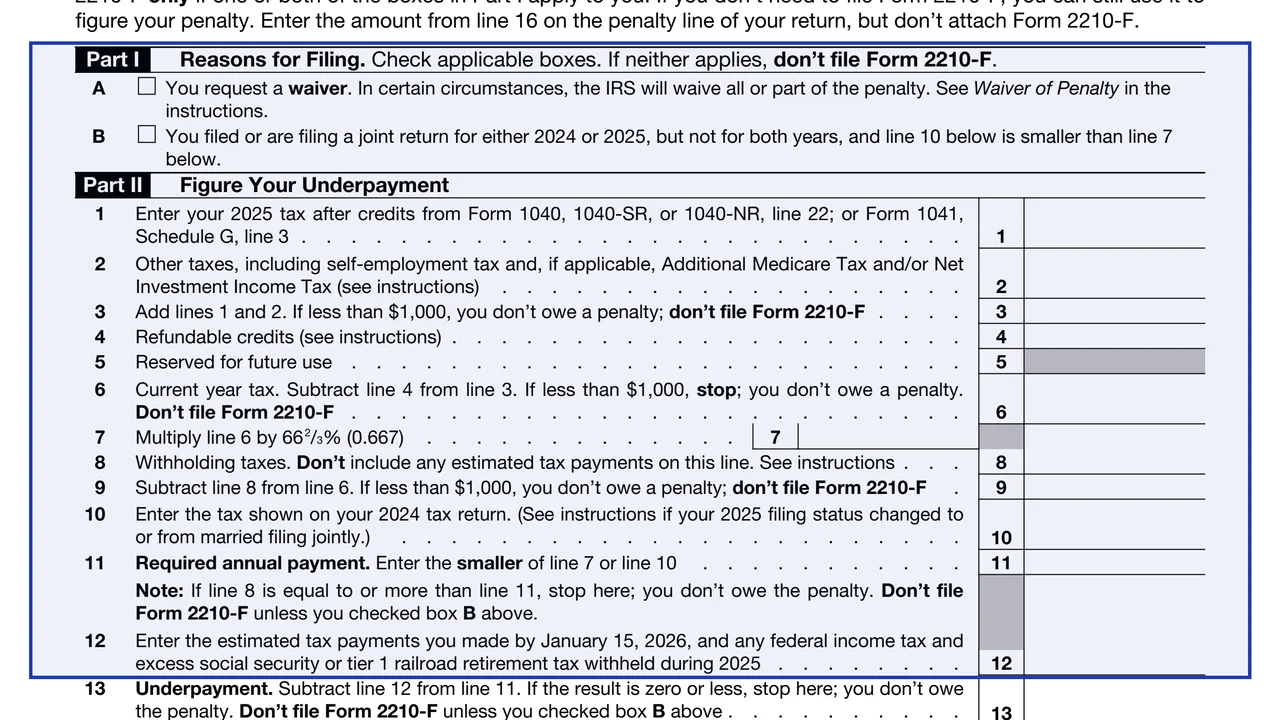
2025 tax after credits, other taxes such as self-employment tax, refundable credits and the current year tax. Line 5 is reserved for future use.
66 2/3% of the current year tax, withholding, the tax shown on the 2024 return, and the required annual payment, the smaller of lines 7 and 10.
Estimated tax payments made by January 15, 2026, plus 2025 withholding, and the underpayment.
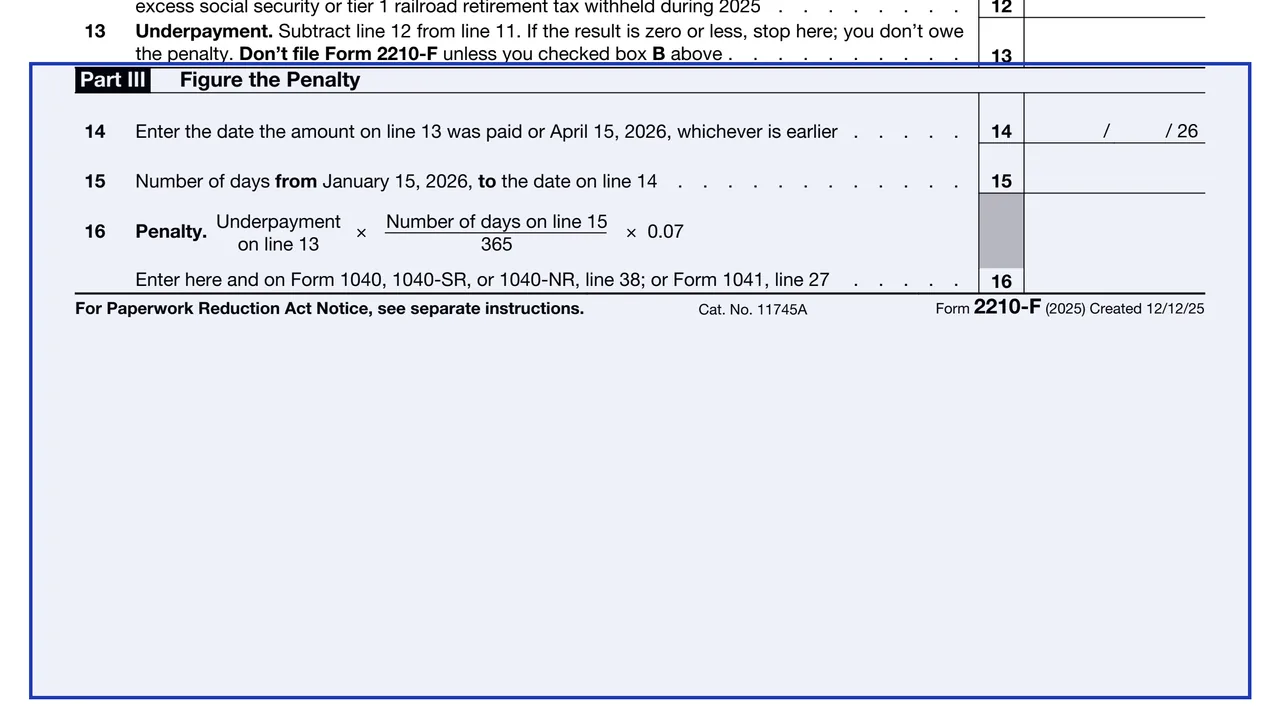
Lines 14 to 16: the date the underpayment was paid or April 15, 2026, whichever is earlier, the days from January 15, 2026, and the penalty at 0.07 times days over 365.
Check box A, box B or both if they apply. Without either, the form can still be used to figure the penalty, but it is not attached to the return.
Enter tax after credits, other taxes and refundable credits. The form says that if line 3 or line 6 is less than $1,000, you don't owe a penalty; don't file Form 2210-F.
Multiply line 6 by 66 2/3% (0.667) and enter withholding without estimated payments on line 8. The form says a line 9 below $1,000 means no penalty.
Enter the tax shown on the 2024 return, adjusted as the instructions explain if the filing status changed to or from married filing jointly. Line 11 is the smaller of line 7 or line 10.
Enter estimated payments made by January 15, 2026, and 2025 withholding, then subtract from line 11. The form says zero or less means no penalty.
Enter the payment date, or April 15, 2026, if earlier, count the days from January 15, 2026, and multiply the underpayment by those days over 365 and by 0.07.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 1040, 1040-SR, 1040-NR or 1041 when box A or B applies.
Line 16 goes on Form 1040, 1040-SR or 1040-NR, line 38, or Form 1041, line 27.
Without box A or B, the instructions say to leave the penalty line blank and not attach the form. Interest won't be charged on the penalty if it is paid by the date on the bill.
Enter the amount to be waived in parentheses next to line 16 and attach a statement with the reasons, plus documents such as police and insurance company reports for a casualty.
The instructions say not to file Form 2210-F if the underpayment was due to a federally declared disaster. Some eligible filers outside a covered area call the IRS disaster hotline at 866-562-5227.
2210
199 fields, 3 pages

1040
199 fields, 2 pages
1040-NR
171 fields, 2 pages

1041
173 fields, 3 pages
1040
63 fields, 2 pages
8962
141 fields, 2 pages
The IRS says individuals, estates, and trusts with at least two-thirds of their gross annual income from farming or fishing use this form.
No tool matches that search.
The instructions say individuals, estates and trusts with at least two-thirds of their 2024 or 2025 gross income from farming or fishing.
No. The form says the IRS will generally figure any penalty and send a bill, and to file the form only if box A or B in Part I applies.
Form 2210-F uses 66 2/3% of the current year tax, compares it with the tax on the 2024 return, and counts payments made by January 15, 2026.
The instructions list exceptions: the return is filed and the tax due paid by March 2, 2026; there was no 2024 tax liability for a full 12-month year; or 2025 tax minus withholding is less than $1,000.
Line 16 multiplies the underpayment by the number of days from January 15, 2026, to the payment date, divided by 365, and by 0.07.
The instructions say the IRS may waive the penalty if, in 2024 or 2025, the filer retired after reaching age 62 or became disabled and the underpayment was due to reasonable cause. Box A is checked and documentation attached.