Section I: Material Advisor Information
Name or entity name, first name, TIN, street address, city, state, ZIP, telephone number and person to contact.
13976
Itemized Statement Component of Advisee List
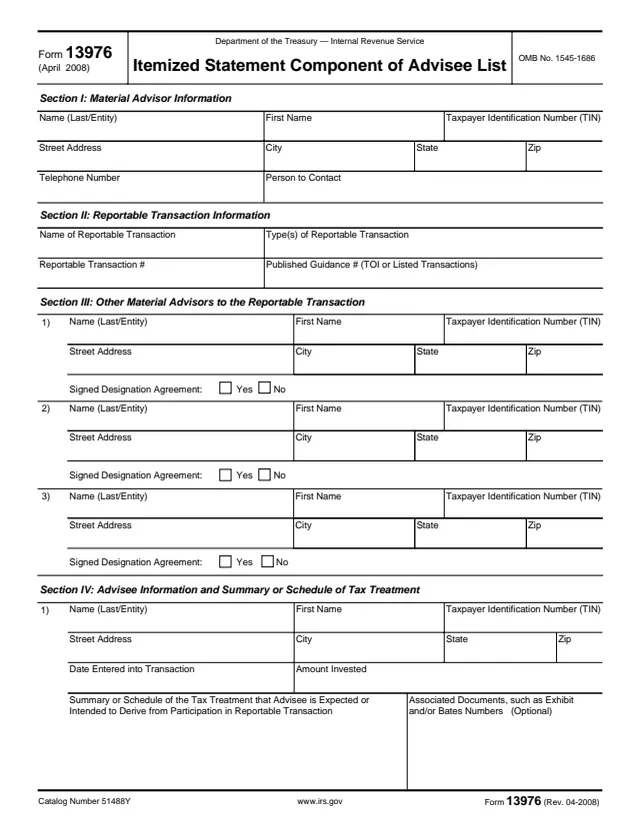
Form 13976, Itemized Statement Component of Advisee List, is a six-page IRS form for material advisors. The instructions say that, per Regulations section 301.6112-1(b)(1) and Rev. Proc. 2008-20, it provides material advisors a format for preparing and maintaining the itemized statement component of the list with respect to a reportable transaction.
The instructions also say the use of this form, or a similar form, is voluntary and is not required to comply with section 6112. Material advisors may use it as a template for a similar form, including a spreadsheet. The form records the material advisor, the reportable transaction, other material advisors, and each advisee with a summary or schedule of the tax treatment the advisee is expected or intended to derive.
The general and specific instructions are printed on pages 5 and 6. You can fill out Form 13976 free in your browser on this page and download it without an account.
Name or entity name, first name, TIN, street address, city, state, ZIP, telephone number and person to contact.
Name and type of the reportable transaction, the reportable transaction number and the published guidance number.
Three entries, each with name, TIN, address and a yes or no box for a signed designation agreement.
Eleven advisee entries across pages 1 to 4, each with name, TIN, address, date entered, amount invested, tax treatment and optional associated documents.
Page 4 explains the authority for the form, the 20 business day rule and the estimated burden.
Pages 5 and 6 hold the general instructions and the specific instructions for each section.
Enter the material advisor's details. An individual gives name, address, phone and SSN. An entity gives its name as on its income tax return, address, EIN and a contact person with phone.
Enter the transaction's name, if any, and its type. The instructions say not to report more than one type of reportable transaction unless the transactions are the same or substantially similar.
Enter the reportable transaction number if the transaction was disclosed under section 6111, and, for a listed transaction or transaction of interest, the published guidance that identified it.
List other material advisors, if known, with name, address and SSN or EIN if known, and mark yes or no for a designation agreement.
For each advisee, enter name, address, TIN, the date entered and amount invested if known, and a summary or schedule of the expected or intended tax treatment.
If space runs out, the instructions say to attach sheets in the same order as the lines, labeled with the Section they belong to and showing the advisor's name and identifying number at the top.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The Privacy Act notice says sections 6112 and 6708 require the information to be furnished within 20 business days after the IRS requests it in writing.
The instructions say the form may be provided along with a description of the transaction and copies of documents required under Regulations section 301.6112-1(b)(3)(ii) and (iii).
The notice says use of this form is optional, but providing the information requested is mandatory. A similar form or spreadsheet may be used instead.
The instructions say the form is complete only when filled in its entirety, including the tax treatment summary. A statement that information will be provided upon request is not complete.
The instructions say a designation of one material advisor does not relieve others of section 301.6112-1 if the IRS cannot obtain the list from the designated advisor or that list is missing or incomplete.
The form is kept by a material advisor. The advisees and other advisors are listed on it, not the people who complete it.
No tool matches that search.
The instructions say use of the form is voluntary and not required to comply with section 6112. The notice adds that providing the information requested is mandatory.
Yes. The instructions say material advisors may use the form as a template for a similar form, including a spreadsheet on their software.
The notice says within 20 business days after the IRS requests it in writing.
The instructions name listed transactions, confidential transactions, transactions with contractual protection, loss transactions and transactions of interest.
It is filled in its entirety, including a summary or schedule of the tax treatment for each advisee. A promise to provide information upon request is not enough, the instructions say.
No. The instructions say it is optional and may hold Bates numbers or other information identifying labeled documents for the advisee.