Material advisor and items A to C
Name, individual or entity, identifying number, phone and address; a contact person; whether this is a protective disclosure; and whether it is the original Form 8918 for the transaction.
8918
Material Advisor Disclosure Statement
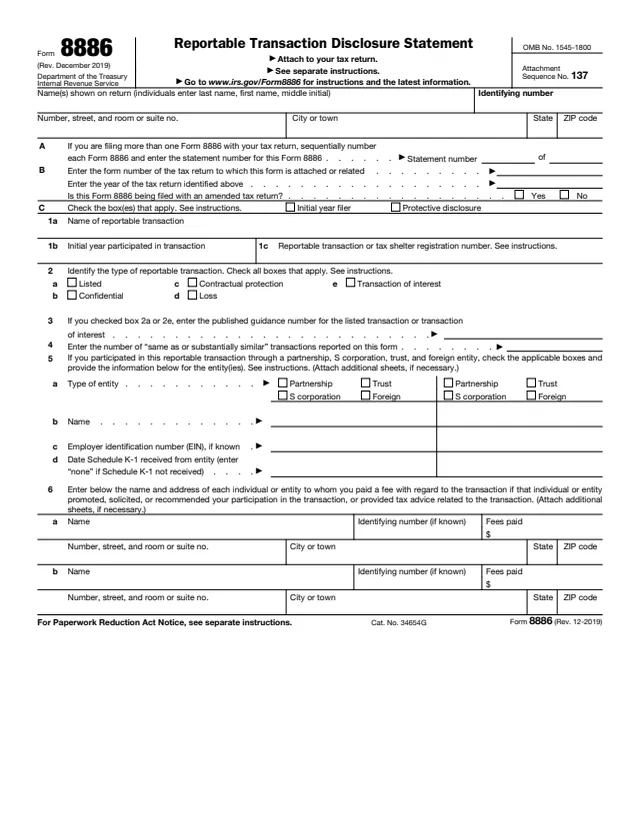
Form 8918 is the Material Advisor Disclosure Statement. The About page says material advisors to any reportable transaction file it to disclose certain information about the reportable transaction. It is filed by the advisor, not by the taxpayer who entered into the transaction: the instructions say every taxpayer who has participated in a reportable transaction also discloses it on Form 8886.
The instructions say material advisors who file Form 8918 receive a reportable transaction number from the IRS and provide it to the taxpayers and material advisors they advise. They also say Form 8918 replaces Form 8264, Application for Registration of a Tax Shelter.
The instructions say the IRS will reject forms filed incorrectly, that the form must not be handwritten, and that only the 2021 version is accepted after June 1, 2022. You can fill it out free in your browser on this page and download the result without an account.
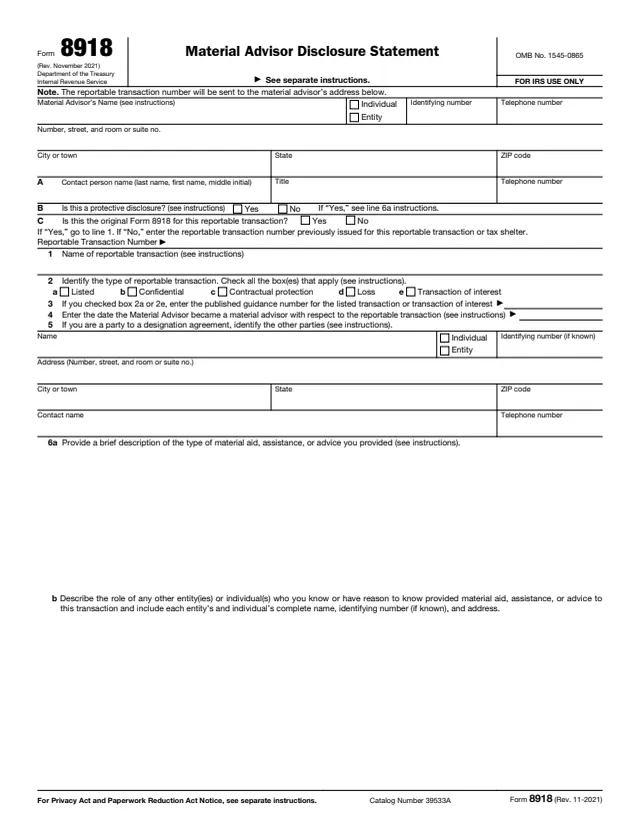
Name, individual or entity, identifying number, phone and address; a contact person; whether this is a protective disclosure; and whether it is the original Form 8918 for the transaction.
Name of the transaction, its type (listed, confidential, contractual protection, loss, transaction of interest), the published guidance number, and the date the advisor became a material advisor.
Other parties to a designation agreement, the material aid, assistance or advice provided, and the role of others who provided it.
Whether related, foreign or tax-exempt parties are needed, and whether income or gain is allocated to a party with a net operating loss or unused losses or credits.
Types of financial instruments, the expected tax benefits, when they are claimed, and the Internal Revenue Code sections used.
A description of the transaction and any tax result protection, signed by the material advisor under penalties of perjury.
An individual enters name, SSN, phone number and complete address. An entity enters its name as shown on its income tax return, its EIN and address, and a contact person at item A.
Check Yes on item B for a protective disclosure and explain why on line 6a. On item C, an amended statement answers No and enters the reportable transaction number previously provided.
Enter the transaction's name or a short identifying description, check every category that applies (including the listed box for a listed transaction), name the guidance on line 3, and enter on line 4 the latest of the dates the instructions list.
Identify any designation agreement parties, describe the advisor's role and others' roles, the parties the transaction needs, the financial instruments, the tax benefits and the code sections.
Describe all relevant facts, including the tax benefits, years affected, steps, purpose of each step and business reasons. The instructions say a statement that information will be provided upon request is not a complete disclosure.
The material advisor signs and dates the form and adds a printed name and title.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say it is filed with the Office of Tax Shelter Analysis (OTSA) by the last day of the month that follows the end of the calendar quarter in which the advisor became a material advisor, or in which an amended statement becomes required.
The instructions give the electronic fax number 1-844-253-5607 (this is toll-free), only for Form 8918 and related attachments, with a cover sheet and no more than 100 pages.
Without electronic fax, the instructions say to mail it to Internal Revenue Service, OTSA Mail Stop 4915, 1973 Rulon White Blvd., Ogden, Utah 84201. A receipt confirms the submission.
The instructions say the advisor provides it when the transaction is entered into, or, if it was entered into before the advisor received the number, within 60 calendar days from the date the number is mailed to the advisor. Receiving it does not mean the IRS reviewed or approved the transaction.
The instructions say a material advisor generally keeps a list for each reportable transaction for 7 years and furnishes it on the IRS's written request.
The instructions list $50,000 for reportable transactions other than listed transactions. For listed transactions, the greater of $200,000 or 50 percent of the gross income from the advice, and 75% if the failure is intentional.
The form is completed and signed by a material advisor and sent to the IRS Office of Tax Shelter Analysis. The instructions describe who that is.
No tool matches that search.
The material advisor files Form 8918. The instructions say taxpayers who participated in a reportable transaction disclose it on Form 8886.
The instructions say material advisors who file Form 8918 receive a reportable transaction number, which is sent to the material advisor's address on the form.
Yes. The instructions give 1-844-253-5607 (toll-free) for Form 8918 and related attachments, with a cover sheet that leaves out sensitive information such as an EIN or SSN.
The instructions say only the 2021 version is accepted after June 1, 2022, and that the form must not be handwritten.
The instructions say an advisor uncertain whether a transaction has to be disclosed can check Yes on item B, disclose the transaction and explain on line 6a why the disclosure is protective.
The instructions say such a statement is not considered a description and may cause the disclosure statement to be treated as incomplete.