Payer and recipient boxes
The payer's or trustee's name, address and phone number, both TINs, the recipient's name and address, and an account number.
1099-Q
Payments From Qualified Education Programs (Under Sections 529 and 530)
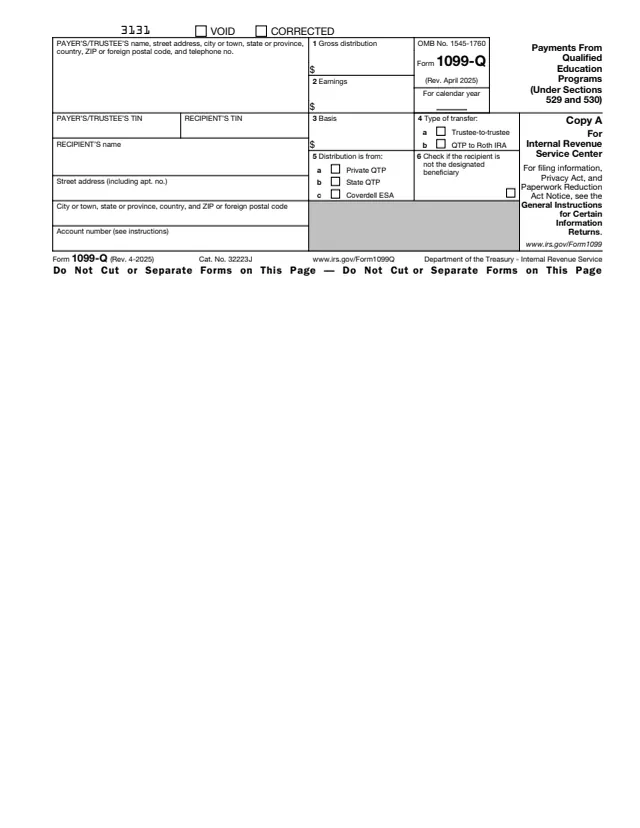
Form 1099-Q, Payments From Qualified Education Programs (Under Sections 529 and 530), is an information return that reports distributions from a qualified tuition program (QTP) under section 529 and from a Coverdell education savings account (ESA) under section 530. The IRS page says it is filed by an officer or employee, or the designee of an officer or employee, having control of a program established by a state or eligible educational institution, who made a distribution from a QTP. The instructions add that a trustee of a Coverdell ESA files it to report distributions from Coverdell ESAs.
The filer sends Copy A to the IRS and gives Copy B to the recipient, who is the designated beneficiary or the account owner depending on how the money was paid. Copy B carries the Instructions for Recipient, which explain each box and point to Pub. 970 and Form 5329.
The instructions say the form has been converted to an online fillable format because the IRS receives very few paper copies. You can fill out the PDF free in your browser on this page and download it without an account.
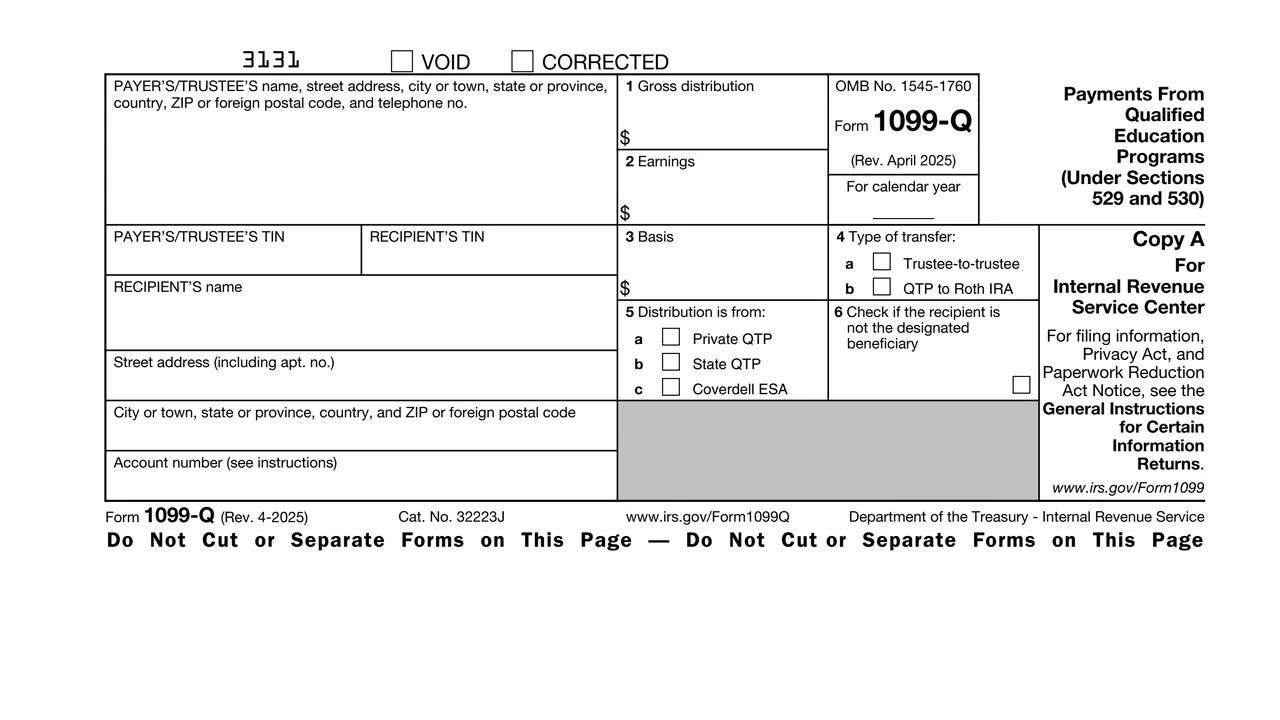
The payer's or trustee's name, address and phone number, both TINs, the recipient's name and address, and an account number.
Gross distribution, earnings and basis. Copy B says box 1 is the total of the amounts in boxes 2 and 3.
Type of transfer: 4a for a trustee-to-trustee transfer and 4b for a QTP to Roth IRA transfer. Box 4b is new in this revision.
Where the distribution came from: a private QTP, a state QTP or a Coverdell ESA.
A check box showing the recipient is not the designated beneficiary.
Copy B has a box 7 for the fair market value of a Coverdell ESA or an optional distribution code from 1 to 6.
For a QTP, enter the name and EIN of the QTP. A state program using the state's EIN puts the state on the first name line and the program on the second. For a Coverdell ESA, enter the trustee's name and EIN.
Enter the recipient chosen under the rules above and that person's TIN. The account number is required when one recipient has several accounts with more than one Form 1099-Q.
Enter the gross distribution, cash or in-kind. If Coverdell ESA earnings and basis are not reported, leave boxes 2 and 3 blank and report the year-end FMV in box 7, labeled FMV.
Enter the earnings using the earnings ratio the instructions cite. Enter a loss only in the final year of distributions, otherwise zero. The instructions say box 3 equals box 1 minus box 2.
Check 4a for a direct transfer between QTPs, from a QTP to an ABLE account, or from a Coverdell ESA to another ESA or a QTP. Check 4b for a direct QTP to Roth IRA transfer. Check one of 5a to 5c, and box 6 if needed.
The instructions say you may, but are not required to, enter a code in box 7: 1 distributions, 2 or 3 excess contributions plus earnings, 4 disability, 5 death, 6 prohibited transaction.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say a filer with few recipients filing on paper can send the black-and-white Copy A with a Form 1096 also printed from the IRS website.
The instructions say the e-file threshold was lowered to 10 returns, counted across all information returns, for returns required to be filed on or after January 1, 2024. IRIS is the IRS online portal for e-filing information returns.
A filer of Form 1099-Q also furnishes a copy of the form or an acceptable substitute statement to each recipient.
The recipient's TIN may be truncated on payee statements but not on documents filed with the IRS. The payer's or trustee's TIN may not be truncated on any form.
In a trustee-to-trustee transfer, the instructions say the distributing program gives a statement of the earnings portion within 30 days of the distribution or by January 10, whichever is earlier.
The instructions point to the General Instructions for Certain Information Returns for who files, when and where to file, corrections and penalties.
1096
55 fields, 3 pages
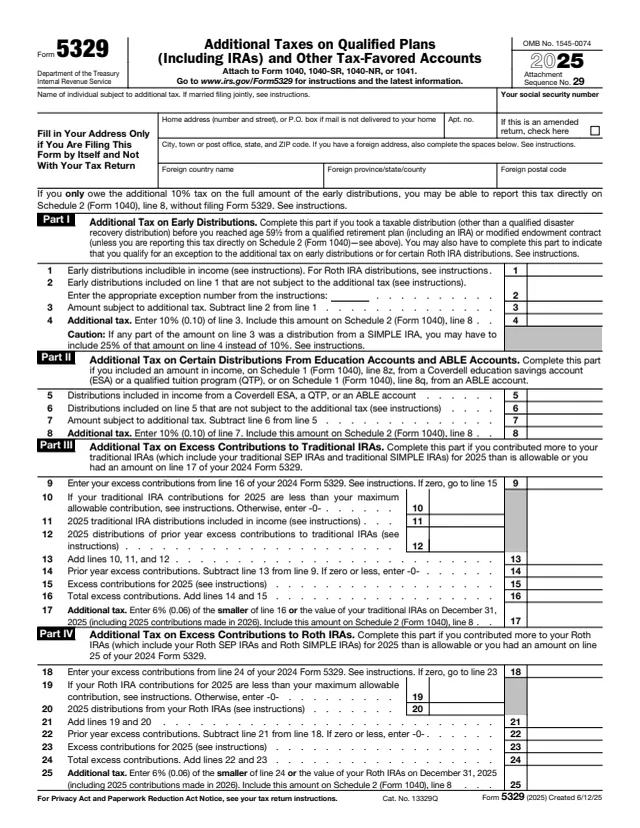
5329
75 fields, 3 pages

1040
199 fields, 2 pages
1099-QA
31 fields, 3 pages
1099-R
257 fields, 9 pages
1099-SA
33 fields, 3 pages
The program or trustee that made the distribution completes and files the form. The recipient gets a copy and does not file it with the IRS.
No tool matches that search.
Copy B says it shows a distribution paid to you during the year from a QTP or a Coverdell ESA. Box 1 is the gross distribution, including in-kind distributions.
Copy B says distributions from these accounts, including rollovers, may be taxable, and that nontaxable distributions are not required to be reported on an income tax return. It points to Pub. 970 and the Instructions for Forms 1040 and 1040-SR.
For a Coverdell ESA, the designated beneficiary. For a QTP, the beneficiary when paid to them, to a school for them or to a Roth IRA for them; otherwise the account owner.
The instructions say box 4b is checked when the distribution was made directly, trustee-to-trustee, from a QTP to a Roth IRA maintained for the benefit of the QTP beneficiary.
For Coverdell ESA distributions, Copy B says the payer or trustee may report the account's fair market value as of December 31 in box 7 instead. Pub. 970 has a worksheet to figure earnings and basis.
Copy B says an additional 10% tax may apply to part or all of an amount included in income from the CESA or QTP, and points to Form 5329.
Copy B says the form may show only the last four digits of your TIN for your protection, but the payer or trustee has reported your complete TIN to the IRS.