Corporation and shareholder boxes
The corporation's name, address and telephone number, the corporation's TIN, the shareholder's TIN, name and address, and an account number.
1099-CAP
Changes in Corporate Control and Capital Structure
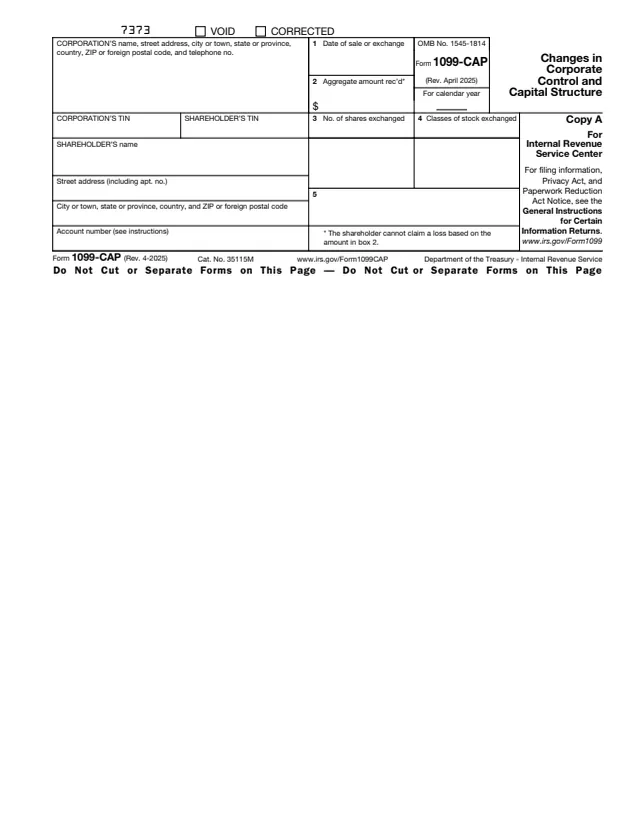
Form 1099-CAP, Changes in Corporate Control and Capital Structure, is an information return. The IRS About page says to file this form for shareholders of a corporation if control of the corporation was acquired or it underwent a substantial change in capital structure, and that it is furnished to shareholders who receive cash, stock, or other property from the acquisition of control or substantial change in capital structure.
The corporation files Copy A with the IRS and gives Copy B to the shareholder. The form shows the date of sale or exchange, the aggregate amount received, the number of shares exchanged and the classes of stock exchanged. A note on the form says the shareholder cannot claim a loss based on the amount in box 2.
This page hosts the April 2025 revision, which the instructions say is used for tax year 2025 and later years until a superseding revision is issued. The instructions say that because of the very low volume of paper Forms 1099-CAP, the form was converted to an online fillable format, and a low-volume paper filer may send the black-and-white Copy A with a Form 1096 printed from the IRS website. You can fill it out free in your browser on this page and download it without an account.
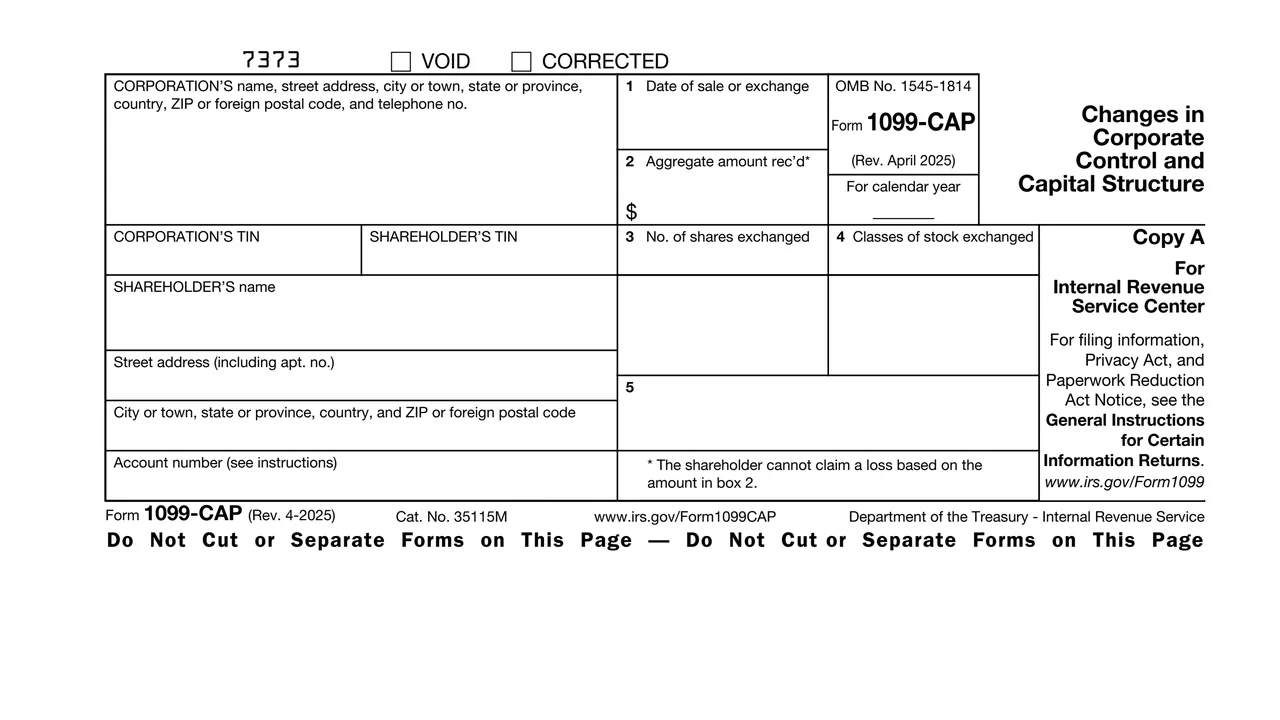
The corporation's name, address and telephone number, the corporation's TIN, the shareholder's TIN, name and address, and an account number.
The form says this shows the date the stock was exchanged for cash, stock or other property.
The aggregate amount of any cash and the fair market value of any stock or other property received for the stock held. A note says no loss can be claimed based on this amount.
The number of the corporation's shares that were exchanged in the transaction, and the class or classes of stock exchanged.
Enter the corporation's name, address, telephone number and federal identification number. The instructions say this is generally the reporting corporation's information and EIN.
The account number is required when there are multiple accounts for a recipient with more than one Form 1099-CAP. The instructions say the IRS encourages an account number on all of them.
Enter the trade date of the sale or exchange, actually or constructively received.
Enter the aggregate amount of cash and the FMV of any stock and other property received in exchange for the number of shares exchanged in the reporting corporation.
Enter the number of shares the shareholder exchanged and the class or classes of stock, abbreviated to fit, for example C for common stock, P for preferred or O for other.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Copy A goes to the IRS and Copy B goes to the shareholder. The form says the corporation sends the shareholder statement by January 31 of the year following the calendar year of the change.
The instructions say to furnish Form 1099-CAP to a clearing organization by January 6, 2025, and in later years by January 5th of the year following the calendar year in which the transaction took place.
The instructions say the e-file threshold is 10 information returns in the aggregate, and point to IRS.gov/IRIS. A low-volume paper filer may send the black-and-white Copy A with a Form 1096 printed from the IRS website.
The instructions say Form 8806 and all Forms 1099-CAP count as one return for the section 6652(l) penalty, which will not exceed $500 for each day the failure continues, up to a maximum of $100,000.
The instructions list cases where a corporation does not file, such as an acquisition within an affiliated group, stock valued at less than $100 million, the consent election on Form 8806, or a transaction reported on Form 966.
8806
38 fields, 4 pages
1099-B
207 fields, 7 pages
1096
55 fields, 3 pages
8949
202 fields, 2 pages
966
29 fields, 2 pages
1099-DIV
140 fields, 6 pages
A domestic corporation completes and files the form and sends Copy B to its shareholders. The shareholder copy is marked "keep for your records."
No tool matches that search.
The instructions say a domestic corporation that is required to file Form 8806 files Form 1099-CAP with the IRS and furnishes a copy to each shareholder who receives cash, stock or other property and is not an exempt recipient.
The form says the shareholder cannot claim a loss based on the amount in box 2. Its shareholder instructions say to report any gain from the exchange on Form 8949 and point to chapter 4 of Pub. 550.
The form says the corporation sends the statement by January 31 of the year following the calendar year of the change in control or capital structure.
In part, the instructions describe a second corporation gaining control of a first corporation where the stock acquired is worth $100 million or more and gain must be recognized under section 367(a). Control means at least 50% of the voting power or of the value of all classes of stock.
The corporation files Form 1099-CAP. The instructions say a broker holding the shares for a customer files Form 1099-B for the same kind of transaction, unless the customer is an exempt recipient.
The instructions say that for this form only, a filer sending paper forms due to a low volume of recipients may send the black-and-white Copy A with a Form 1096 printed from the IRS website. Filers of 10 or more forms follow their usual e-filing procedures.