Part I: reporting corporation
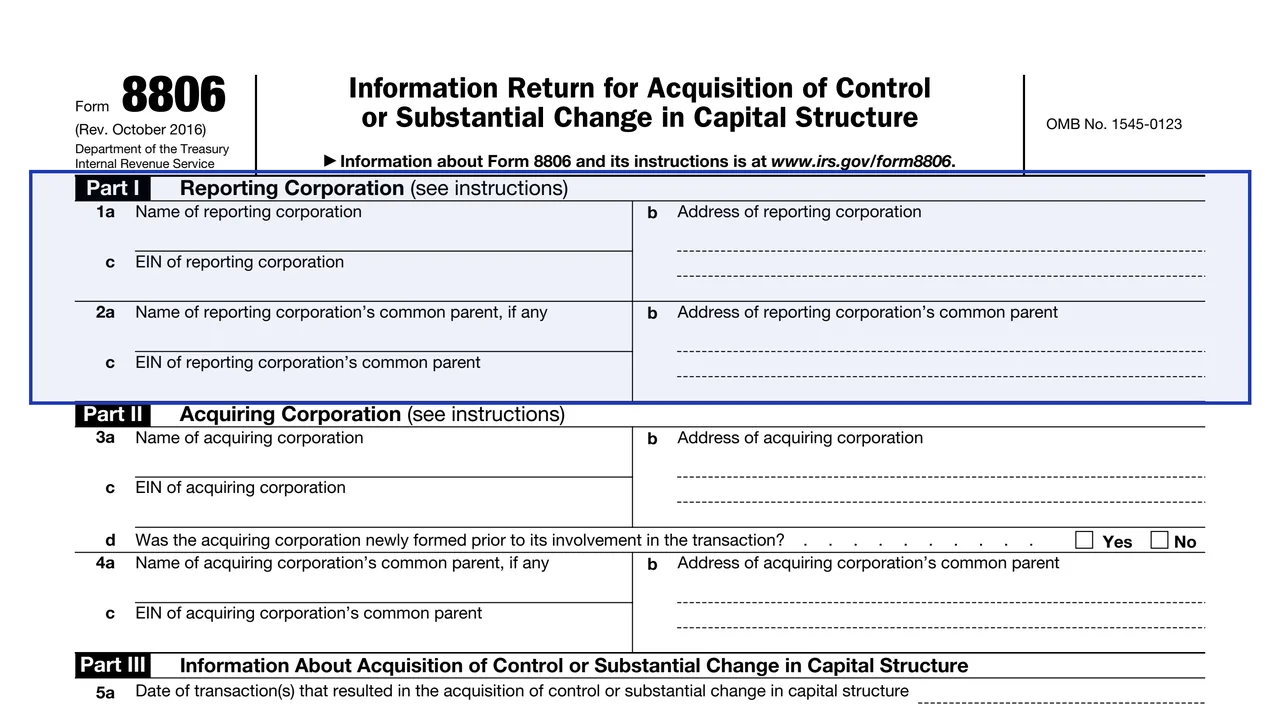
Lines 1a to 1c for its name, address and EIN, and lines 2a to 2c for its common parent, if any.
8806
Information Return for Acquisition of Control or Substantial Change in Capital Structure
Form 8806, Information Return for Acquisition of Control or Substantial Change in Capital Structure, is filed by a corporation. The IRS page says a reporting corporation files it to report an acquisition of control or a substantial change in the capital structure of a domestic corporation. The instructions add that the filing applies when the reporting corporation or any shareholder is required to recognize gain (if any) under section 367(a) as a result of the transaction.
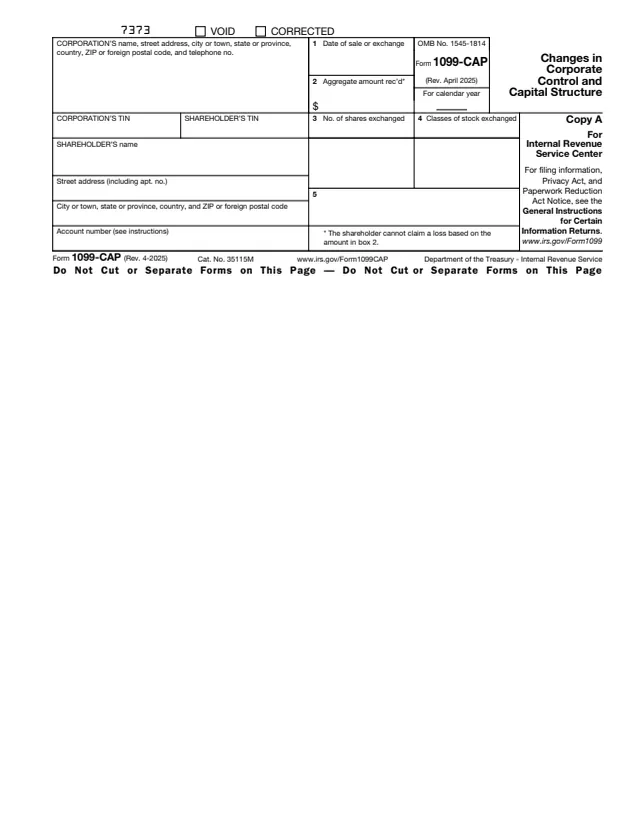
The form identifies the reporting corporation and the acquiring corporation, describes the transaction, and asks whether the corporation consents to the IRS publishing certain details to help brokers with their own reporting. A corporation that files Form 8806 also files Form 1099-CAP for certain shareholders.
The PDF opens with a coversheet saying that, until further notice, Form 8806 is sent to the IRS by fax and can no longer be mailed. The instructions are on pages 2 and 3. You can fill out the PDF free in your browser on this page and download it without an account.
Lines 1a to 1c for its name, address and EIN, and lines 2a to 2c for its common parent, if any.
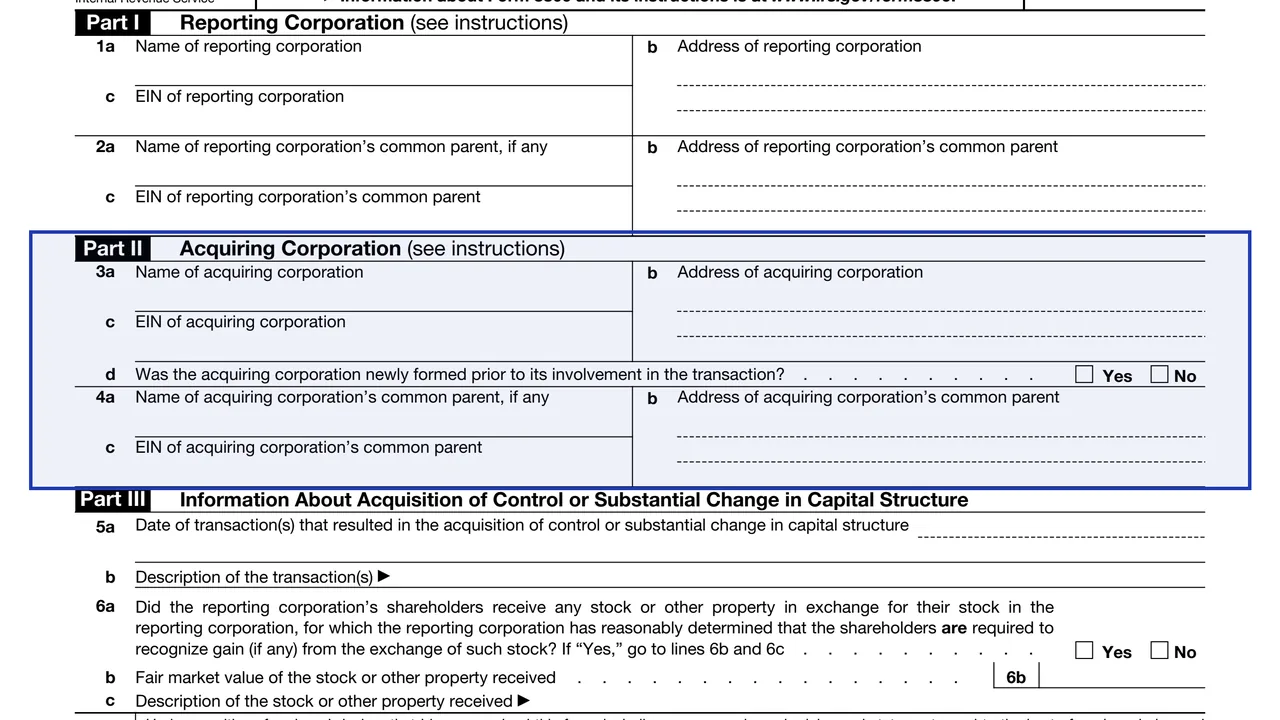
Lines 3a to 3c for its name, address and EIN, line 3d asking whether it was newly formed before the transaction, and lines 4a to 4c for its common parent.
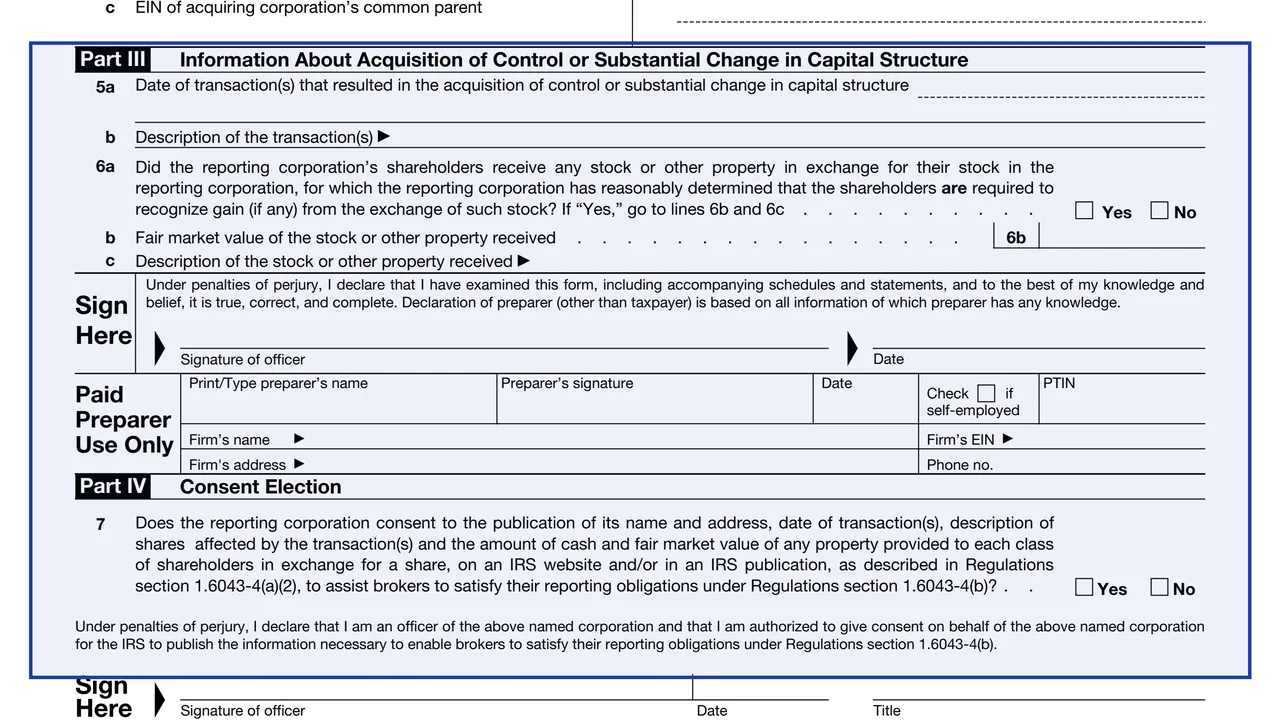
Line 5 for the date and a description of the transaction. Line 6 asks whether shareholders received stock or other property and, if so, its fair market value and description.
The officer's signature and date, and the paid preparer's name, signature, PTIN, firm name, firm EIN, address and phone.
Line 7 asks whether the corporation consents to the IRS publishing its name, address, transaction date, shares affected and amounts paid per share, with a separate officer signature.
Enter each corporation's name, address and EIN. The instructions say an EIN is not required if the corporation does not have, and is not otherwise required to have, one.
Complete lines 2a and 2b if the reporting corporation was a subsidiary member of a consolidated group just before the transaction, and lines 4a and 4b for the acquiring corporation's group.
Enter the transaction date and description. Answer line 6a, and if the answer is Yes, give the fair market value and a description of the stock or property received.
Check Yes or No on line 7. The instructions say corporations that consent are not required to file Form 1099-CAP for shareholders that are clearing organizations.
An officer signs and dates the return, and a paid preparer completes their section if one was used. An officer also signs Part IV.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The coversheet says submissions of Form 8806 are now sent to the IRS by fax and the form can no longer be mailed. Fax Form 8806 to: 844-249-6232. The IRS page lists this as a recent development dated 25-JUL-2022.
Page 2 still prints a Washington, DC mailing address for the Large Business and International Division, but the coversheet says the form can no longer be mailed.
The instructions say to file within 45 days after the transaction, or if earlier by January 5th of the year following the calendar year in which it occurred.
If a correct Form 8806 is not filed by the due date of the corporation's income tax return, including extensions, the instructions say it may be penalized $500 for each day, up to $100,000, unless due to reasonable cause.
A corporation filing Form 8806 also files Form 1099-CAP for certain shareholders of record who receive cash or other property for their stock.
This is a corporate information return. It is signed by an officer of the corporation, and a paid preparer section is included.
No tool matches that search.
The reporting corporation. If it transfers substantially all of its assets in a substantial change in capital structure and does not file, the instructions say the acquiring corporation files.
No. The coversheet on the PDF says it is sent by fax to 844-249-6232 and can no longer be mailed.
The instructions say control means owning stock with at least 50% of the total combined voting power of all voting classes, or at least 50% of the total value of all classes of stock.
The instructions use $100 million or more: the fair market value of stock acquired for an acquisition of control, or the cash and property provided to shareholders for a substantial change in capital structure.
It lets the IRS publish limited details of the transaction on its website or in a publication, to help brokers meet their reporting obligations under Regulations section 1.6043-4(b).
The instructions say a corporation required to file Form 8806 also files Form 1099-CAP for certain shareholders, and that the two are treated as one return for the failure to file penalty.