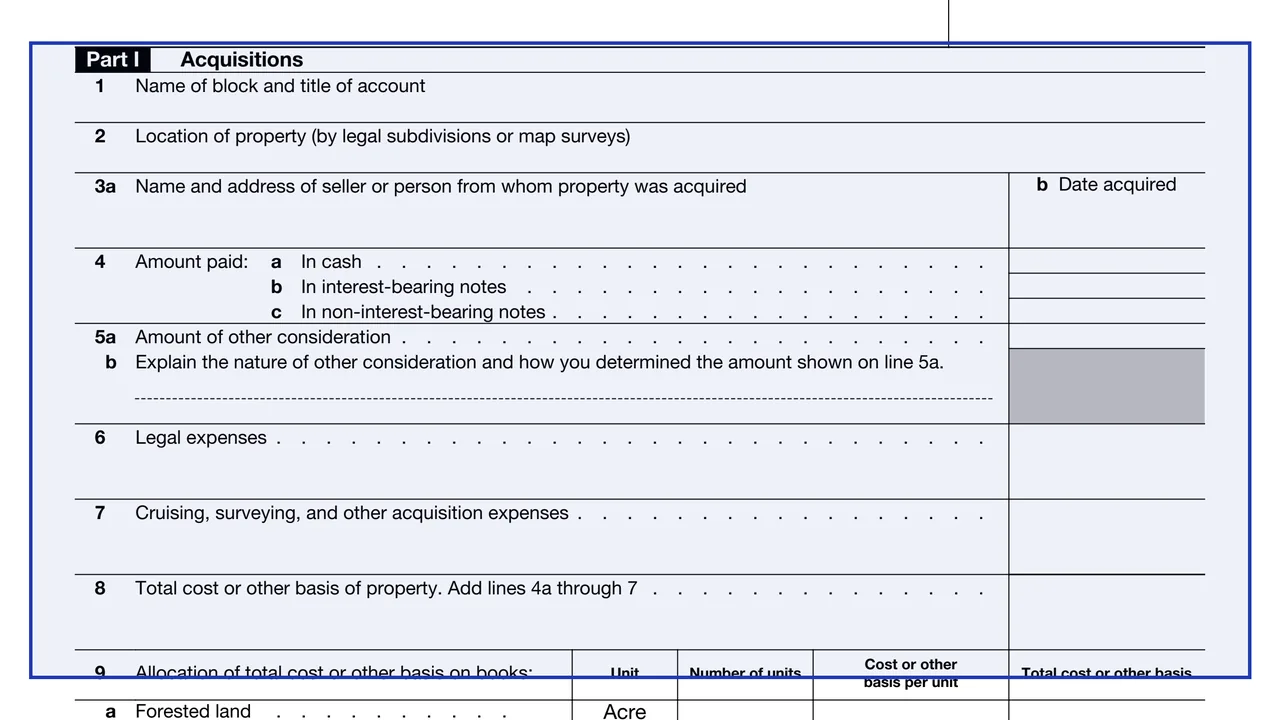
Part I: Acquisitions
Block and account name, location, seller, date acquired, amounts paid in cash and notes, other consideration, legal and cruising expenses, and line 9's allocation of cost among land, timber, improvements and mineral rights.
T
Forest Activities Schedule
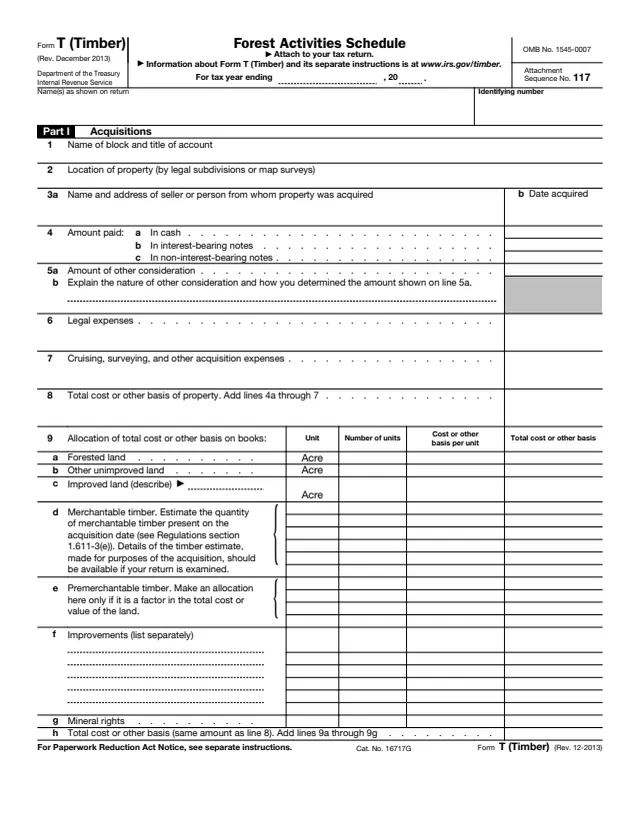
Form T (Timber), Forest Activities Schedule, is a four-page schedule attached to an income tax return. The IRS About page says it is used to provide information on timber accounts when a sale or deemed sale under Internal Revenue Code sections 631(a), 631(b), or other exchange has occurred during the tax year.
The instructions say to complete and attach Form T only when the filer claims a deduction for depletion of timber, elects under section 631(a) to treat the cutting of timber as a sale or exchange, or makes an outright sale of timber under section 631(b). They also say it is not required for an occasional sale of timber (one or two sales every 3 or 4 years).
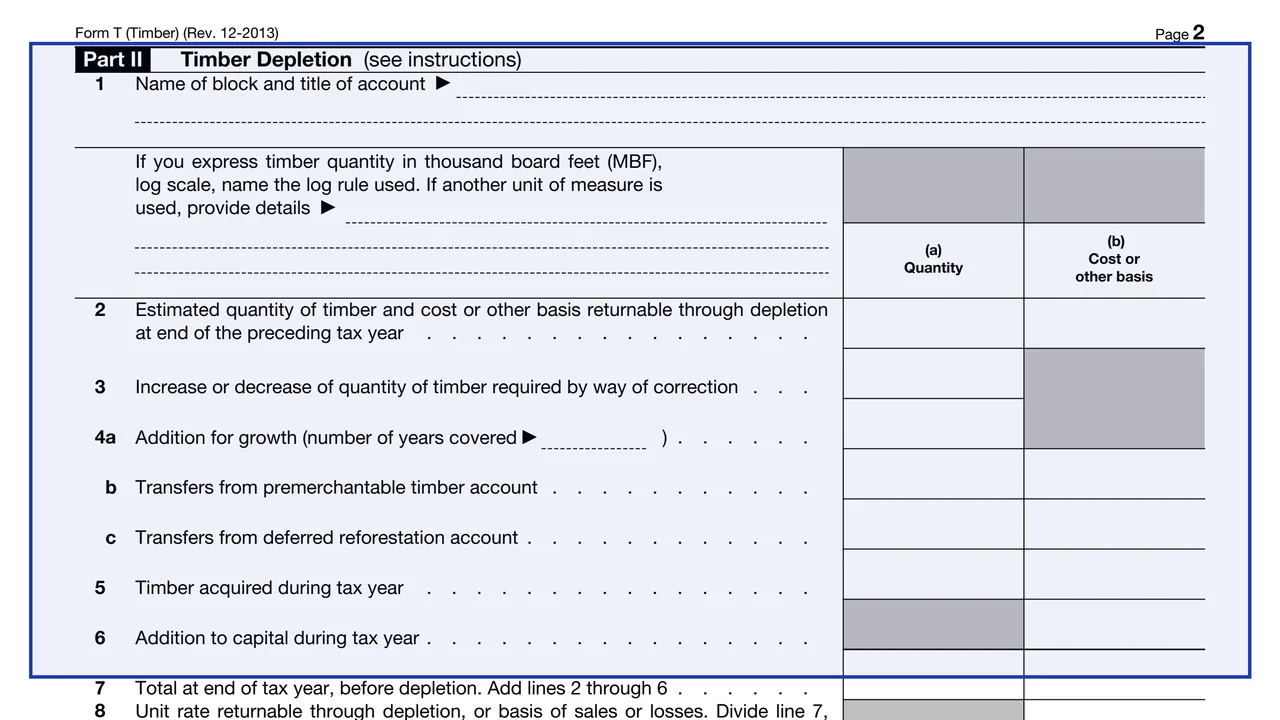
The form has five parts: acquisitions, timber depletion, profit or loss from land and timber sales, reforestation and timber stand activities, and land ownership. You can fill out Form T free in your browser on this page and download it without an account.
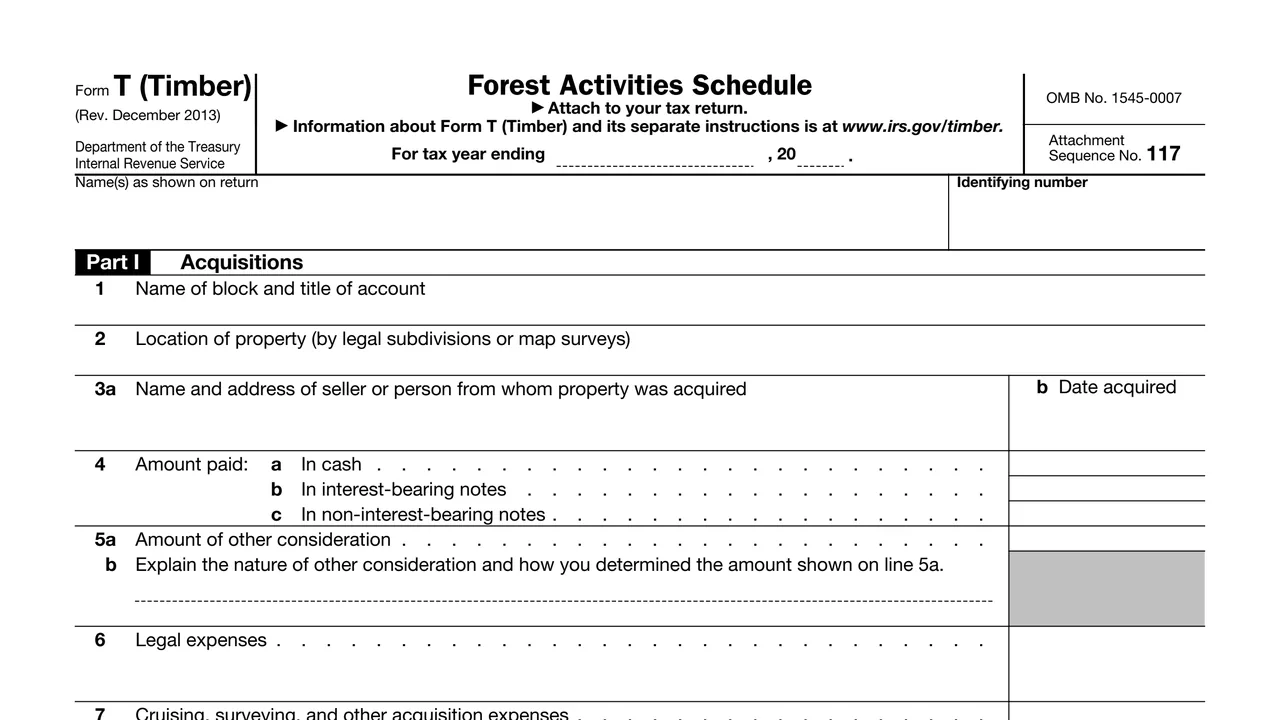
Block and account name, location, seller, date acquired, amounts paid in cash and notes, other consideration, legal and cruising expenses, and line 9's allocation of cost among land, timber, improvements and mineral rights.
Lines 2 to 16 track each timber account's quantity in column (a) and cost or other basis in column (b), giving the unit rate, depletion for timber cut, and basis of timber sold or lost.
Line 17 asks for cut timber sold as logs or other rough products. Line 18a asks about a section 631(a) election and line 18b about revoking it, with an effective date.
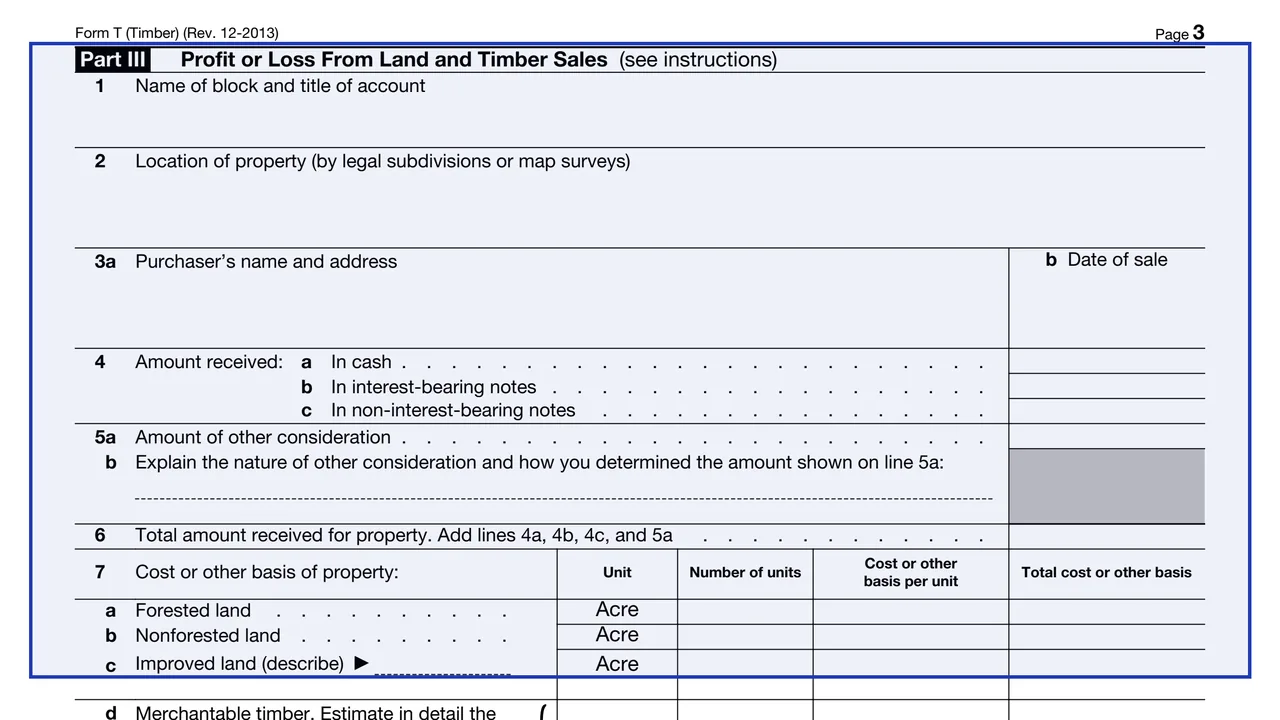
Purchaser, date of sale, amounts received, cost or other basis by category, direct sale expenses for cruising, marking and selling, and the profit or loss on line 8.
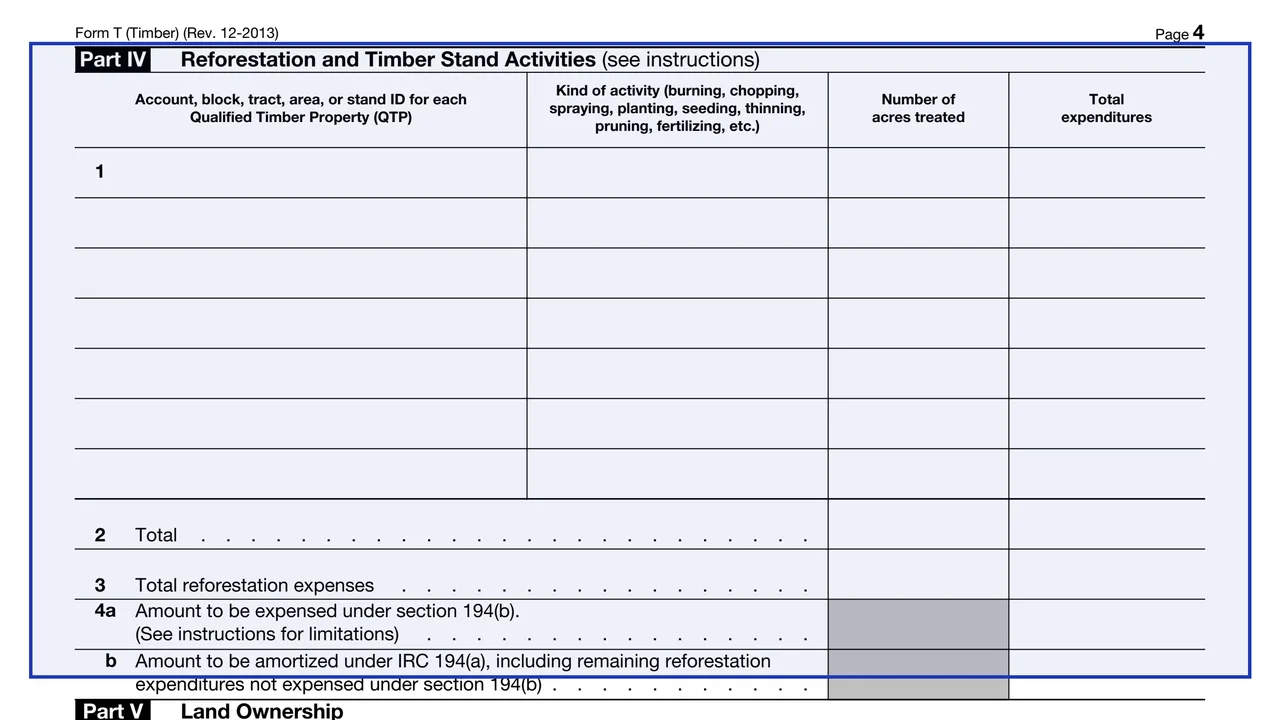
Each qualified timber property with its activity, acres treated and expenditures, then line 4a for the amount expensed under section 194(b) and line 4b for the amount amortized under section 194(a).
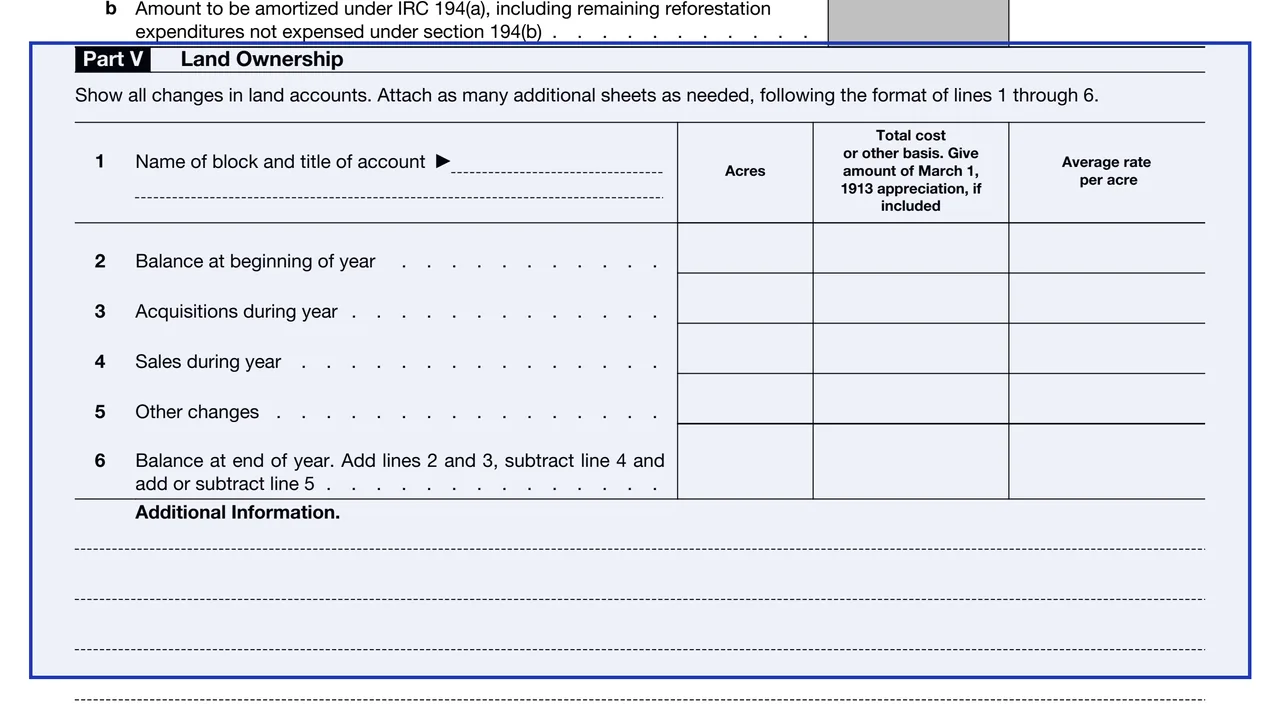
Acres, total cost or other basis and average rate per acre for the balance at the start of the year, acquisitions, sales, other changes and the balance at year end.
Enter the tax year ending date, the name or names as shown on the return and the identifying number. The instructions say to complete all the parts of the form that apply.
Report each acquisition of $10,000 or more separately. Acquisitions under $10,000 may be combined for each account, omitting lines 2 and 3. For a gift or inheritance, skip lines 4 through 7. Line 9h equals line 8.
Give data for each timber account that changed in quantity or dollar amount. Line 8 divides line 7, column (b), by line 7, column (a). Line 10 multiplies line 8 by line 9, and line 12 multiplies line 8 by line 11.
Check Yes on line 18a when making the section 631(a) election or when one from a prior year is in effect. The instructions say the election cannot be made on an amended return. Check Yes on 18b when revoking it.
Report each sale with total consideration of $10,000 or more; smaller sales may be combined for each account. Dispositions by gift are not reported. Line 8 subtracts the sum of lines 7h and 7i from line 6.
List each qualified timber property, activity, acres and expenditures, then split costs between lines 4a and 4b. In Part V, line 6 adds lines 2 and 3, subtracts line 4 and adds or subtracts line 5.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to your tax return." It is a schedule filed with the income tax return, not sent on its own.
The instructions say line 4a cannot exceed $10,000 ($5,000 if your filing status is married filing separately) for each qualified timber property for any tax year. Remaining costs can be amortized over an 84-month period.
The instructions say not to attach maps of timber properties to Form T. Records, including a map where necessary, are kept to support any depletion deduction.
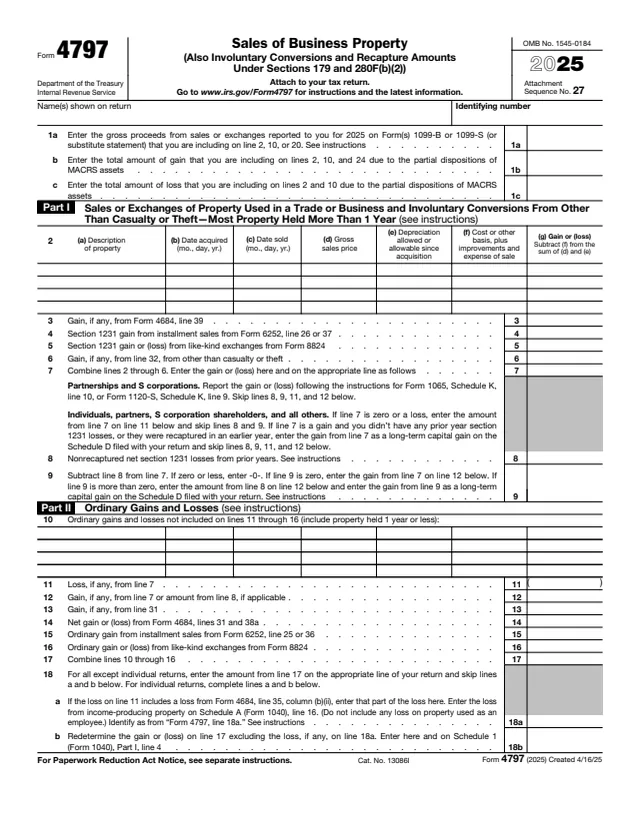
For a section 631(a) election, the instructions say the gain or loss on standing timber is reported on Form 4797, Sales of Business Property.
The instructions say an election made for a tax year ending before October 23, 2004, can be revoked without IRS consent for a tax year ending after October 22, 2004. Otherwise revoking generally needs IRS consent.
For taxpayers other than individuals, the instructions estimate 34 hr., 12 min. for recordkeeping, 42 min. to learn about the law or the form, and 1 hr., 17 min. to prepare and send it.
The instructions name three situations in which Form T is completed and attached to the income tax return, and one exception.
No tool matches that search.
No. The form says to attach it to your tax return.
The instructions say it is not required if there is only an occasional sale of timber, one or two sales every 3 or 4 years. Adequate records of those transactions are still kept.
The instructions describe a block as an operational unit, a logging unit, or an area set by the geographical or political boundaries of logical management areas. Each account generally holds all timber in one block.
No. The instructions say the 631(a) election cannot be made on an amended return.
The instructions say the total cannot exceed $10,000 ($5,000 if married filing separately) for each qualified timber property for any tax year. The rest can be amortized over 84 months under section 194(a).
The About page lists the December 2013 revision as the current Form T (Timber) and shows no recent developments.