Part I, boxes 1 and 2: issuer
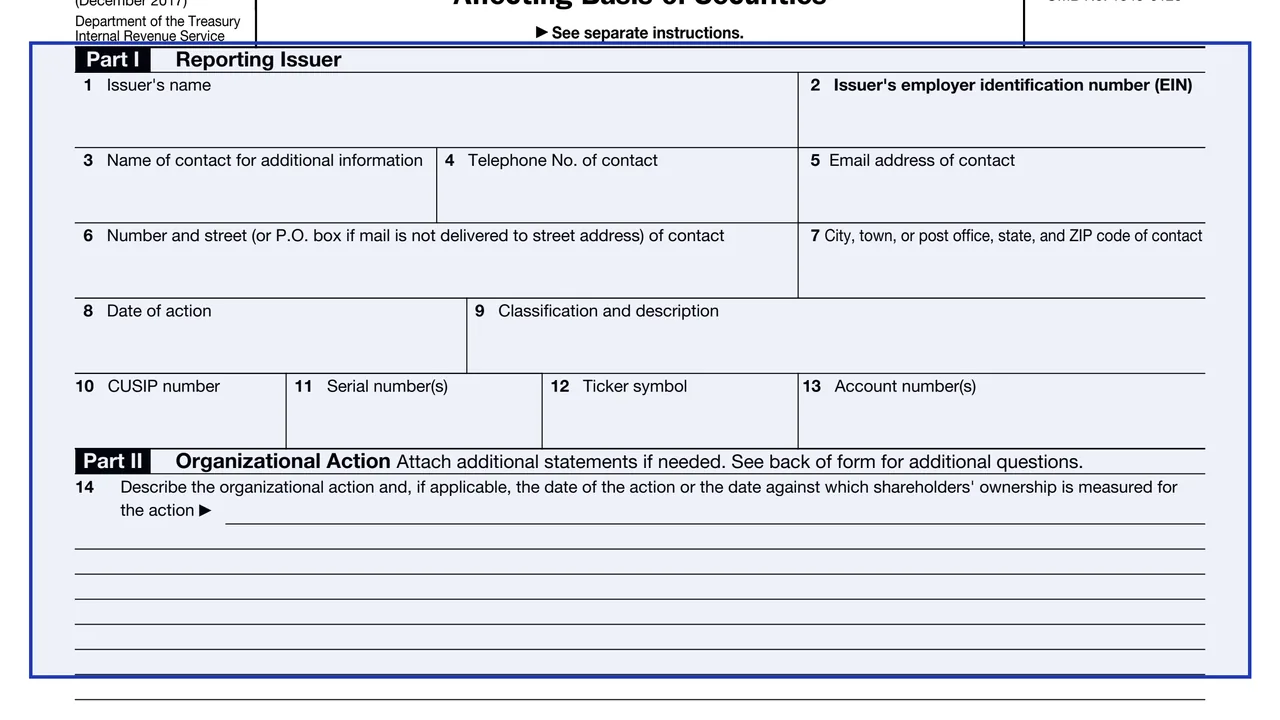
The issuer's name and employer identification number (EIN).
8937
Report of Organizational Actions Affecting Basis of Securities
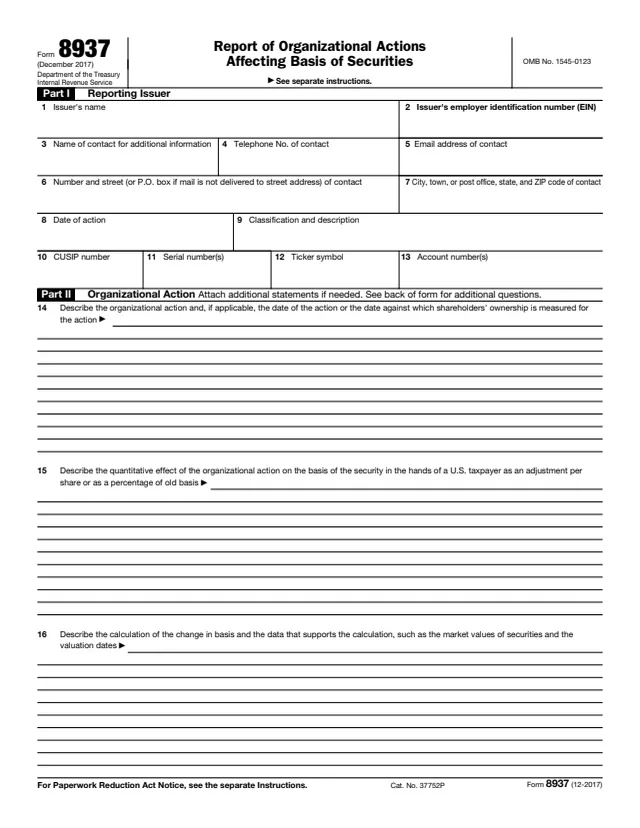
Form 8937, Report of Organizational Actions Affecting Basis of Securities, is filed by an issuer of a specified security that takes an organizational action that affects the basis of that security. The instructions give examples such as a nontaxable cash distribution to shareholders or a nontaxable stock distribution, including a stock split.
The instructions define a specified security to include stock in a corporation, interests treated as stock such as an American Depositary Receipt, certain options, warrants and stock rights, securities futures contracts, and many debt instruments. The requirement applies to both domestic and foreign issuers if U.S. taxpayers own the security, directly or as a depositary receipt.
The issuer reports the action to the IRS and gives a copy, or a written statement with the same information, to holders of record or their nominees. You can fill out the PDF free in your browser on this page and download it without an account.
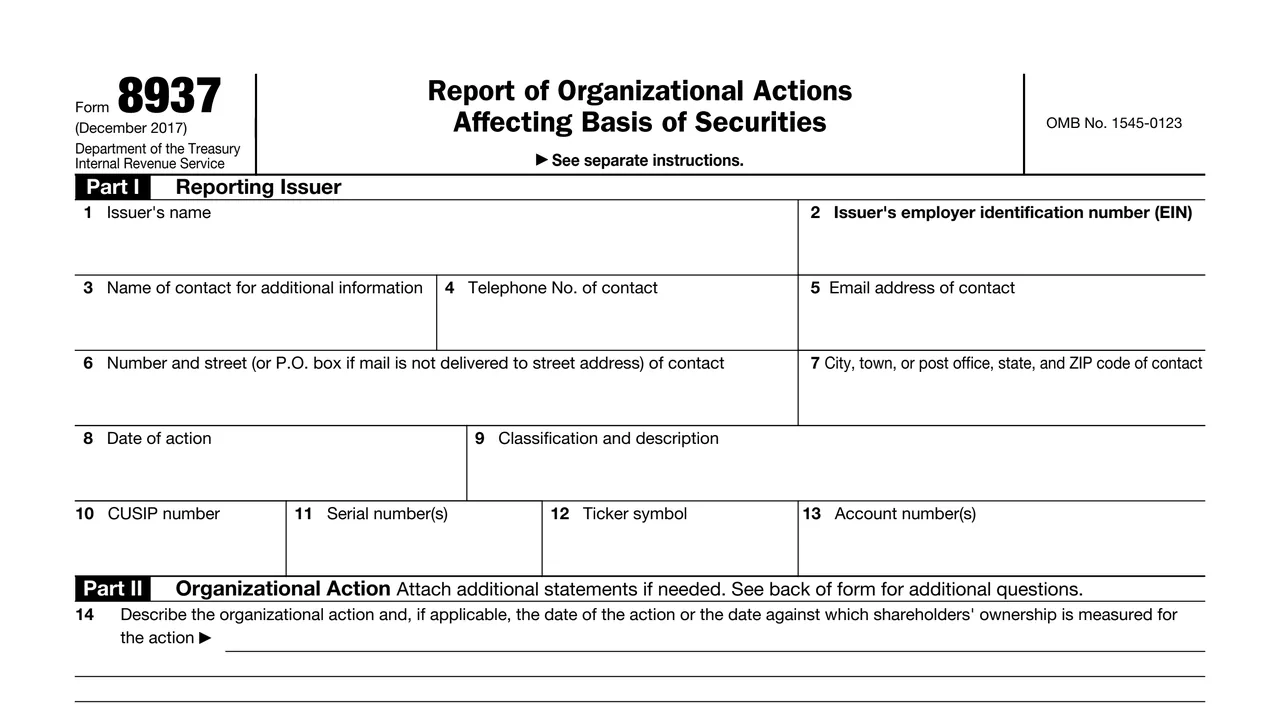
The issuer's name and employer identification number (EIN).
Name, telephone number, email address and mailing address of a contact for additional information.
Date of action, classification and description, CUSIP number, serial numbers, ticker symbol and account numbers.
A description of the organizational action and its date, its quantitative effect on basis per share or as a percentage of old basis, and how the change in basis was calculated.
The Internal Revenue Code sections the treatment is based on, whether any resulting loss can be recognized, and other information such as the reportable tax year.
Signature under penalties of perjury with printed name and title, and a Paid Preparer Use Only block with PTIN and firm details.
Enter the issuer's name and EIN.
Enter the name, telephone number, email address and mailing address of a contact person.
For each security involved, complete every box that applies and leave the rest blank. In box 9, enter the classification, such as stock, and describe the class of security affected.
For each security involved, describe the action, its quantitative effect on basis, the calculation and supporting data, the Code sections relied on, whether a loss can be recognized, and any other information needed.
Sign and date, and print the name and title. A paid preparer, if one is used, completes the preparer block.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say Form 8937 is filed on or before the 45th day following the organizational action or, if earlier, January 15 of the year following the calendar year of the action.
The form says to send it, including accompanying statements, to Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0054.
The instructions say filing with the IRS is not required if, by the due date, the issuer posts a completed and signed form on its primary public website and keeps it accessible for 10 years.
A copy or written statement goes to holders of record or nominees on or before January 15 of the year following the calendar year of the organizational action.
The instructions say a corrected return is filed within 45 days of determining facts that result in a different quantitative effect on basis.
The instructions say not to report a distribution on Form 8937 if it is reportable as a dividend on Form 1099-DIV.
The issuer of the security files Form 8937. Holders of the security and their nominees receive a copy or an issuer statement.
No tool matches that search.
The issuer of a specified security that takes an organizational action affecting the basis of that security. Holders of the security receive a copy or an issuer statement.
The instructions say on or before the 45th day following the organizational action or, if earlier, January 15 of the year following the calendar year of the action.
The instructions say filing with the IRS is not required if, by the due date, a completed and signed form is posted on the issuer's primary public website and kept accessible for 10 years.
The instructions list a nontaxable stock distribution to shareholders, including a stock split, as an example of an action reported on the form.
The instructions say Form 8937 is not needed for an initial public offering or an issuance of a debt instrument, though it may be needed for a debt issuance in a recapitalization.
The form says to send it to Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0054.