Filer and plan (items A to G)
Filer's tax year, name, EIN and address, name of plan, plan sponsor's name, address and EIN, plan year ending and plan number.
8928
Return of Certain Excise Taxes Under Chapter 43 of the Internal Revenue Code
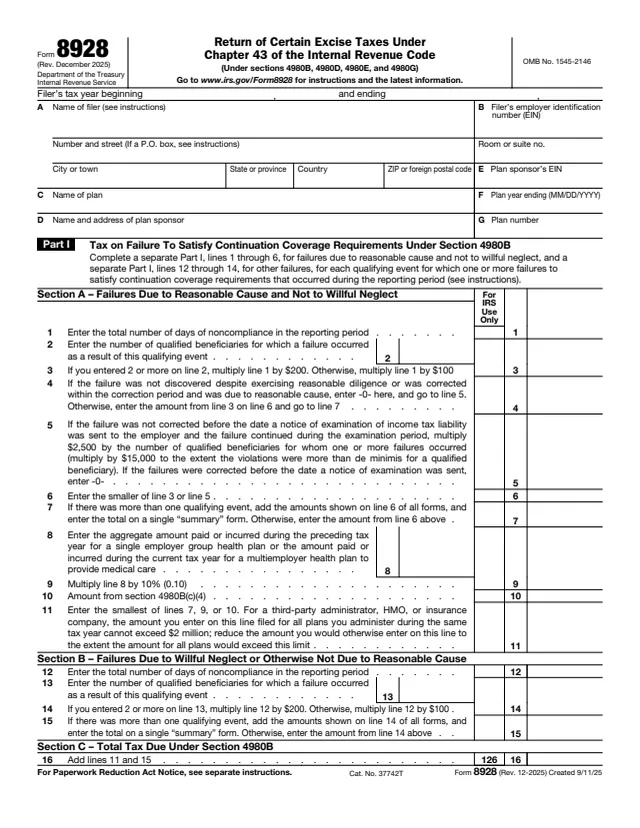
Form 8928, Return of Certain Excise Taxes Under Chapter 43 of the Internal Revenue Code, is filed by group health plans or employers to report the tax due on certain failures. The instructions list a failure to provide the required level of pediatric vaccine coverage, a failure to satisfy continuation coverage requirements under section 4980B, a failure to meet portability, access, renewability and market reform requirements, and a failure to make comparable Archer MSA or health savings account (HSA) contributions under sections 4980E and 4980G.
The return has five parts: one for each of the four tax sections and a final part for the tax due or overpayment. Parts I and II separate failures due to reasonable cause from failures due to willful neglect. The instructions say the tax due is paid in full when Form 8928 is filed, and that Form 7004 extends the time to file but not the time to pay.
You can fill out the PDF free in your browser on this page and download it without an account.
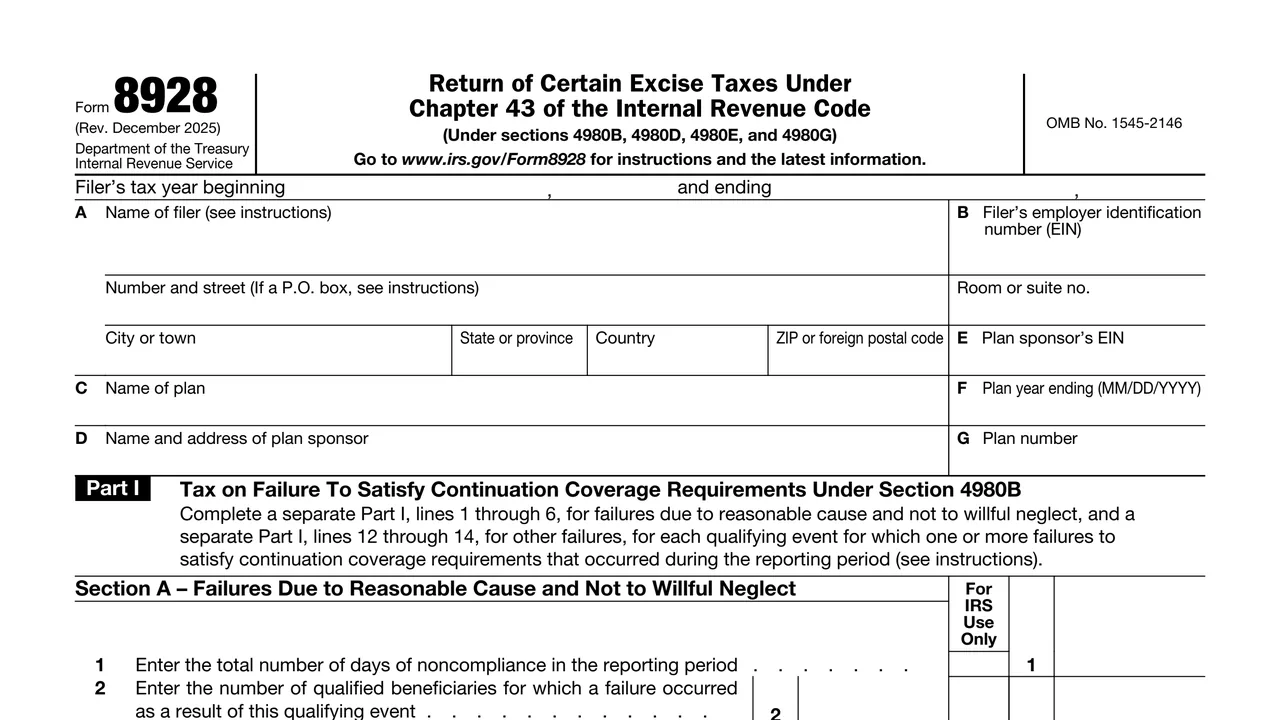
Filer's tax year, name, EIN and address, name of plan, plan sponsor's name, address and EIN, plan year ending and plan number.
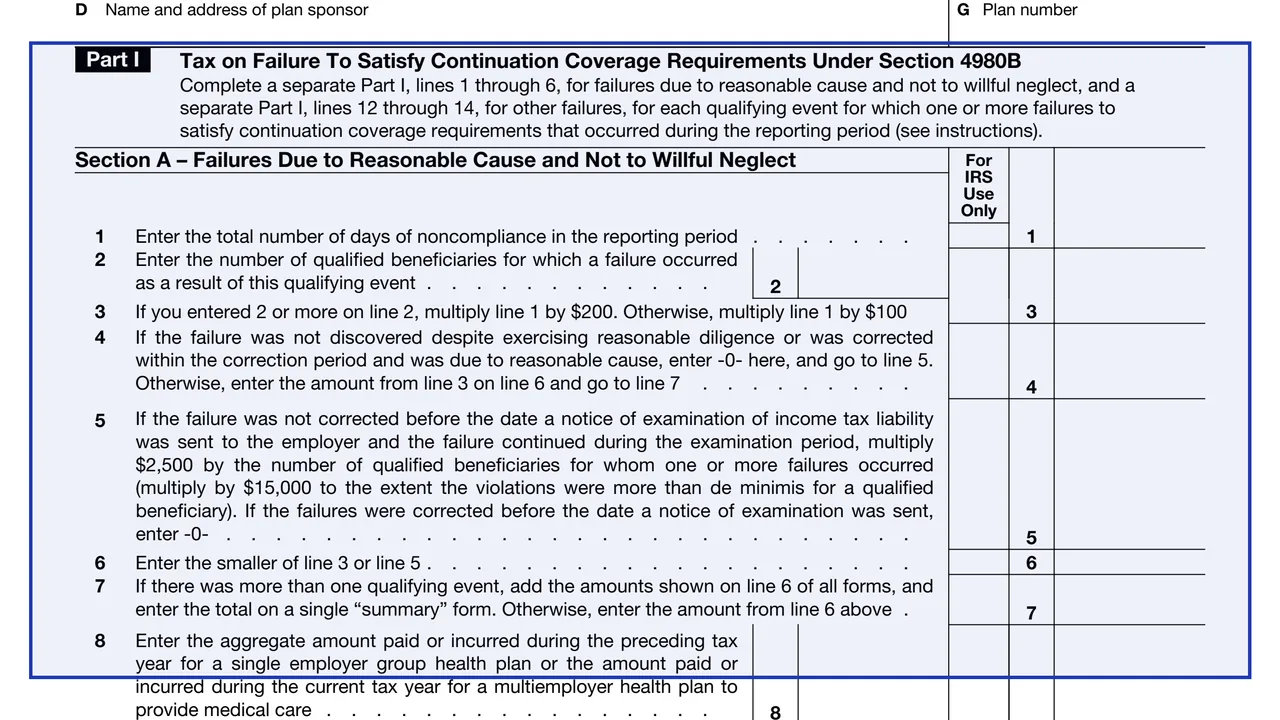
Tax on failure to satisfy continuation coverage requirements. Section A covers failures due to reasonable cause, Section B covers willful neglect, and line 16 totals them.
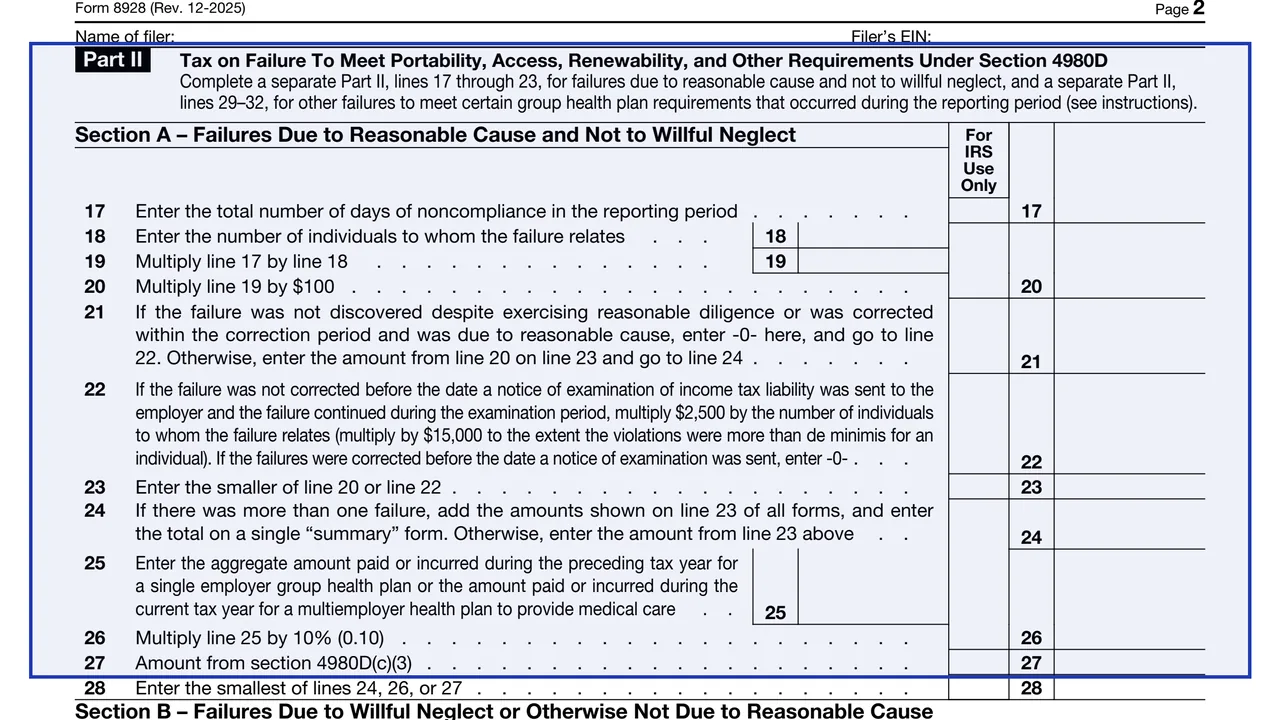
Tax on failure to meet portability, access, renewability and other requirements, with the same Section A, B and C structure. Line 34 is the total.
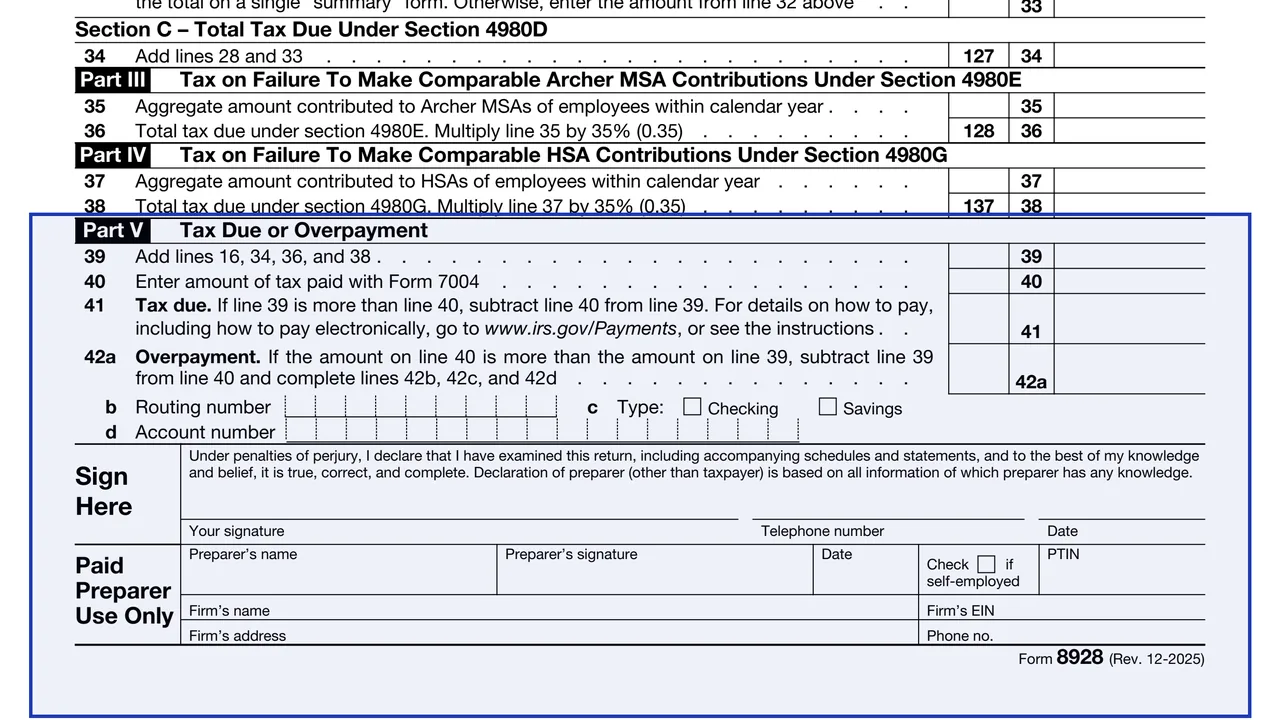
Aggregate employer contributions to employees' Archer MSAs (line 35) and HSAs (line 37), each multiplied by 35% (0.35).
Total tax, tax paid with Form 7004, tax due or overpayment, and direct deposit lines 42b to 42d, followed by the signature and paid preparer section.
Enter the filer's tax year, the liable filer's name and address, the plan name and sponsor, the sponsor's EIN as used on Form 5500, the plan year ending in eight digits (for example 03/31/2025) and the three-digit plan number.
Complete lines 1 through 6 for each qualifying event. Line 3 multiplies the days by $200 if two or more beneficiaries are on line 2, otherwise by $100. Lines 8 to 11 cap the total using 10% of line 8 and the section 4980B(c)(4) amount.
With more than one qualifying event or failure, complete separate parts, then a summary Form 8928 with items A to G and the totals. The instructions say to write "Summary Form" at the top and attach all copies.
Multiply the days of noncompliance by the number of individuals, then by $100. The instructions describe an exception for certain insured small employer plans and say the $2,500 or $15,000 minimum does not apply to a church plan.
Enter the aggregate amount contributed to employees' Archer MSAs on line 35 or HSAs on line 37 for tax years ending with or within the calendar year, then multiply by 35%.
Add lines 16, 34, 36 and 38, subtract tax paid with Form 7004, and enter the tax due or the overpayment with direct deposit details. Sign, date and add a daytime phone number.
These steps summarize the Specific Instructions for Form 8928.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions give this address: Department of the Treasury, Internal Revenue Service Center, Kansas City, MO 64999.
For 4980B or 4980D failures by an employer or other responsible person, by the due date of that person's federal income tax return. For a multiemployer or multiple employer plan, by the last day of the seventh month after the plan year ends. For 4980E or 4980G, by the 15th day of the 4th month after the calendar year of the contributions.
Form 7004 requests an automatic extension of time to file and is filed on or before the regular due date of Form 8928. The instructions say it does not extend the time to pay the excise taxes.
The instructions list EFTPS, same-day wire and check. A check is payable to "United States Treasury" with the entity's name, address, EIN and "Form 8928" written on it.
Late filing: 5% of the unpaid tax per month, up to 25%, with a minimum for a return more than 60 days late of the smaller of $525 or 100% of the tax due. Late payment: ½ of 1% per month, up to 25%.
To claim a refund or credit or report additional tax, write "Amended Return" at the top of Form 8928 and complete the appropriate part. A refund claim states the reasons in detail.

7004
26 fields, 1 page
W-12
85 fields, 3 pages
5330
304 fields, 6 pages
The instructions name the filers below. Item A says the filer is the employer, individual or other entity liable for the tax.
No tool matches that search.
The instructions say employers, group health plans, plan administrators or plan sponsors liable for the taxes under sections 4980B, 4980D, 4980E or 4980G.
The instructions give Department of the Treasury, Internal Revenue Service Center, Kansas City, MO 64999.
No. The instructions say Form 7004 extends the time to file Form 8928 but does not extend the time to pay the excise taxes due.
When there is more than one qualifying event or failure, separate parts are completed for each, and a summary Form 8928 carries the totals. It is marked "Summary Form" at the top with all copies attached.
Line 11 says that for a third-party administrator, HMO or insurance company, the amount for all plans administered in the same tax year cannot exceed $2 million.
The instructions say to write "Amended Return" at the top of Form 8928 and complete the appropriate part, stating the reasons in detail for a refund or credit claim.