Header
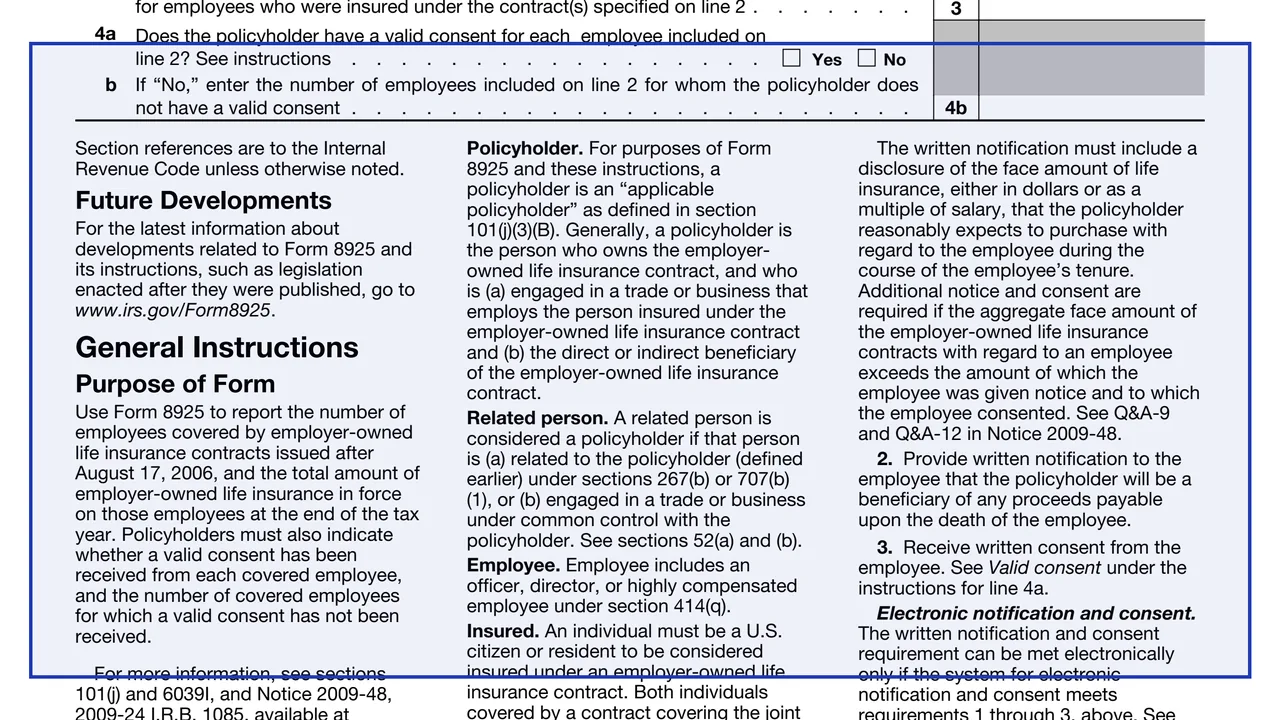
Name shown on the return and identifying number, the name and identifying number of the policyholder if different, and the type of business.
8925
Report of Employer-Owned Life Insurance Contracts
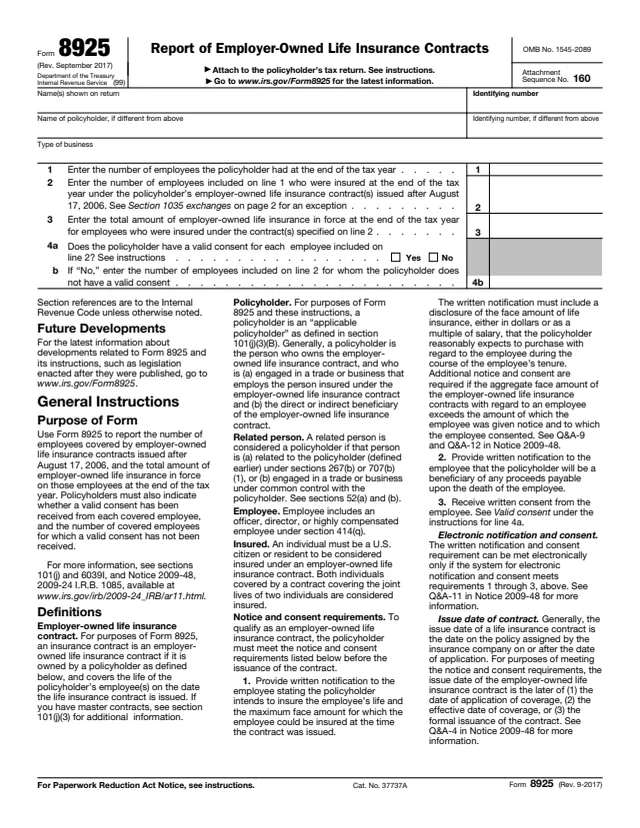
Form 8925 reports the number of employees covered by employer-owned life insurance contracts issued after August 17, 2006, and the total amount of employer-owned life insurance in force on those employees at the end of the tax year. The instructions say policyholders also indicate whether a valid consent has been received from each covered employee, and how many covered employees have no valid consent.
The form is filed by the policyholder that owns the contracts, not by the insured employees. It is attached to the policyholder's income tax return. The instructions, printed on the form, point to sections 101(j) and 6039I and to Notice 2009-48 for more information.
You can fill it out free in your browser on this page and download the result without an account.
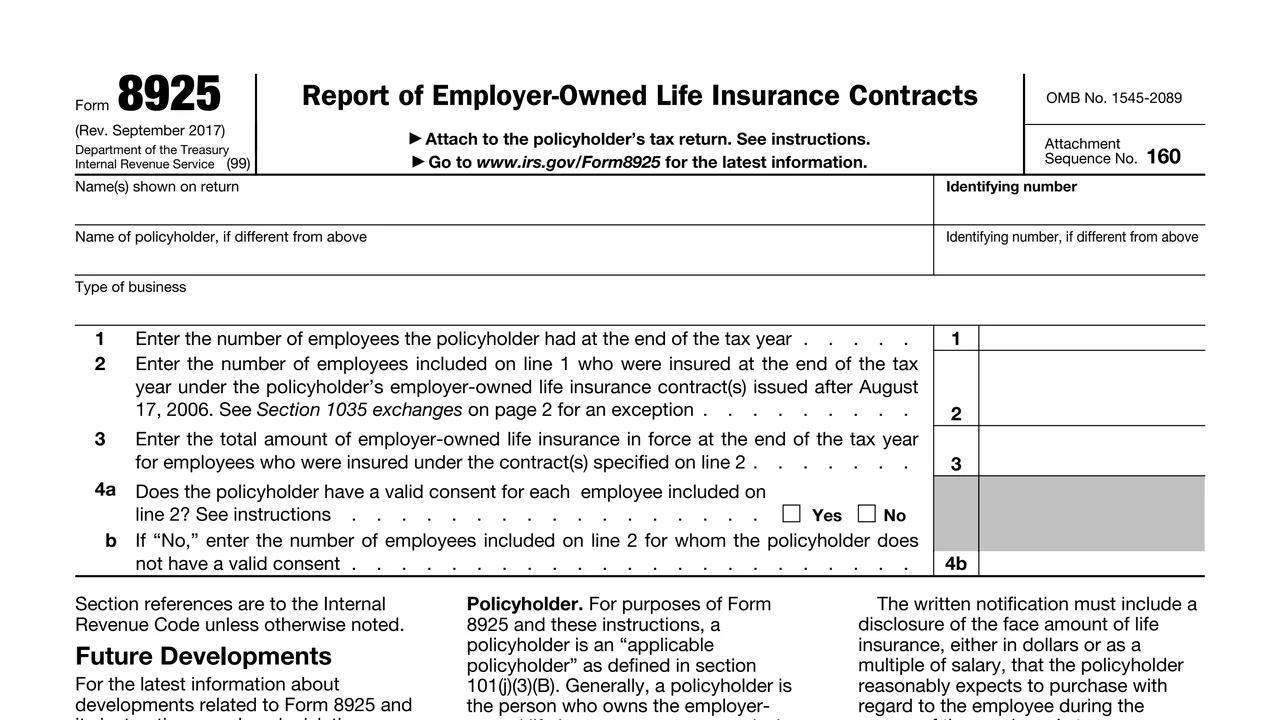
Name shown on the return and identifying number, the name and identifying number of the policyholder if different, and the type of business.
The number of employees the policyholder had at the end of the tax year.
The number of employees from line 1 insured at year end under employer-owned life insurance contracts issued after August 17, 2006.
The total amount of employer-owned life insurance in force at the end of the tax year for the employees on line 2.
A Yes or No question on whether the policyholder has a valid consent for each employee on line 2, and, if No, the number of employees without one.
Enter the name of the policyholder. The instructions say the identifying number of an individual is a social security number, and for all other taxpayers it is an employer identification number.
Enter the policyholder's trade or business activity.
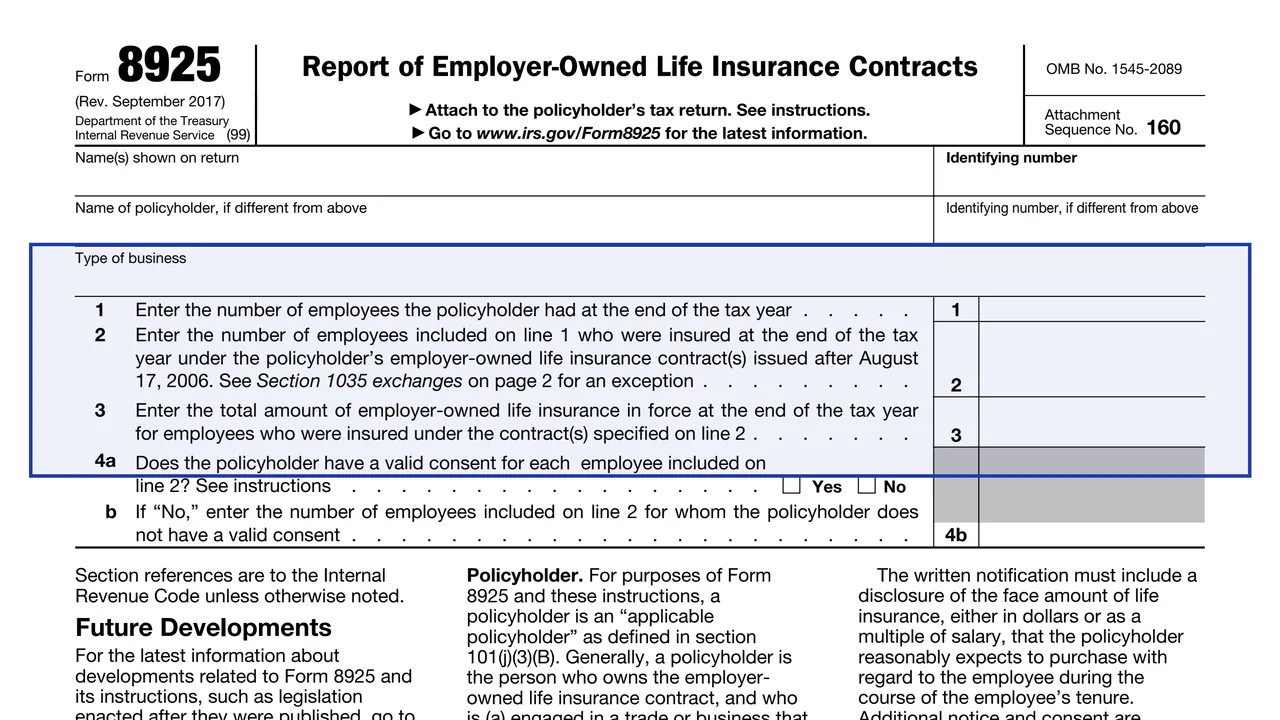
Enter the year-end employee count, the number insured under contracts issued after August 17, 2006, and the total insurance in force for them.
The instructions say a valid consent is a written consent, given before the contract is issued, to be insured and to coverage continuing after employment ends. Check Yes or No.
If line 4a is No, enter the number of employees on line 2 for whom the policyholder does not have a valid consent.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Form 8925 to the policyholder's income tax return for each tax year during which the policyholder has employer-owned life insurance contracts in force.
The instructions list three steps before the contract is issued: written notice of the intent to insure and the maximum face amount, written notice that the policyholder will be a beneficiary, and written consent from the employee.
The instructions say the written consent is not valid unless the contract is issued within a year after the consent was executed, or before the employee ends employment, whichever is earlier.
The instructions say the notice and consent can be given electronically only if the system meets the three written requirements. They point to Q&A-11 in Notice 2009-48.
The instructions say to keep adequate records to support the information reported on Form 8925.
The instructions say that, generally, every policyholder owning one or more employer-owned life insurance contracts issued after August 17, 2006, files Form 8925 for each tax year the contracts are owned.
No tool matches that search.
No. The instructions say the policyholder that owns the employer-owned life insurance contracts files it, attached to its own income tax return.
Employer-owned life insurance contracts issued after August 17, 2006. The instructions describe an exception for certain section 1035 exchanges of contracts issued before August 18, 2006.
The instructions say it is a written consent from the employee, given before the contract is issued, to be insured and to coverage that may continue after employment ends.
The instructions say it is attached to the policyholder's income tax return for each tax year during which the contracts are in force.
The form points to sections 101(j) and 6039I of the Internal Revenue Code and to Notice 2009-48, 2009-24 I.R.B. 1085.