Line 1: cases of distilled spirits
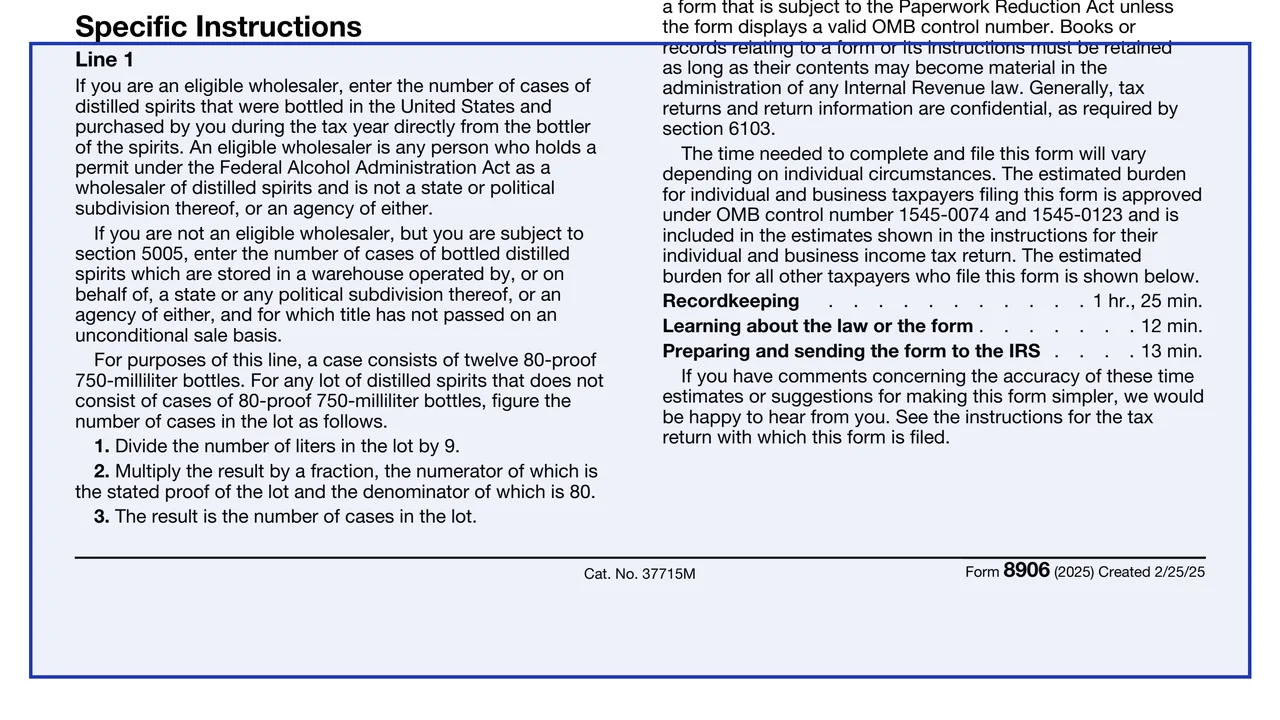
The total number of cases of distilled spirits. The form says a case consists of twelve 80-proof 750-milliliter bottles.
8906
Distilled Spirits Credit
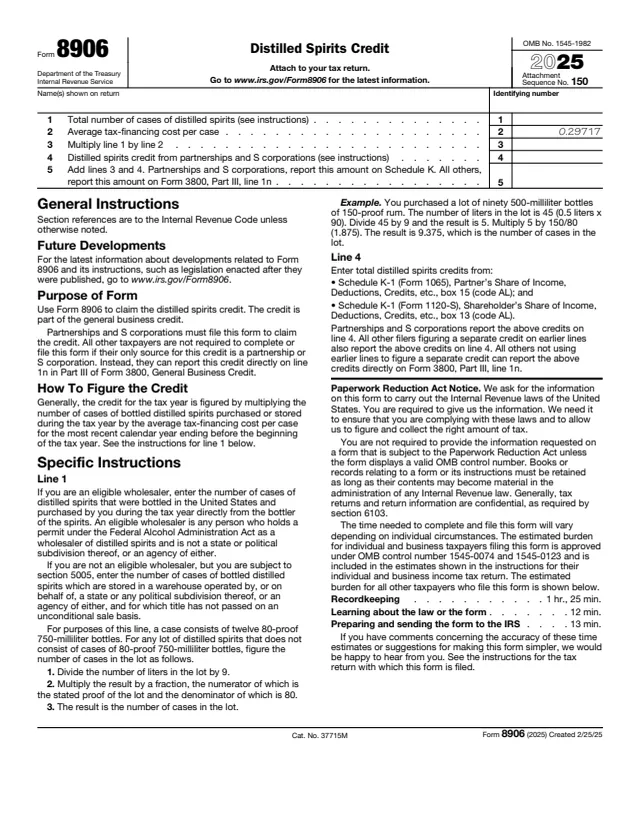
Form 8906 is used to claim the distilled spirits credit. The form and its About page say the credit is part of the general business credit, and the form says to attach it to the tax return. This page covers the 2025 form.
The form says the credit is generally figured by multiplying the number of cases of bottled distilled spirits purchased or stored during the tax year by the average tax-financing cost per case for the most recent calendar year ending before the beginning of the tax year. On the 2025 form, line 2 is preprinted with an average tax-financing cost per case of 0.29717.
The form has five lines, and its instructions are printed on the same page. You can fill it out free in your browser on this page and download the result without an account.
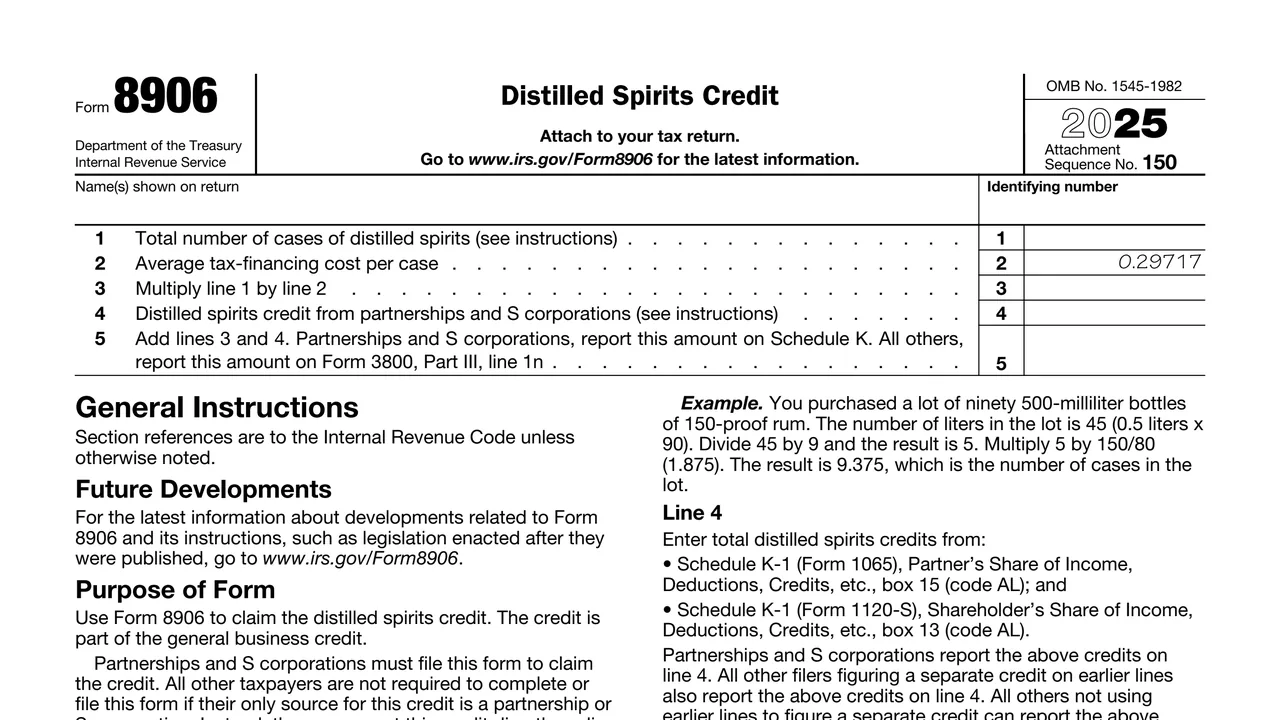
The total number of cases of distilled spirits. The form says a case consists of twelve 80-proof 750-milliliter bottles.
Preprinted on the 2025 form as 0.29717.
Line 1 multiplied by line 2.
Distilled spirits credit passed through from partnerships and S corporations.
Lines 3 and 4 added together, reported on Schedule K by partnerships and S corporations, or on Form 3800, Part III, line 1n by all others.
The form says an eligible wholesaler enters the number of cases of distilled spirits bottled in the United States and purchased during the tax year directly from the bottler of the spirits.
A filer that is not an eligible wholesaler but is subject to section 5005 enters cases of bottled distilled spirits stored in a warehouse operated by, or on behalf of, a state or political subdivision, or an agency of either, for which title has not passed on an unconditional sale basis, as the form describes.
For a lot not in cases of 80-proof 750-milliliter bottles, the form says to divide the liters in the lot by 9, then multiply by the stated proof over 80. Its example: ninety 500-milliliter bottles of 150-proof rum come to 9.375 cases.
Line 2 already shows 0.29717. Multiply line 1 by line 2 and enter the result on line 3.
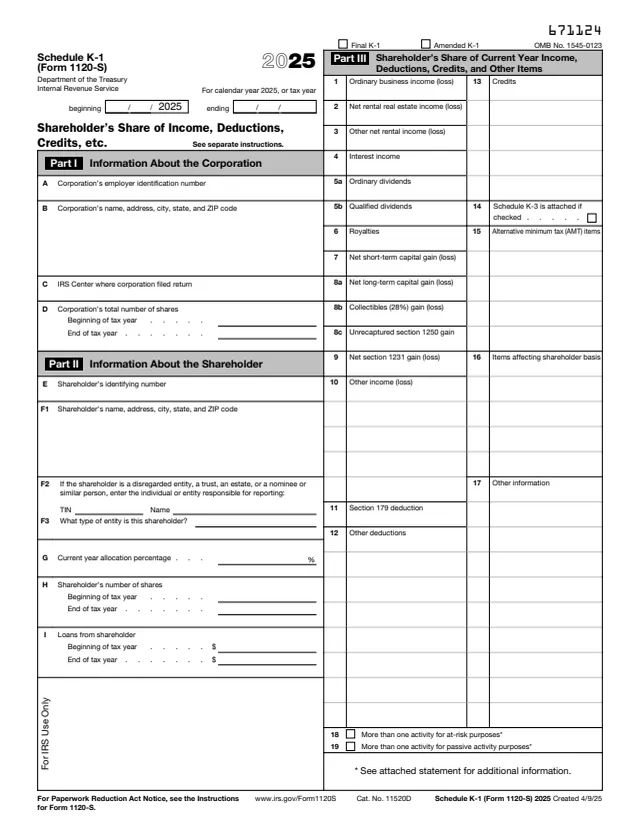
Enter credits from Schedule K-1 (Form 1065), box 15 (code AL), and Schedule K-1 (Form 1120-S), box 13 (code AL), as the form says.
Add lines 3 and 4. The form says partnerships and S corporations report this amount on Schedule K, and all others report it on Form 3800, Part III, line 1n.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return.
The credit is part of the general business credit. Filers other than partnerships and S corporations carry the line 5 amount to Form 3800, Part III, line 1n.
The form says filers figuring a separate credit on earlier lines also report pass-through credits on line 4, while others not using earlier lines can report them directly on Form 3800, Part III, line 1n.
For filers outside the individual and business estimates, the form lists 1 hr., 25 min. for recordkeeping, 12 min. for learning about the law or the form, and 13 min. for preparing and sending the form to the IRS.
The form points to www.irs.gov/Form8906 for developments such as legislation enacted after it was published.

3800
1,921 fields, 9 pages

1065
111 fields, 1 page
1120-S
114 fields, 1 page

1065
440 fields, 6 pages

1120-S
390 fields, 5 pages
The form is attached to the tax return of the taxpayer claiming the credit. The form describes these filers.
No tool matches that search.
The form says a case consists of twelve 80-proof 750-milliliter bottles. Other lots are converted by dividing the liters by 9 and multiplying by the stated proof over 80.
The 2025 form prints 0.29717 as the average tax-financing cost per case.
The form says taxpayers whose only source of the credit is a partnership or S corporation are not required to complete or file it, and can report the credit on Form 3800, Part III, line 1n.
The form says it is any person who holds a permit under the Federal Alcohol Administration Act as a wholesaler of distilled spirits and is not a state or political subdivision thereof, or an agency of either.
Partnerships and S corporations report it on Schedule K. All others report it on Form 3800, Part III, line 1n.