Line 1: natural gas production
Qualified natural gas production, in thousands of cubic feet.
8904
Credit for Oil and Gas Production From Marginal Wells
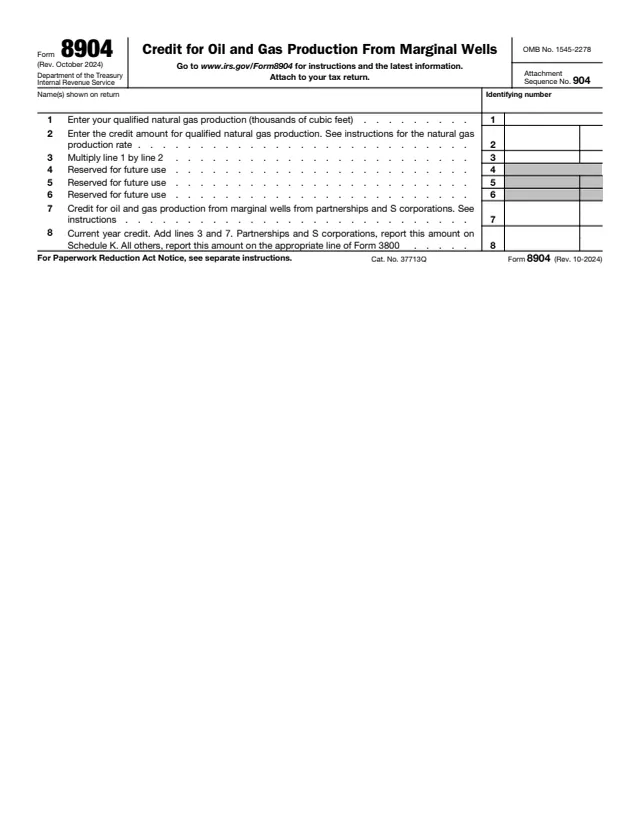
Form 8904 is used to claim the section 45I credit for oil and gas production from marginal wells. The About page says the credit is part of the general business credit, and the form says to attach it to the tax return.
The instructions say the credit is applicable for tax years beginning in 2025 for qualified natural gas production, and that it remains phased out for crude oil production. For tax years beginning in 2025, they give a credit amount of $0.79 per thousand cubic feet of qualified natural gas production, entered on line 2.
The form is short: natural gas production and the credit rate on lines 1 to 3, three lines reserved for future use, and credits from partnerships and S corporations on line 7. You can fill it out free in your browser on this page and download the result without an account.
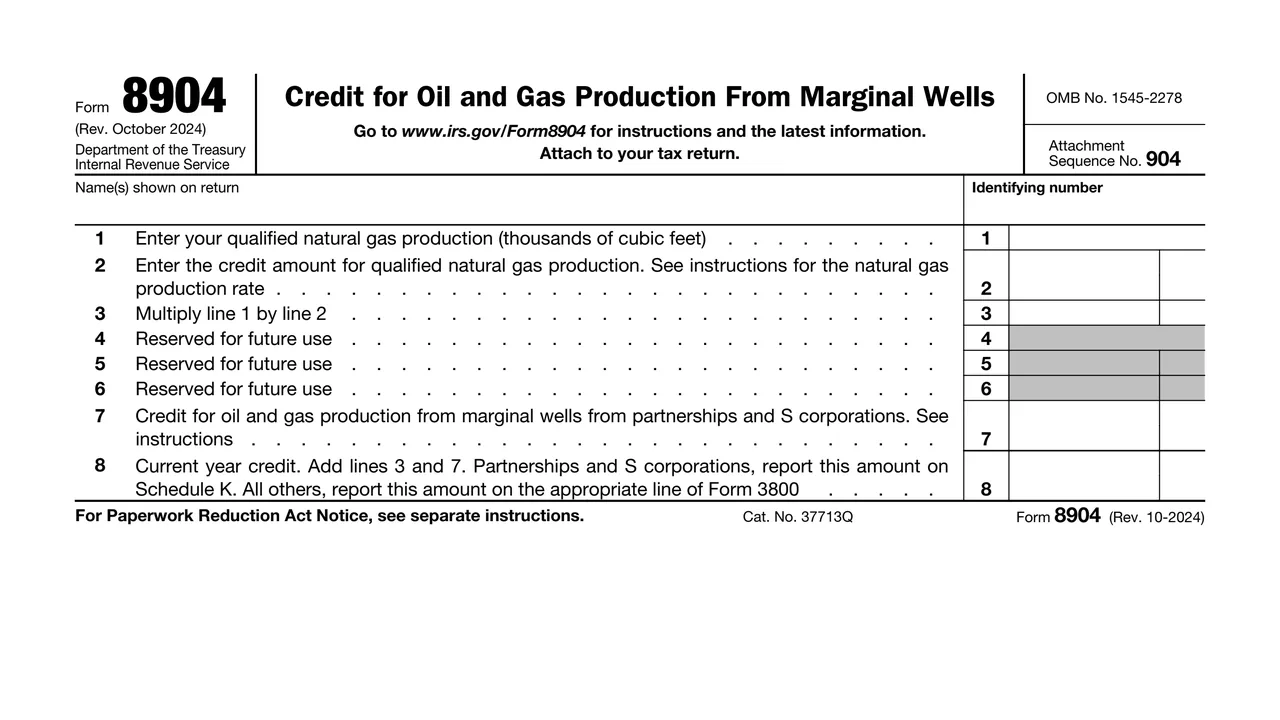
Qualified natural gas production, in thousands of cubic feet.
The credit amount for qualified natural gas production. The form says to see the instructions for the rate.
Line 1 multiplied by line 2.
Reserved for future use.
Credit for oil and gas production from marginal wells from partnerships and S corporations.
Lines 3 and 7 added together, reported on Schedule K or Form 3800.
Enter qualified natural gas production in thousands of cubic feet. The instructions limit qualified production to 1,095 barrels or barrel-of-oil equivalents per well for the tax year, reduced for short years and days a well can't produce.
The instructions say that for tax years beginning in 2025, enter the credit amount of $0.79 on line 2.
Multiply line 1 by line 2. Leave lines 4, 5 and 6 blank, as they are reserved for future use.
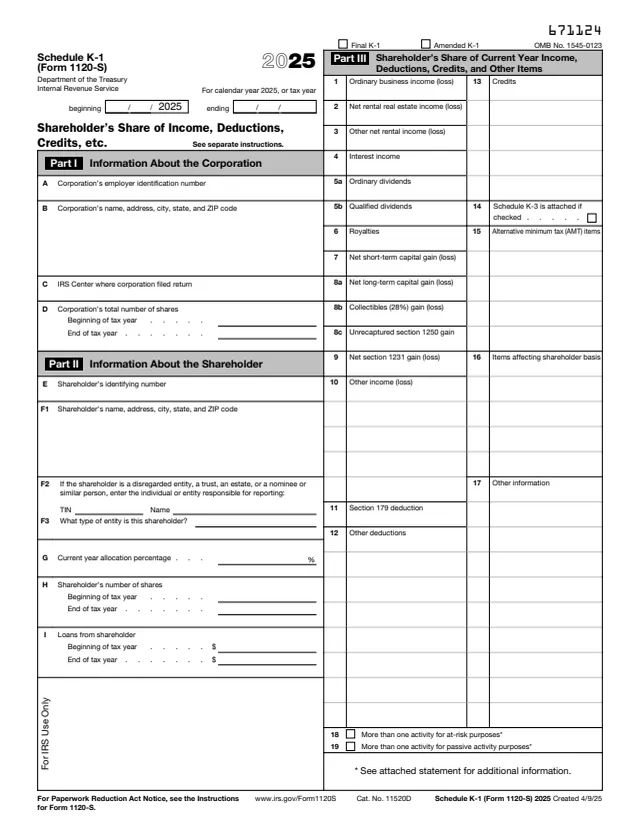
Enter credits from Schedule K-1 (Form 1065), box 15 (code P), and Schedule K-1 (Form 1120-S), box 13 (code P), as the instructions say.
Add lines 3 and 7. The form says partnerships and S corporations report this amount on Schedule K, and all others report it on the appropriate line of Form 3800.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to your tax return.
The instructions say the credit is generally $3 per barrel of qualified crude oil production and $0.50 per 1,000 cubic feet of qualified natural gas production, subject to a statutory reduction and an inflation adjustment factor. For tax years beginning in 2025, it is $0.79 per thousand cubic feet of natural gas.
The instructions say an owner of a marginal well may claim the credit any time within 3 years from the due date (excluding extensions) of its return, on either its original or an amended return.
The instructions say an unused credit is carried back to each of the preceding 5 tax years, then forward to each of the 20 tax years after the year of the credit.
The instructions define it as a domestic well whose production is treated as marginal production under section 613A(c)(6), or has average daily production of not more than 25 barrel-of-oil equivalents and produces water at a rate not less than 95% of total well effluent.
The instructions say no section 45I credit is allowable for a well eligible for the section 45K nonconventional source fuel credit unless an election is made not to claim the section 45K credit for that well.

3800
1,921 fields, 9 pages

1065
111 fields, 1 page
1120-S
114 fields, 1 page

1065
440 fields, 6 pages

1120-S
390 fields, 5 pages
The form is attached to the tax return of the taxpayer claiming the credit. The instructions describe these filers.
No tool matches that search.
The instructions say the credit is applicable for tax years beginning in 2025 for qualified natural gas production and remains phased out for crude oil production.
The instructions say that for tax years beginning in 2025, enter the credit amount of $0.79 on line 2.
The instructions say taxpayers whose only source of the credit is a partnership or S corporation aren't required to file it and can report the credit directly on Form 3800.
The form and instructions mark lines 4, 5 and 6 as reserved for future use.
The instructions say an owner of a marginal well may claim it within 3 years from the due date (excluding extensions) of its return, on either its original or an amended return.