Header and period of claim
The name and EIN or SSN as shown on Form 8849, the total refund, a caution with the claimant's certifications, and the period of claim in MMDDYYYY format.
8849 Sch. 1
Nontaxable Use of Fuels
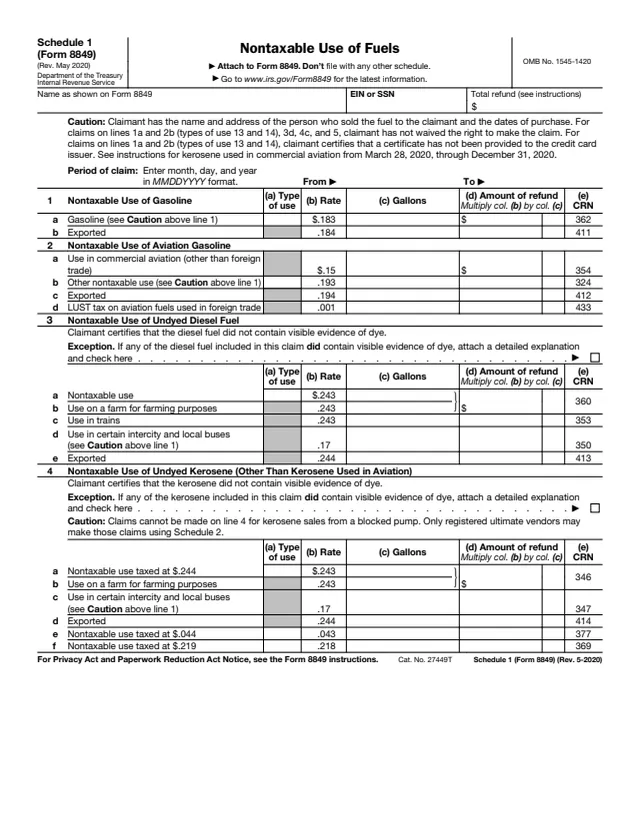
Schedule 1 (Form 8849), Nontaxable Use of Fuels, is a schedule of Form 8849, Claim for Refund of Excise Taxes. The IRS says an ultimate purchaser of gasoline, gasohol, aviation gasoline, diesel fuel, kerosene, aviation fuel (other than gasoline), and liquefied gas (LPG) uses Schedule 1 to make a claim for refund.
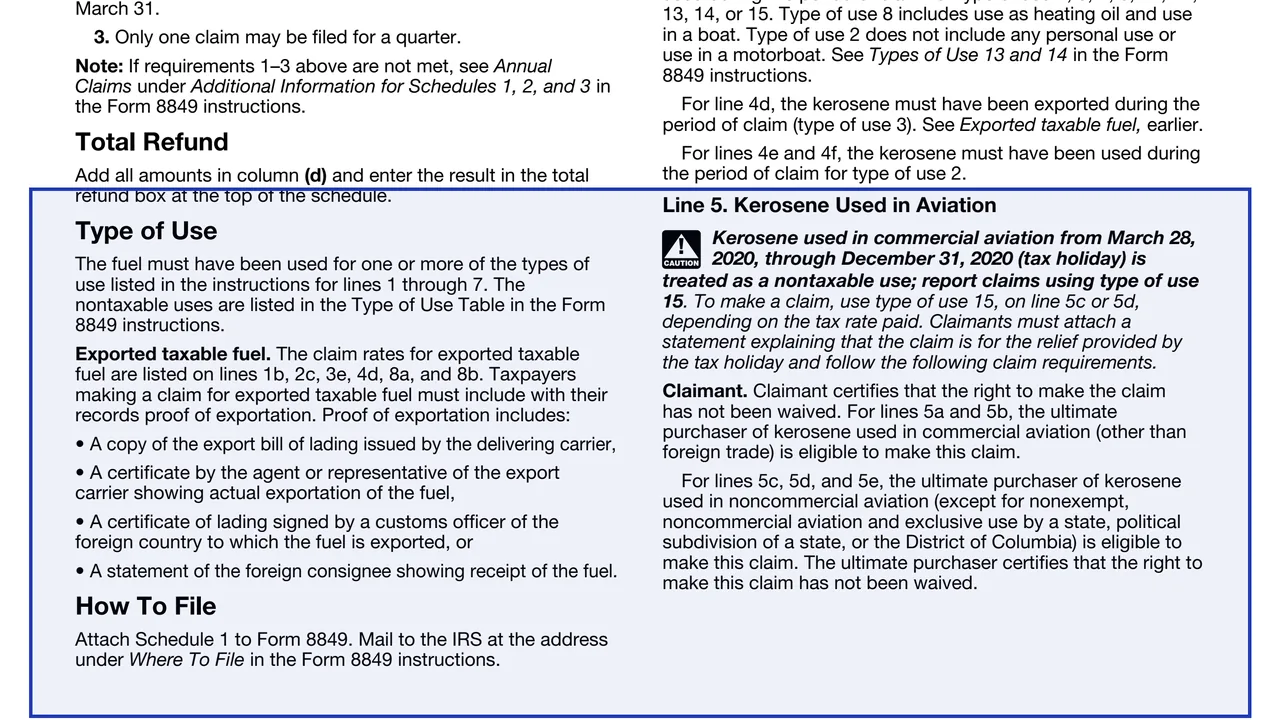
The instructions printed on the schedule say the fuel must have been used in a nontaxable use, and list the allowable types of use for each line. Each line multiplies a printed rate by the gallons claimed, and the amounts add up to the total refund at the top. The form says "Attach to Form 8849. Don't file with any other schedule."
You can fill out Schedule 1 free in your browser on this page and download it without an account.
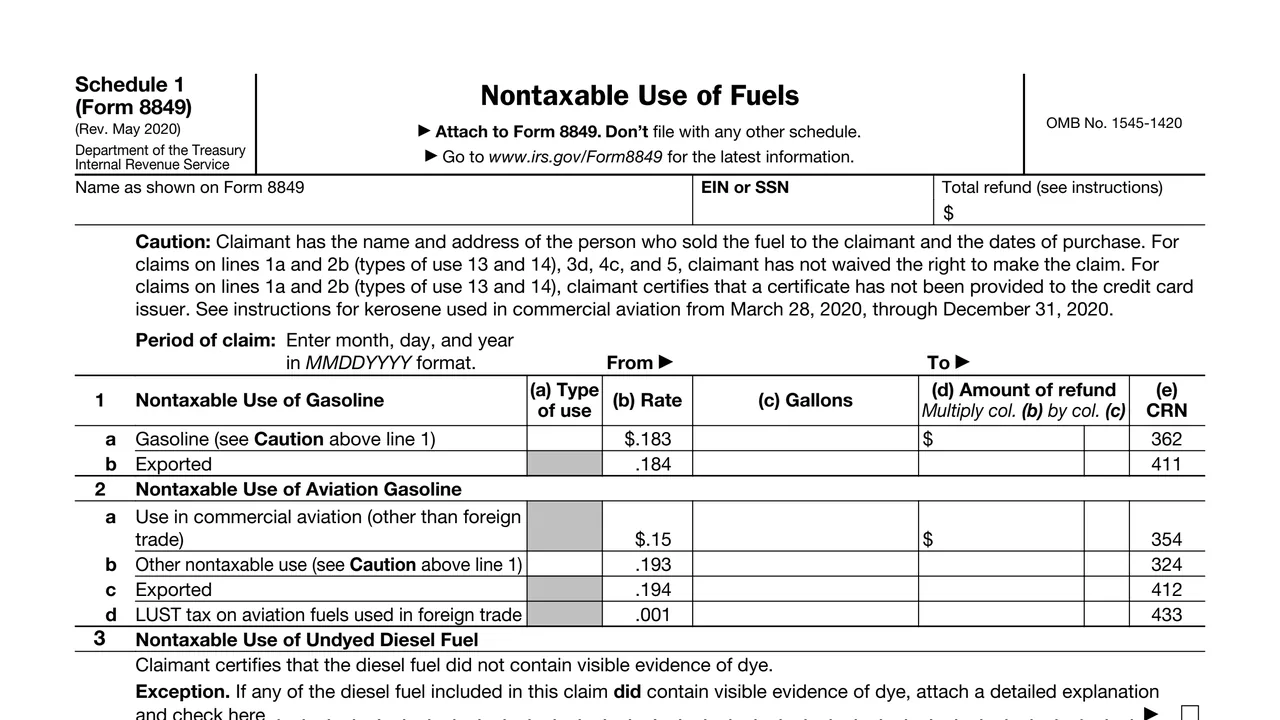
The name and EIN or SSN as shown on Form 8849, the total refund, a caution with the claimant's certifications, and the period of claim in MMDDYYYY format.
Nontaxable use and export of gasoline, aviation gasoline used in commercial aviation or other nontaxable use, and the LUST tax on aviation fuels used in foreign trade.
Nontaxable use, farm use, trains, certain buses and export, each with a certification that the fuel had no visible evidence of dye and a box for exceptions.
Kerosene used in commercial aviation (other than foreign trade), other nontaxable use at two tax rates, and the LUST tax on aviation fuels used in foreign trade.
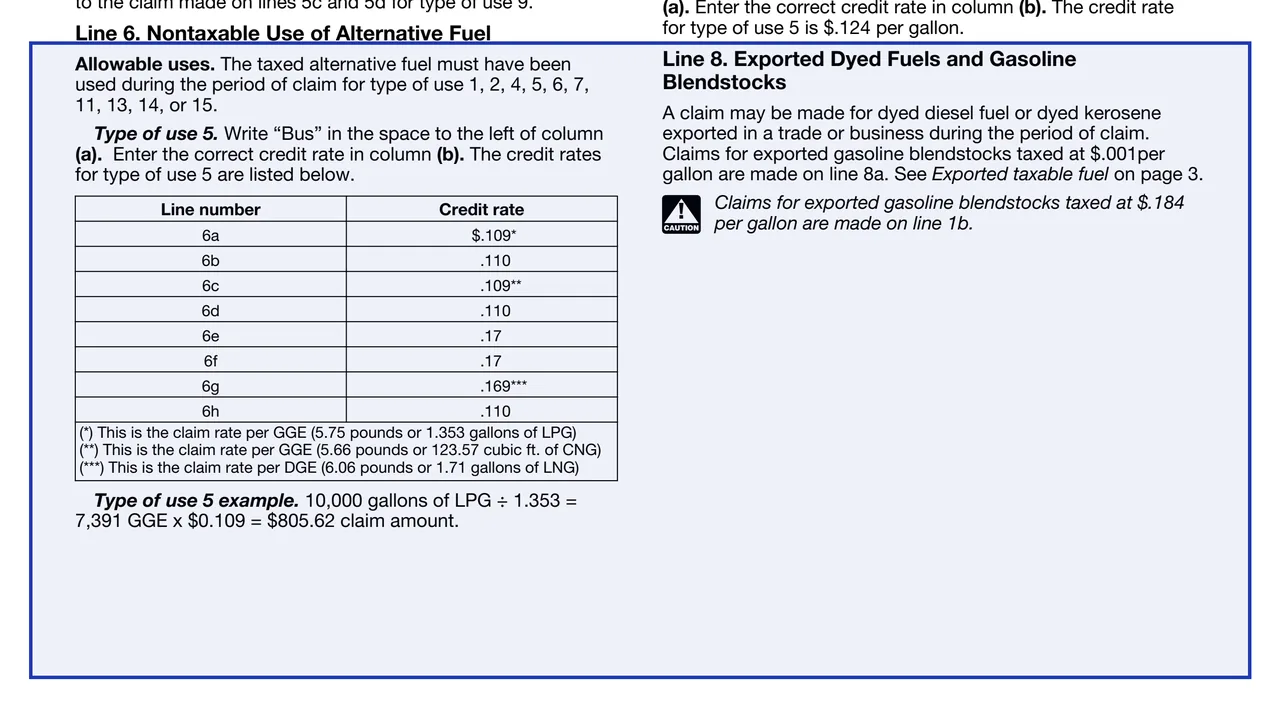
Alternative fuels such as LPG, CNG, LNG and liquid fuel derived from biomass, then a diesel-water fuel emulsion used or exported.
Exported dyed diesel fuel and gasoline blendstocks taxed at $.001, and exported dyed kerosene.
Enter the name and EIN or SSN as shown on Form 8849, and the first and last dates of the period of claim in MMDDYYYY format.
In column (a), enter the type of use number. The instructions list the allowable types for each line and point to the Type of Use Table in the Form 8849 instructions.
Enter the gallons in column (c) and multiply the rate in column (b) by column (c) to get the refund in column (d). Line 6 uses gasoline or diesel gallon equivalents where shown.
For lines 3 and 4, if any of the fuel did contain visible evidence of dye, the form says to attach a detailed explanation and check the box.
Write "Bus" to the left of column (a) and enter the reduced credit rate. The instructions give $.124 per gallon for line 7 and a table of rates for line 6.
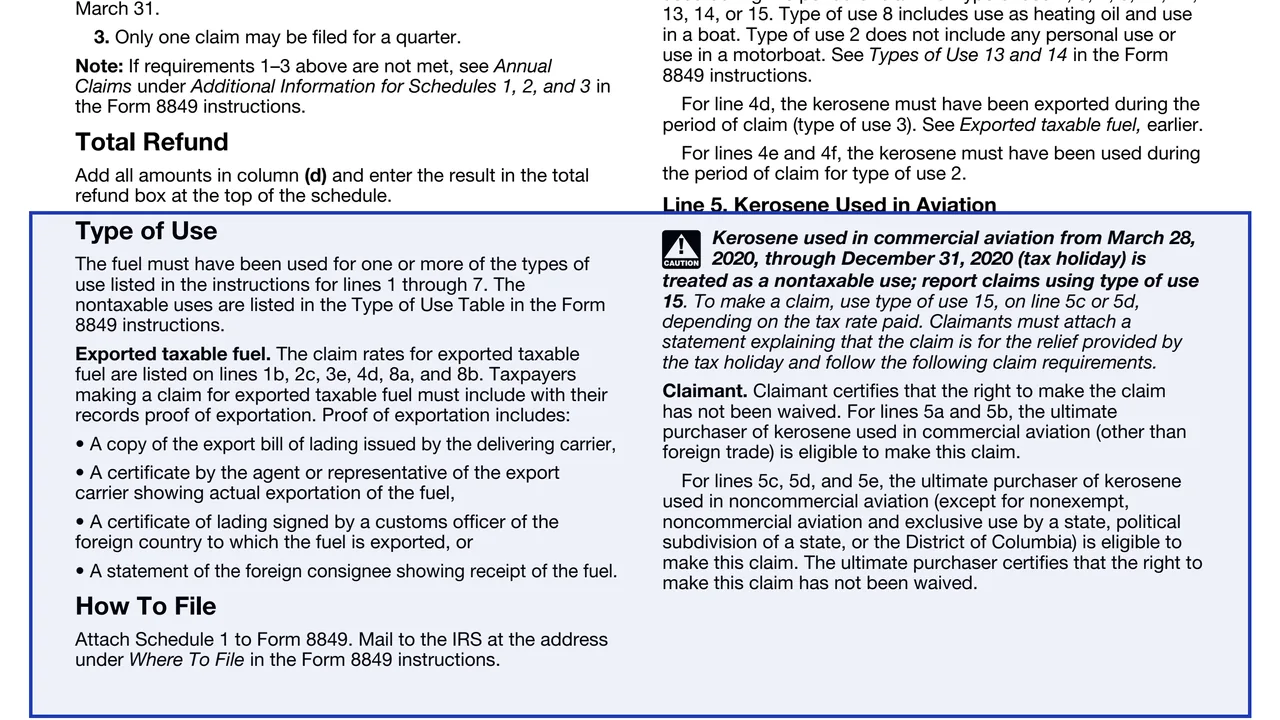
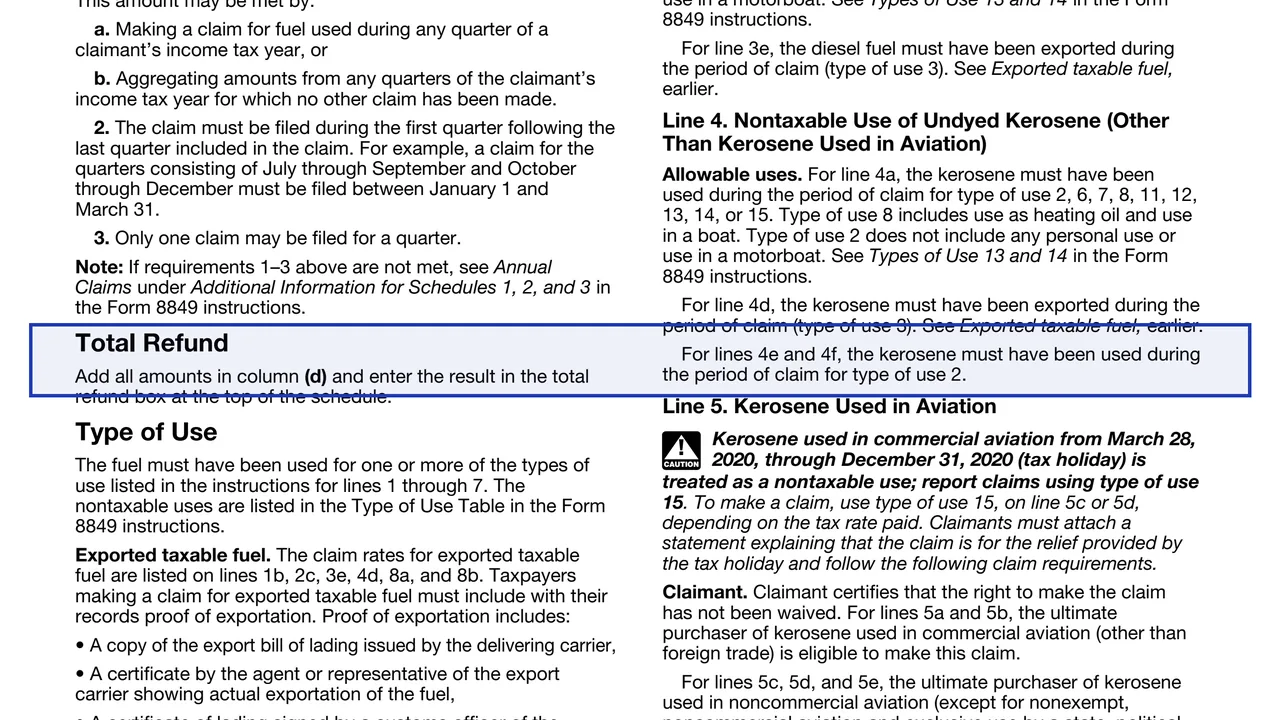
The instructions say to add all amounts in column (d) and enter the result in the total refund box at the top of the schedule.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach Schedule 1 to Form 8849 and mail it to the IRS at the address under Where To File in the Form 8849 instructions. The form says not to file it with any other schedule.
The instructions say the amount claimed on Schedule 1 must be at least $750, which may be met by aggregating quarters of the claimant's income tax year for which no other claim has been made.
The instructions say the claim is filed during the first quarter following the last quarter included. A claim for July through December is filed between January 1 and March 31.
The instructions say only one claim may be filed for a quarter. If the requirements are not met, they point to Annual Claims in the Form 8849 instructions.
For exported fuel, the instructions list proof such as an export bill of lading, a carrier certificate, a foreign customs certificate of lading or a statement of the foreign consignee.
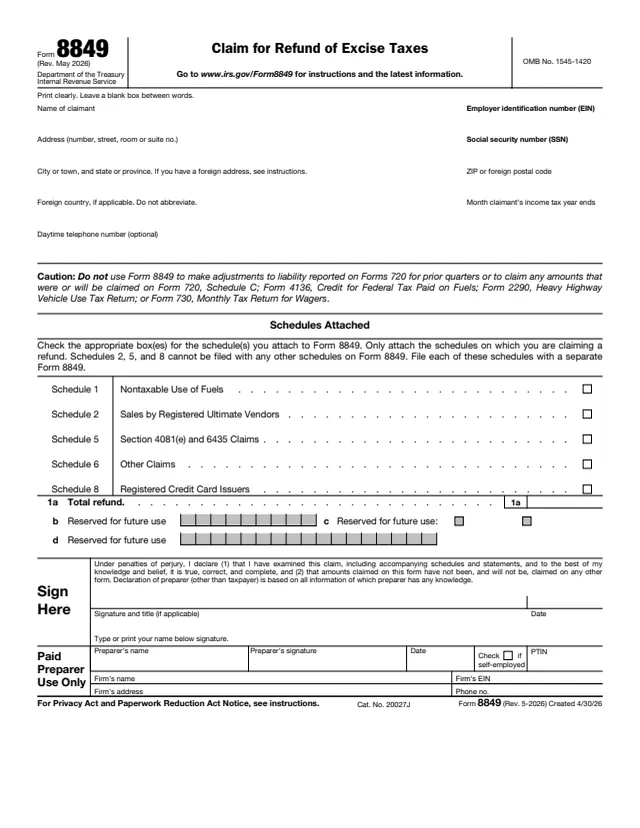
8849
27 fields, 4 pages
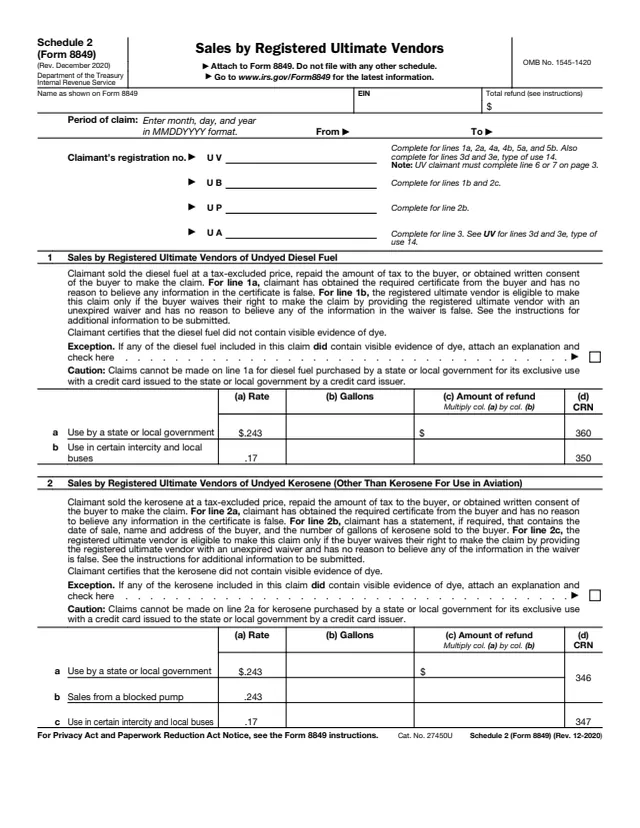
8849 Sch. 2
147 fields, 5 pages
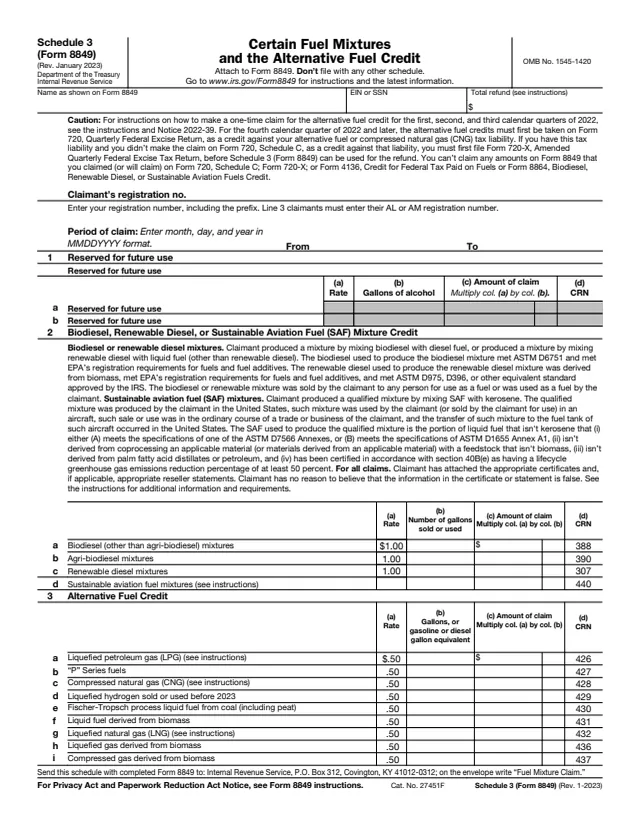
8849 Sch. 3
81 fields, 3 pages
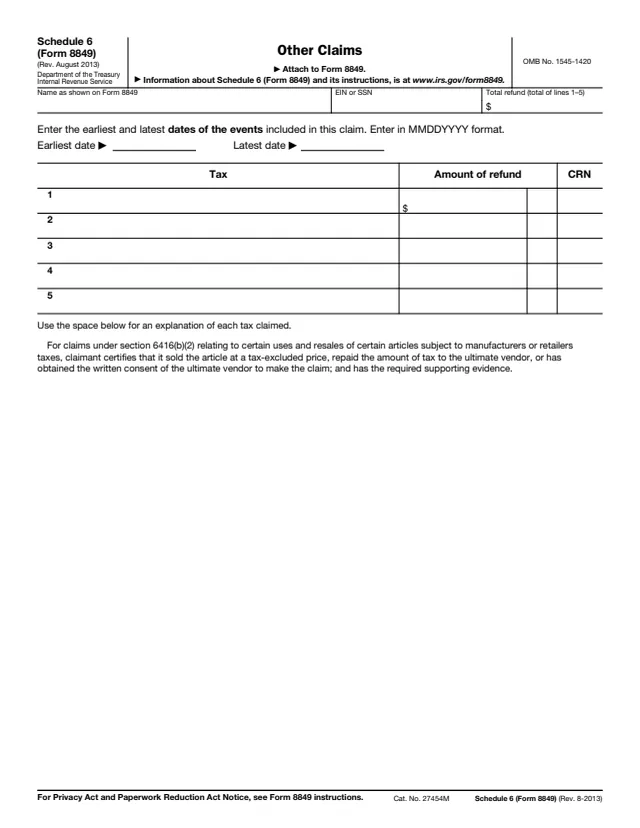
8849 Sch. 6
26 fields, 1 page
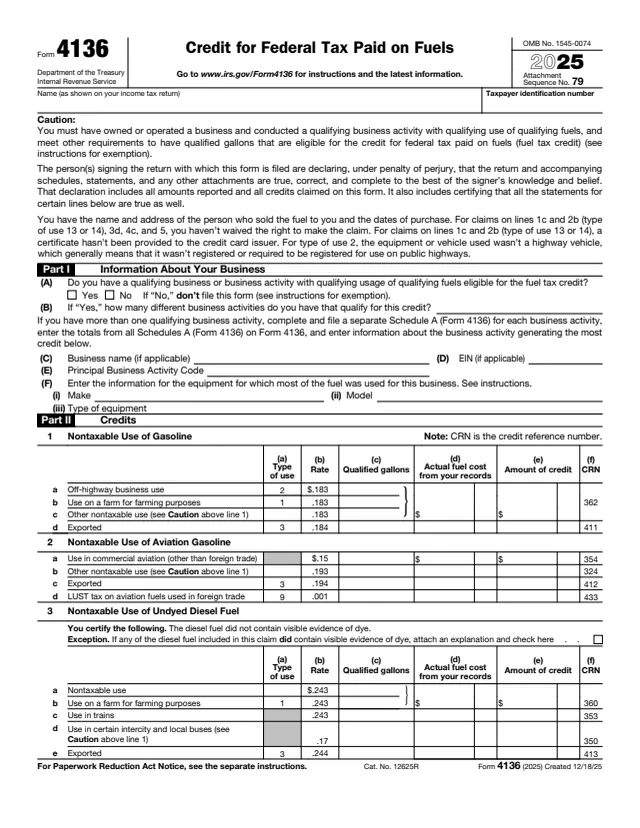
4136
485 fields, 4 pages
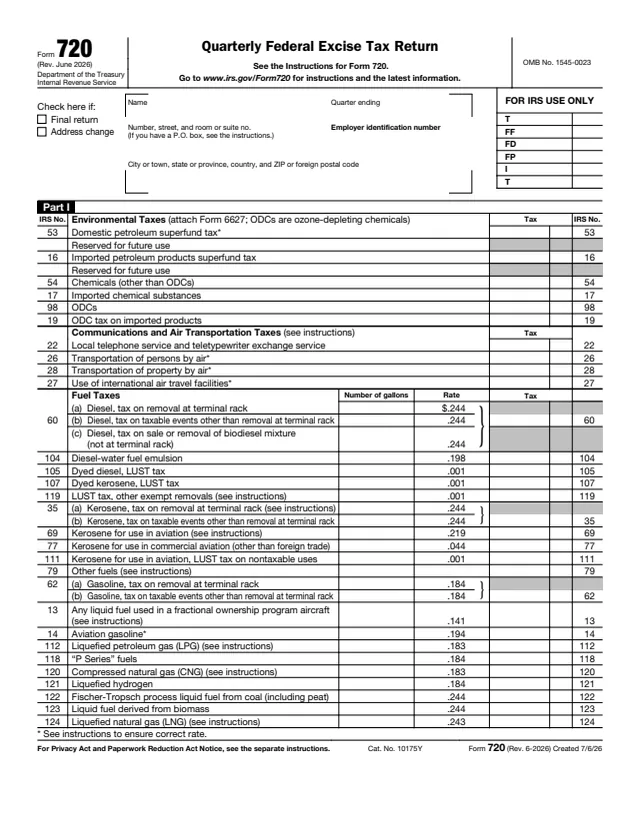
720
715 fields, 8 pages
The ultimate purchaser of the fuel files it with Form 8849, under the name and EIN or SSN shown on that form. It can be a person or a business.
No tool matches that search.
The IRS says an ultimate purchaser of gasoline, gasohol, aviation gasoline, diesel fuel, kerosene, aviation fuel (other than gasoline), and liquefied gas (LPG) uses Schedule 1 to make a claim for refund.
The instructions say the amount claimed on Schedule 1 must be at least $750. If the requirements are not met, they point to Annual Claims in the Form 8849 instructions.
The instructions say during the first quarter following the last quarter included in the claim, with only one claim per quarter.
The form says "Attach to Form 8849. Don't file with any other schedule."
The claimant certifies the fuel had no visible evidence of dye. If any of it did, the form says to attach a detailed explanation and check the exception box.
The schedule says kerosene used in commercial aviation from March 28, 2020, through December 31, 2020 is treated as a nontaxable use, claimed with type of use 15 on line 5c or 5d with an attached statement.