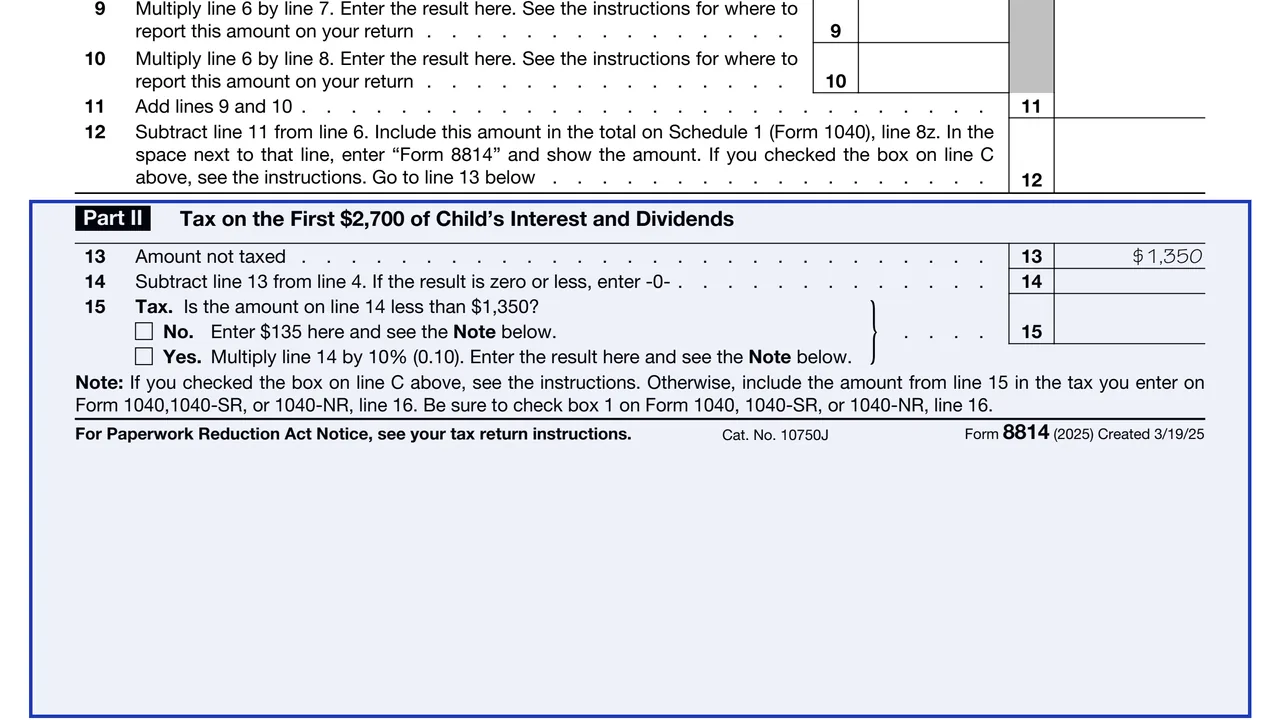
Header and lines A to C
The parents' names and SSN, the child's name and SSN, and a box on line C if more than one Form 8814 is attached.
8814
Parents' Election To Report Child's Interest and Dividends
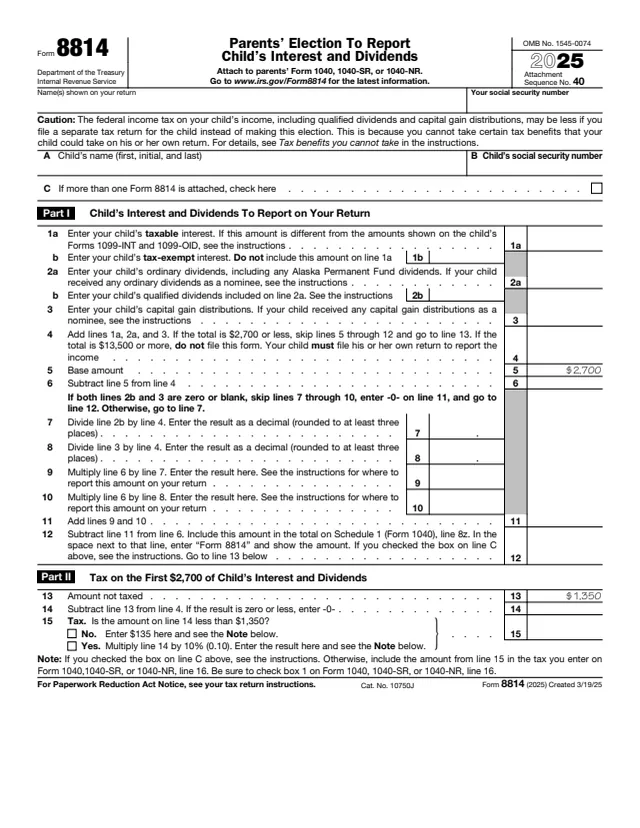
Form 8814, Parents' Election To Report Child's Interest and Dividends, is the 2025 form parents attach to their Form 1040, 1040-SR or 1040-NR to report a child's interest and dividend income on their own return. The IRS says parents use it so the child will not have to file a return.
The instructions list conditions for the child, including that the child was under age 19 (or under age 24 if a full-time student) at the end of 2025, had income only from interest and dividends, including capital gain distributions and Alaska Permanent Fund dividends, and had gross income of less than $13,500. They also describe which parent's return is used.
The form carries its own caution: the tax on the child's income may be less if a separate return is filed for the child, because certain tax benefits the child could take are not available on the parents' return. A separate Form 8814 is used for each child. You can fill out Form 8814 free in your browser on this page and download it without an account.
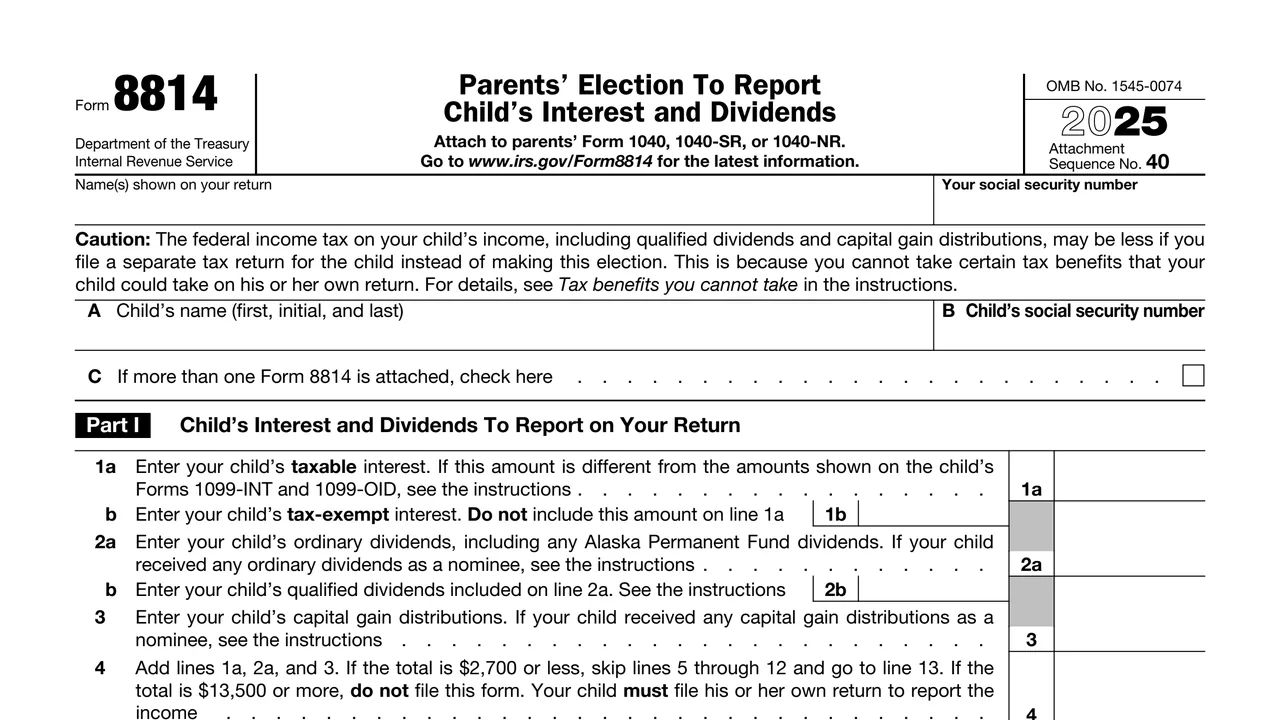
The parents' names and SSN, the child's name and SSN, and a box on line C if more than one Form 8814 is attached.
The child's taxable interest, tax-exempt interest, ordinary dividends, qualified dividends and capital gain distributions, totaled on line 4.
A $2,700 base amount is subtracted, and the rest is split between qualified dividends, capital gain distributions and other income to report on the parents' return.
Line 13 shows $1,350 not taxed. Lines 14 and 15 figure the tax on the rest of the first $2,700: 10% of line 14, or $135.
A note near the top says the tax may be less on a separate return for the child, and points to Tax benefits you cannot take in the instructions.
Enter the name(s) on your return and your SSN. On a joint return, the instructions say to enter both names and the SSN of the person listed first. Then enter the child's name and SSN, and check line C if more than one Form 8814 is attached.
Enter the child's taxable interest on line 1a and tax-exempt interest on line 1b. The instructions say amounts received as a nominee are marked ND on the dotted line and left out of the total.
Enter ordinary dividends (box 1a of Form 1099-DIV), the qualified dividends included in them (box 1b) and capital gain distributions (box 2a), as the instructions describe.
Add lines 1a, 2a and 3. If the total is $2,700 or less, the form says to skip to line 13. Otherwise subtract the $2,700 base on lines 5 and 6.
Divide line 2b and line 3 by line 4, apply the results to line 6, and carry line 12 to Schedule 1 (Form 1040), line 8z with the words Form 8814.
Subtract $1,350 from line 4 and figure line 15. The form says to include line 15 in the tax on Form 1040, 1040-SR or 1040-NR, line 16, and check box 1 on that line.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to parents' Form 1040, 1040-SR, or 1040-NR." The instructions say to file the return by its due date, including extensions.
The instructions say a separate Form 8814 is filed for each child whose income is reported, and the election can be made for some children and not others.
Line 9 goes on Form 1040, lines 3a and 3b, line 10 on Schedule D (Form 1040), line 13 or Form 1040, line 7a, and line 12 on Schedule 1 (Form 1040), line 8z.
The instructions list examples such as the child's additional standard deduction of $2,000 if blind, the penalty on early withdrawal of the child's savings, and the child's itemized deductions.
The instructions say that with qualified dividends or capital gain distributions, the election can mean up to $135 more tax than a separate return, because income between $1,350 and $2,700 is taxed at 10%.
The instructions say Schedule B (Form 1040) is filed if the line 9 amount plus the parents' dividends is more than $1,500, and Part III of Schedule B applies if the child had a foreign financial account or foreign trust.

1040
199 fields, 2 pages
1040
73 fields, 2 pages
1040
72 fields, 1 page
1040
55 fields, 2 pages
1040-NR
171 fields, 2 pages
8938
131 fields, 2 pages
The parent whose return is used makes the election and attaches the form to that return. The instructions say only the parent whose tax return is used can make the election.
No tool matches that search.
The IRS says parents use this form to report their child's income on their return, so the child will not have to file a return.
The instructions list conditions, such as the child being under 19 (or under 24 if a full-time student) at the end of 2025, having only interest and dividend income, and having gross income under $13,500.
Not always. The form's caution says the tax may be less on a separate return for the child, and the instructions describe comparing both methods.
The instructions say a separate Form 8814 is filed for each child whose income is reported. Line C is checked when more than one is attached.
On a joint return, that return. Otherwise the instructions give rules for married, separated, divorced, remarried and never-married parents, often pointing to the parent with the greater taxable income or the custodial parent.
Line 13 of the form shows $1,350 as the amount not taxed, and the instructions say amounts at $1,350 and below are not taxed under this election.