Part I: income from the USVI
Lines 1 to 15 list USVI wages, interest, dividends, business income, gains, retirement income, rental and farm income and other income, totaled on line 16.
8689
Allocation of Individual Income Tax to the U.S. Virgin Islands
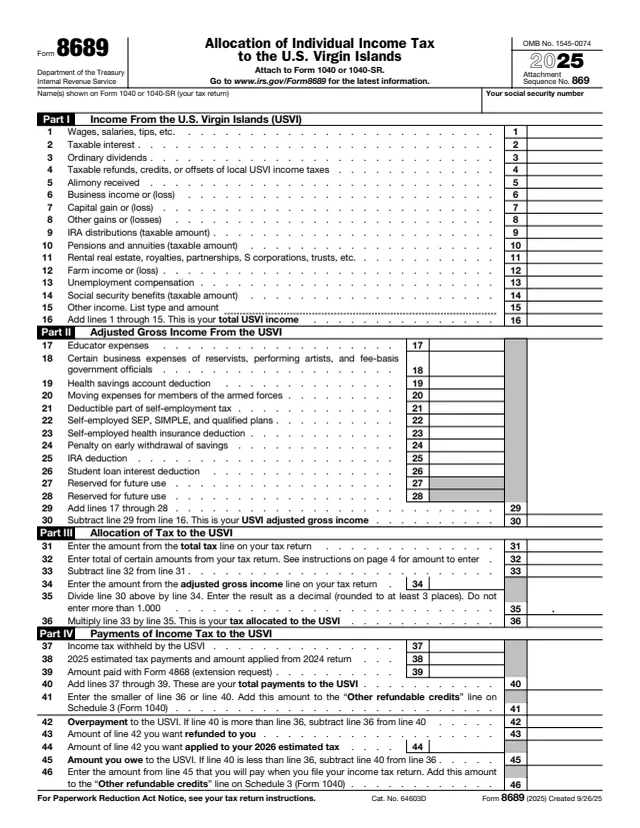
Form 8689 is used to figure the amount of U.S. tax allocable to the U.S. Virgin Islands (USVI). This page covers the 2025 form, which is attached to Form 1040 or 1040-SR.
The IRS says it is used by a U.S. citizen or resident alien, other than a bona fide resident of the USVI, with income from sources in the USVI or income effectively connected with a trade or business in the USVI. The instructions say the USVI tax liability is a percentage of the U.S. tax liability, and that the form is not for a bona fide resident of the USVI for the entire tax year.
The form lists USVI income, subtracts USVI adjustments, allocates part of the U.S. tax to the USVI and records payments made to the USVI. The instructions are printed on pages 3 and 4 of the form. You can fill out the form free in your browser on this page and download the result without an account.
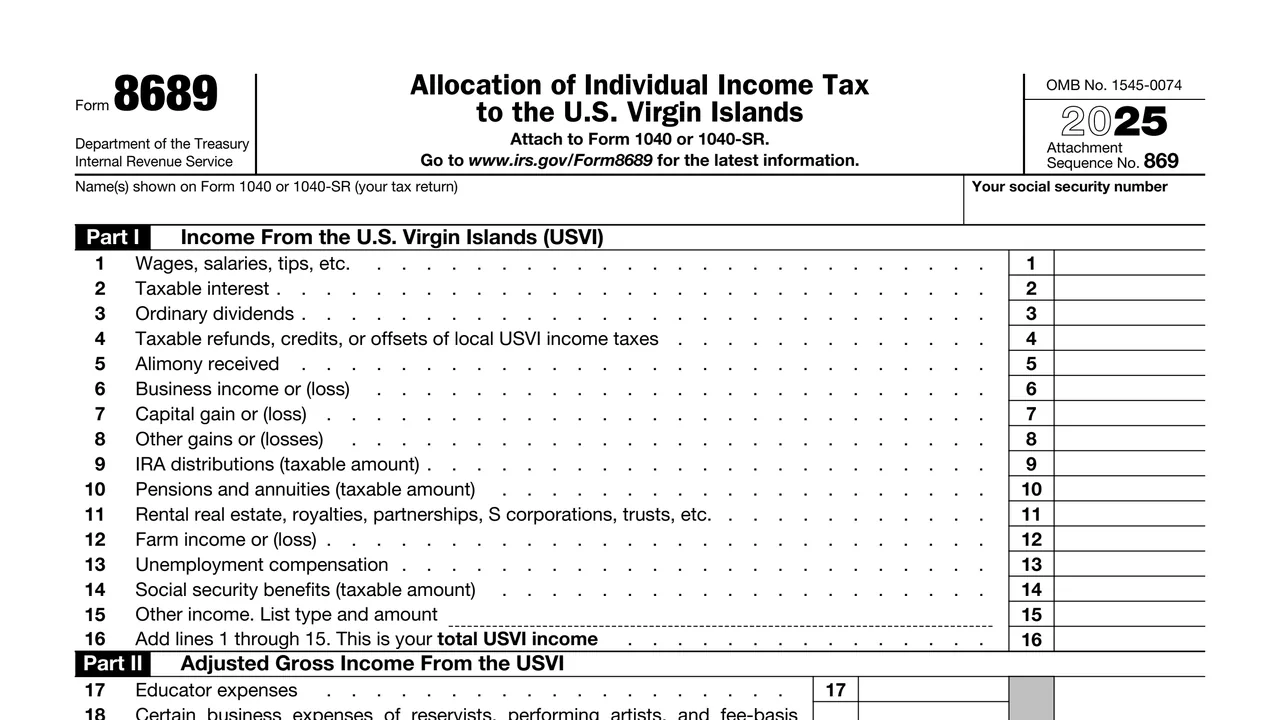
Lines 1 to 15 list USVI wages, interest, dividends, business income, gains, retirement income, rental and farm income and other income, totaled on line 16.
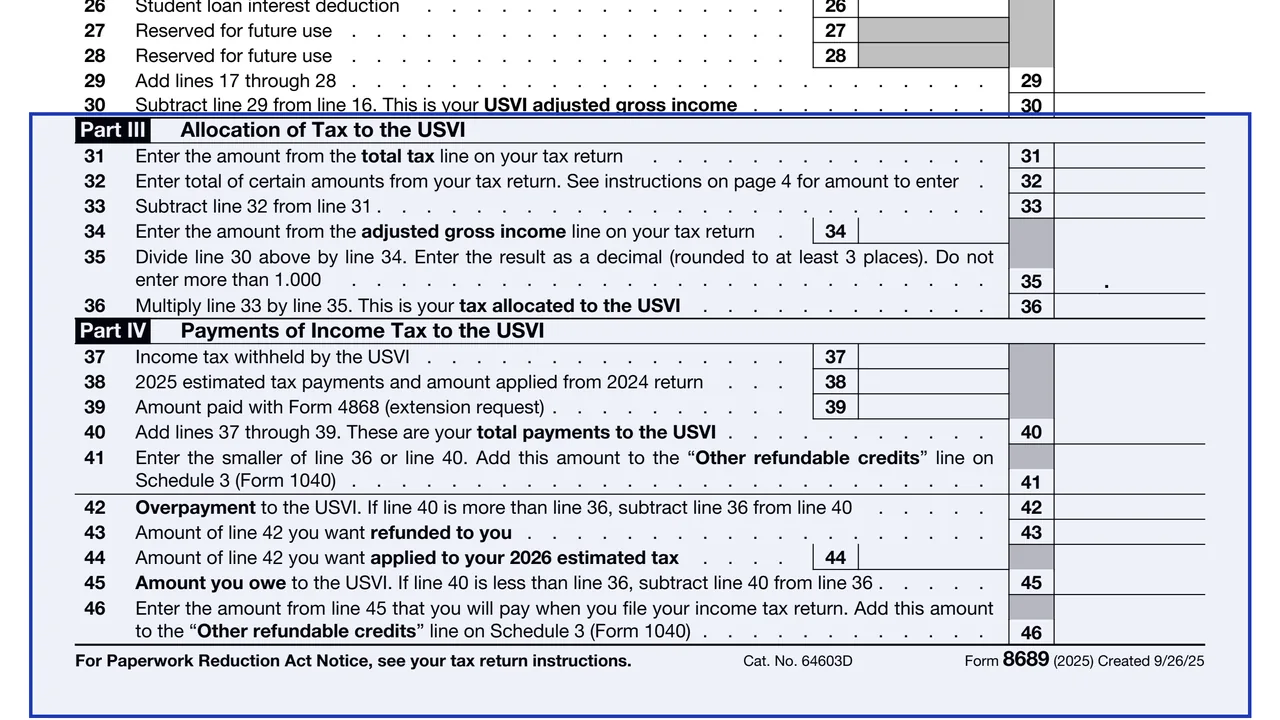
Lines 17 to 28 list adjustments such as educator expenses, HSA, self-employment and IRA deductions. Line 30 is USVI adjusted gross income.
Lines 31 to 36 take the total tax from the return, subtract certain amounts, and multiply by the ratio of USVI AGI to total AGI to get the tax allocated to the USVI.
Lines 37 to 46 total USVI withholding, estimated payments and extension payments, then show any overpayment, refund or amount owed to the USVI.
Enter only USVI source income. The instructions say for wages earned both in and outside the USVI, include on line 1 only the pay earned while in the USVI.
Enter the adjustments that relate to USVI income. For lines 21 to 23 and line 25, the instructions give a ratio of USVI income to worldwide income to apply to each deduction.
Enter the total tax and AGI from the return. Line 32 takes the amounts listed on page 4, and line 35 is a decimal rounded to at least 3 places and no more than 1.000.
Enter USVI income tax withheld from box 2 of Form W-2VI on line 37. The instructions say not to include it on the federal withholding lines of Form 1040.
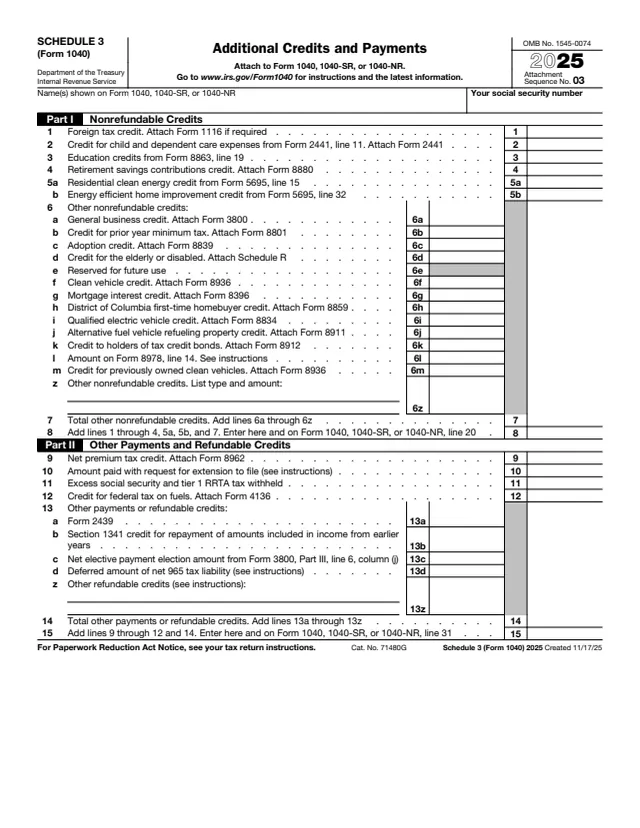
The form says to add line 41 and line 46 to the Other refundable credits line on Schedule 3 (Form 1040).
Attach Form 8689 to Form 1040 or 1040-SR, and file a signed copy of the full return with the Virgin Islands Bureau of Internal Revenue.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say identical tax returns are filed with the United States and the USVI. For the U.S. address, they point to Form 8689 under U.S. Citizen or Resident Alien in chapter 3 of Pub. 570.
The instructions say a signed copy of the return with all attachments, including Form 8689, goes to the Virgin Islands Bureau of Internal Revenue, 6115 Estate Smith Bay, Suite 225, St. Thomas, VI 00802.
The instructions say amounts overpaid to the United States generally will not be applied to the amount owed to the USVI, and amounts overpaid to the USVI will not be applied to the amount owed to the United States.
The instructions say the credit on the U.S. return for U.S. tax allocated to the USVI is available only if the tax was actually paid to the USVI.
The instructions say Form 1040-X can be e-filed with tax software or mailed to the IRS, and a copy is sent to the Virgin Islands Bureau of Internal Revenue.

1040
199 fields, 2 pages
1040
37 fields, 1 page
1040-X
166 fields, 2 pages
W-2
268 fields, 7 pages
8898
99 fields, 2 pages
4868
17 fields, 4 pages
The form is completed by an individual and attached to their own Form 1040 or 1040-SR, with a copy of the return also filed with the USVI.
No tool matches that search.
The form says it figures the amount of U.S. tax allocable to the U.S. Virgin Islands. The instructions say the USVI tax liability is a percentage of the U.S. tax liability.
No. The instructions say not to use it for a bona fide resident of the USVI during the entire tax year, or one treated as such under the special rules for the year of a move.
The instructions say to file a signed copy with the Virgin Islands Bureau of Internal Revenue, 6115 Estate Smith Bay, Suite 225, St. Thomas, VI 00802, which processes it as an original return.
The instructions say income from the USVI generally does not include pay for services there if, among other conditions, the person was not a bona fide resident, worked there 90 days or less and earned $3,000 or less from those services.
On line 37 of Form 8689, from box 2 of Form W-2VI. The instructions say not to include it on the federal income tax withheld lines on Form 1040.
This page covers the 2025 Form 8689. Line 38 refers to 2025 estimated tax payments and line 44 to the 2026 estimated tax.