Line 1: issuer's/transmitter's information
Name, address, city, state/country code, ZIP code, contact name, telephone number and email address.
15397
Application for Extension of Time to Furnish Recipient Statements
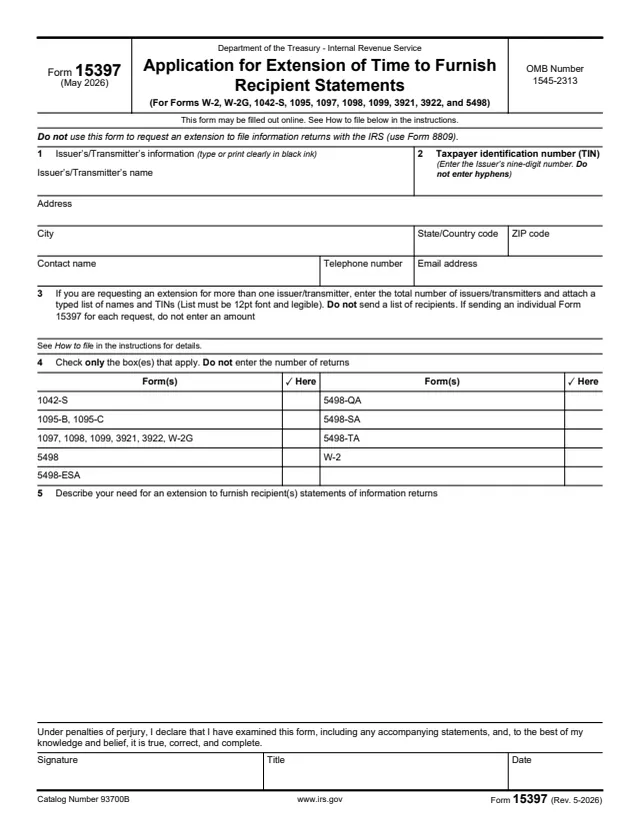
Form 15397 is the Application for Extension of Time to Furnish Recipient Statements. The instructions say it is used to request a one-time extension of up to 30 days to furnish statements of information returns to recipients for the current tax year. The form covers Forms W-2, W-2G, 1042-S, 1095, 1097, 1098, 1099, 3921, 3922 and 5498.
It is filed by the issuer or transmitter of those statements, not by the people who receive them. The form says not to use it to request an extension to file information returns with the IRS; that request uses Form 8809. The instructions also say an approved extension only extends the due date for furnishing statements to the payee or recipient.
The two-page PDF holds the one-page form and its instructions. You can fill out Form 15397 free in your browser on this page and download it without an account.
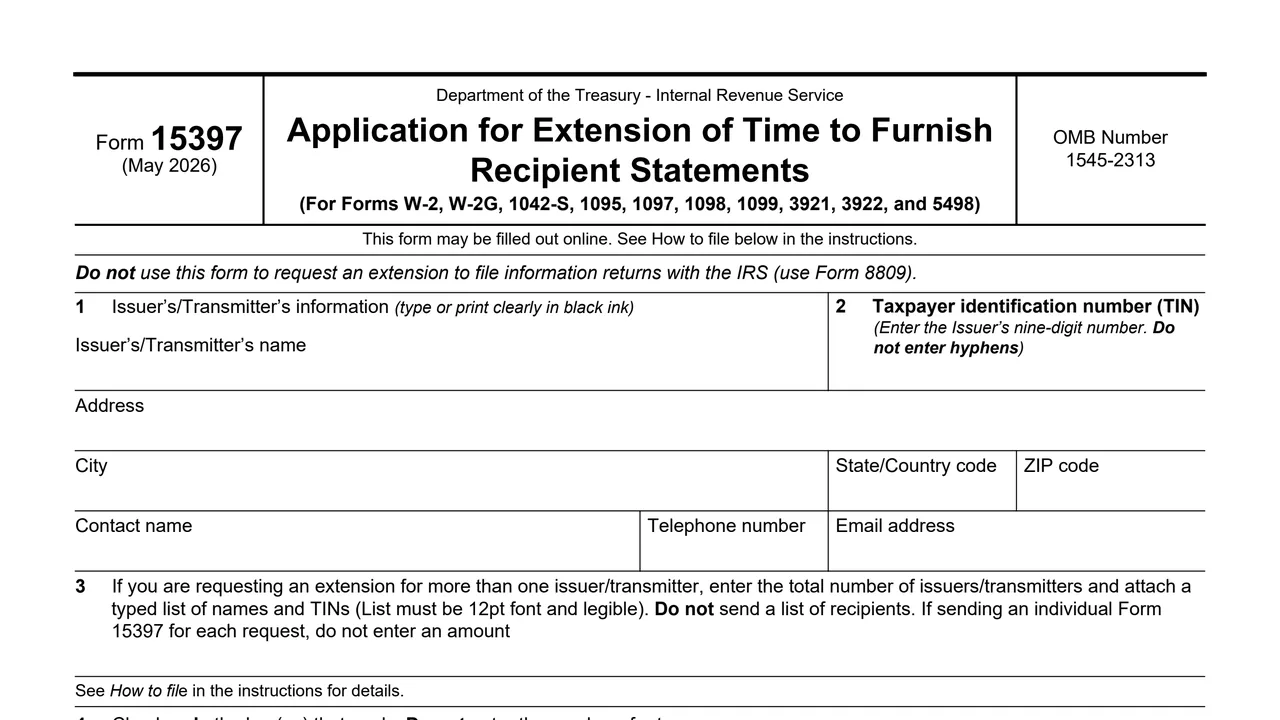
Name, address, city, state/country code, ZIP code, contact name, telephone number and email address.
The issuer's nine-digit number, entered without hyphens.
The total number of issuers/transmitters when one request covers several, with a typed list of names and TINs attached.
Check boxes for 1042-S; 1095-B and 1095-C; 1097, 1098, 1099, 3921, 3922 and W-2G; 5498; 5498-ESA; 5498-QA; 5498-SA; 5498-TA; and W-2.
A space to describe the need for an extension to furnish recipient statements.
A declaration under penalties of perjury, with signature, title and date.
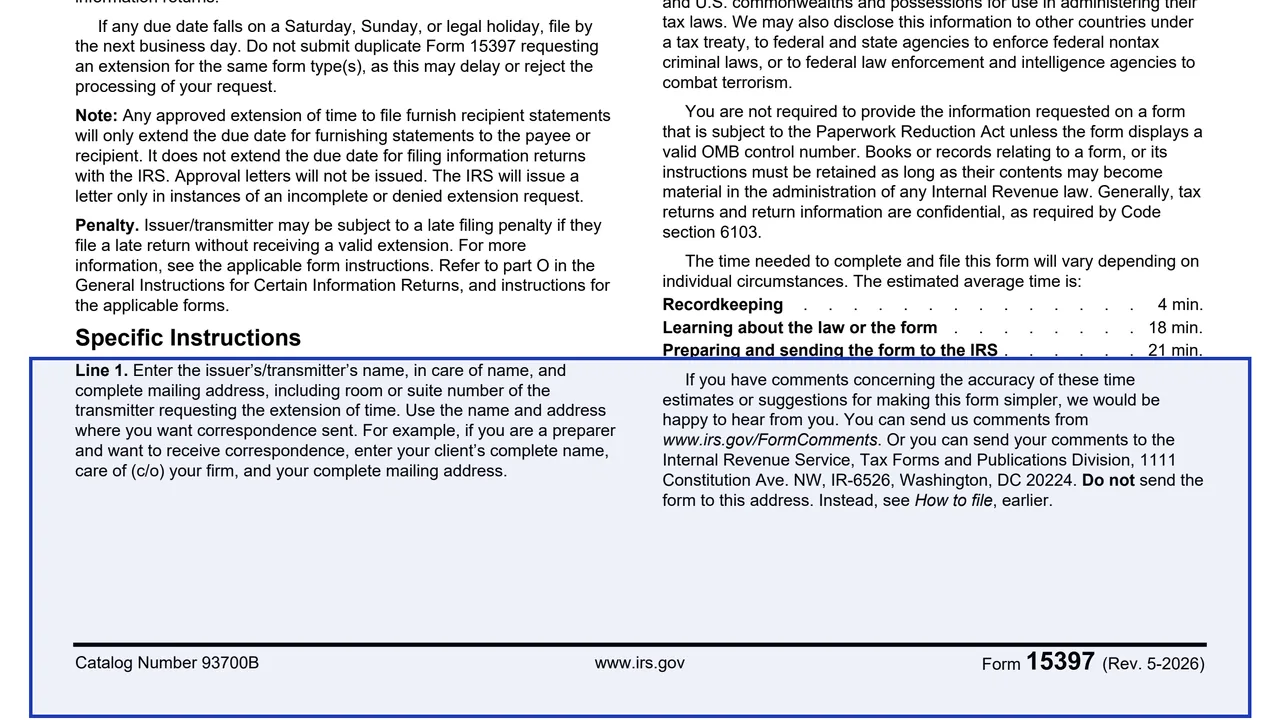
Enter the issuer's/transmitter's name, any in care of name, and the complete mailing address where correspondence goes. The instructions say the legal name and TIN match the name given when the EIN was applied for, with no abbreviations. Add a contact who knows the request.
Enter the issuer's nine-digit EIN, QI-EIN, WP-EIN or WT-EIN without hyphens. The instructions say a filer not required to have an EIN or QI-EIN enters a social security number.
For several issuers/transmitters, enter the total and attach a typed list of names and TINs in 12pt font. The form says not to send a list of recipients, and to leave this blank when sending a separate Form 15397 for each request.
Check only the boxes for the form types that apply. The form says not to enter the number of returns.
Explain why more time is needed. The instructions say to specify the types of amounts being reported, such as Form 5498 contributions or Form 1099-MISC amounts in boxes 8 or 10, and to note composite recipient statements.
The instructions say the issuer/transmitter or a person duly authorized to sign a return signs the form, then add the title and date.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
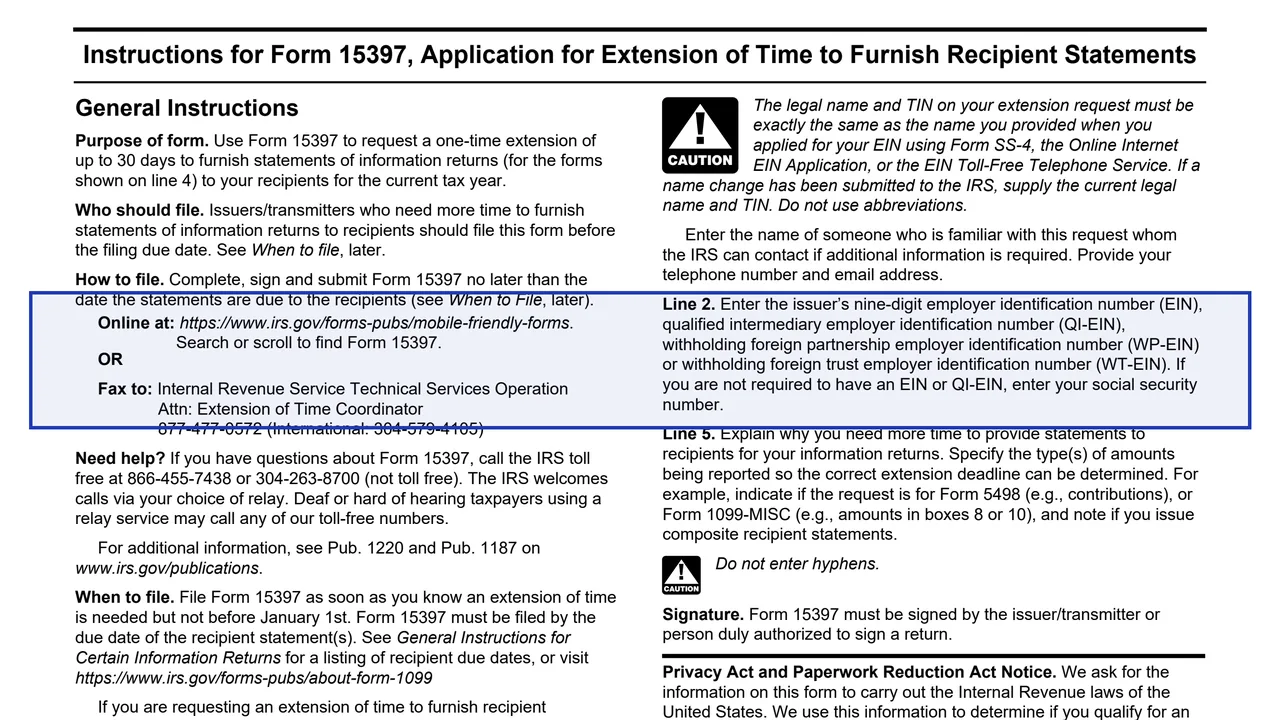
The instructions list two ways: online at https://www.irs.gov/forms-pubs/mobile-friendly-forms (search or scroll to find Form 15397), or by fax to Internal Revenue Service Technical Services Operation, Attn: Extension of Time Coordinator, at 877-477-0572 (International: 304-579-4105).
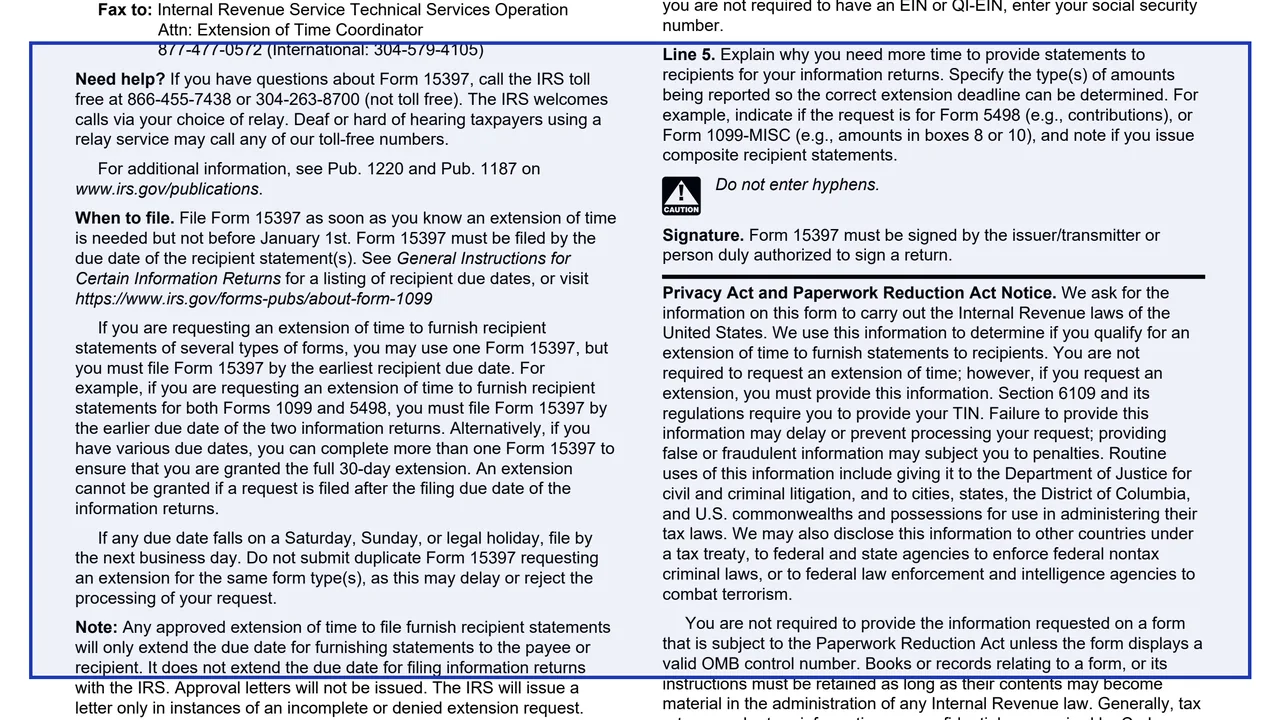
As soon as the need for an extension is known, but not before January 1st, and no later than the due date of the recipient statements. A due date on a Saturday, Sunday or legal holiday moves to the next business day.
One Form 15397 can cover several form types, filed by the earliest recipient due date. The instructions say more than one Form 15397 can be completed when due dates differ, to get the full 30-day extension. Duplicate requests for the same form types may delay or reject processing.
The instructions say it does not extend the due date for filing information returns with the IRS. That request uses Form 8809.
The instructions say approval letters will not be issued. The IRS issues a letter only for an incomplete or denied extension request.
The instructions list the IRS at 866-455-7438 (toll free) or 304-263-8700 (not toll free), and point to Pub. 1220 and Pub. 1187.
8809
32 fields, 2 pages
SS-4
89 fields, 2 pages
W-2
568 fields, 11 pages
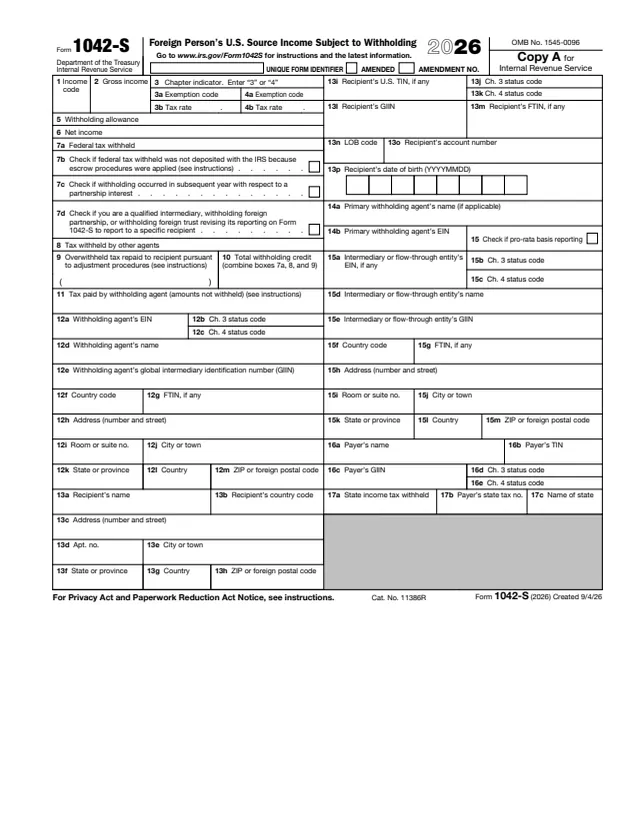
1042-S
300 fields, 7 pages
5498
83 fields, 4 pages
1098
41 fields, 4 pages
The instructions say issuers/transmitters who need more time to furnish statements of information returns to recipients file this form. It goes to the IRS Technical Services Operation.
No tool matches that search.
The instructions say it requests a one-time extension of up to 30 days to furnish statements of information returns to recipients for the current tax year.
No. The instructions say an approved extension only extends the due date for furnishing statements to the payee or recipient. The form points to Form 8809 for an extension to file information returns with the IRS.
The instructions say approval letters will not be issued. A letter is sent only when the request is incomplete or denied.
Yes. Line 4 has boxes for several form types. The instructions say a request covering several types is filed by the earliest recipient due date, or separate forms can be filed for different due dates.
No. The instructions say to file it as soon as an extension is known to be needed, but not before January 1st.
The instructions describe a preparer entering the client's complete name, care of the firm, and the firm's mailing address on line 1. The form is signed by the issuer/transmitter or a person duly authorized to sign a return.